

Repeated road maneuvers
Backing, curbside stops and re-entering traffic expose pedestrians, parked cars and nearby property.
Try a different word, or check the spelling.
The point where delivery ends can decide whether a parcel is still in your custody when it disappears. Fleet and cargo protection should fit that handoff and peak van or depot values, with shipping-partner deductions and seasonal drivers considered separately from porch theft.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
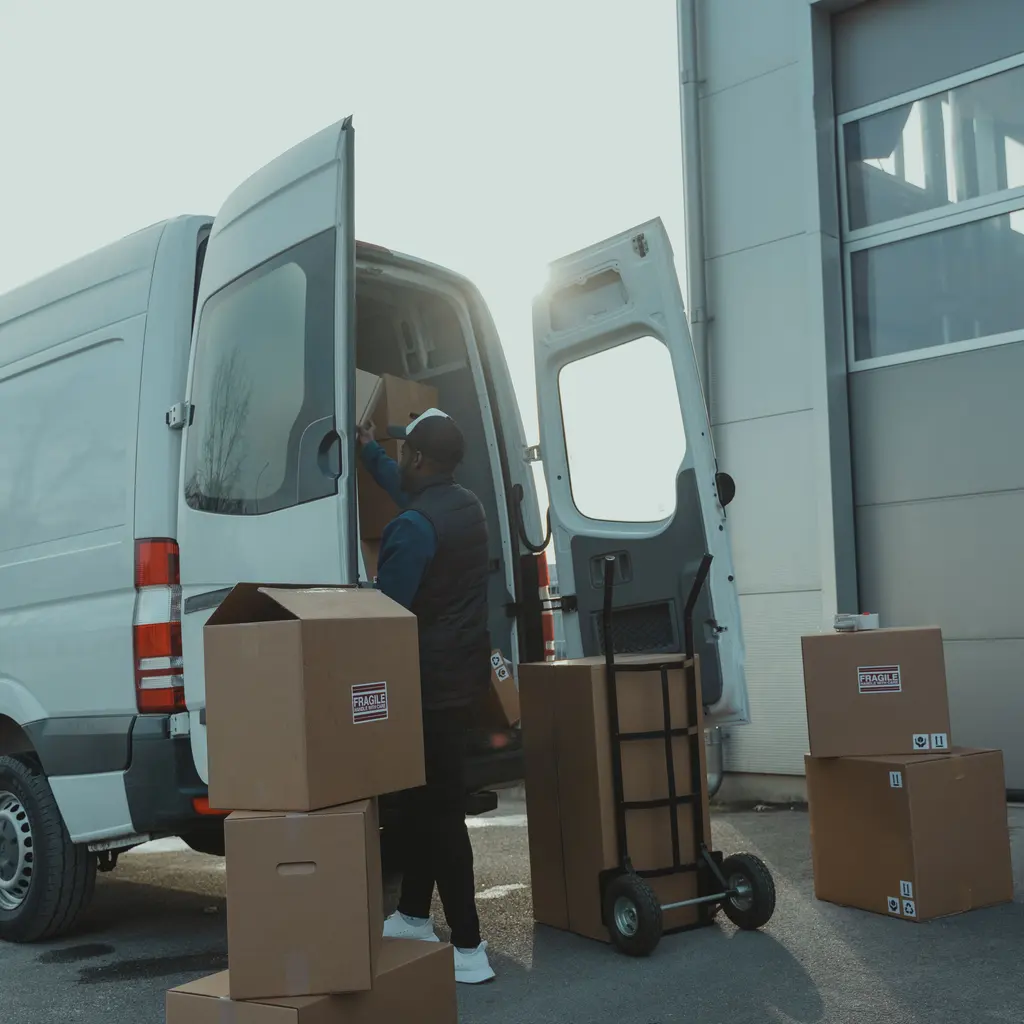
You manage a fleet making frequent stops along residential and business routes, which increases the likelihood of collisions and driver injuries from lifting parcels. Seasonal spikes in volume can further complicate your insurance and safety planning.
The Southern Agency can review your fleet size, seasonal staffing, and delivery practices to help you select appropriate insurance. We can help you coordinate coverage for vehicle incidents with staging-area risks.
Backing, curbside stops and re-entering traffic expose pedestrians, parked cars and nearby property.
New or seasonal drivers face unfamiliar routes, lifting duties, and repeated entry and exit from vans.
A loaded van or staged depot area can hold peak values. Porch theft after delivery may fall outside custody cover.
A shipping partner can impose deductions, limits, and insured-party requirements that differ from the fleet's own policies.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A driver damages a parked vehicle. Auto liability addresses covered third-party claims; the van's damage needs physical-damage cover.
A route driver is injured carrying a parcel. The employee's compensation arrangement governs the injury claim.
Packages are damaged in a minor crash. Cargo values, limits, and terms determine recovery independently of vehicle repairs.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Frequent stops, backing, and vehicle entry create repeated opportunities for loss. Review actual loss history rather than assuming one cause.
It can set requested terms. Compare each requirement with policy wording and endorsements before claiming it is satisfied.
Only within suitable cargo terms, limits, and custody periods. Check overnight storage and unattended-vehicle conditions.
It can document behavior and support training. Insurers assess the information; no particular discount or outcome is guaranteed.
Applicable compensation can address employee route injuries. Describe temporary and contractor arrangements separately.
Consider severe auto and premises claims beyond primary limits. Confirm that delivery operations and relevant underlying forms are accepted.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.