

Unsteady boarding
A step between a fixed dock and a moving boat can lead to a fall against the craft or into the water.
Try a different word, or check the spelling.
A gondola's hull, a fixed dock and a passenger stepping between them do not share the same insurance interest. Marine and shoreside terms need your actual boarding duties, with salvage, crew status and flood treatment addressed beyond an ordinary premises or equipment policy.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
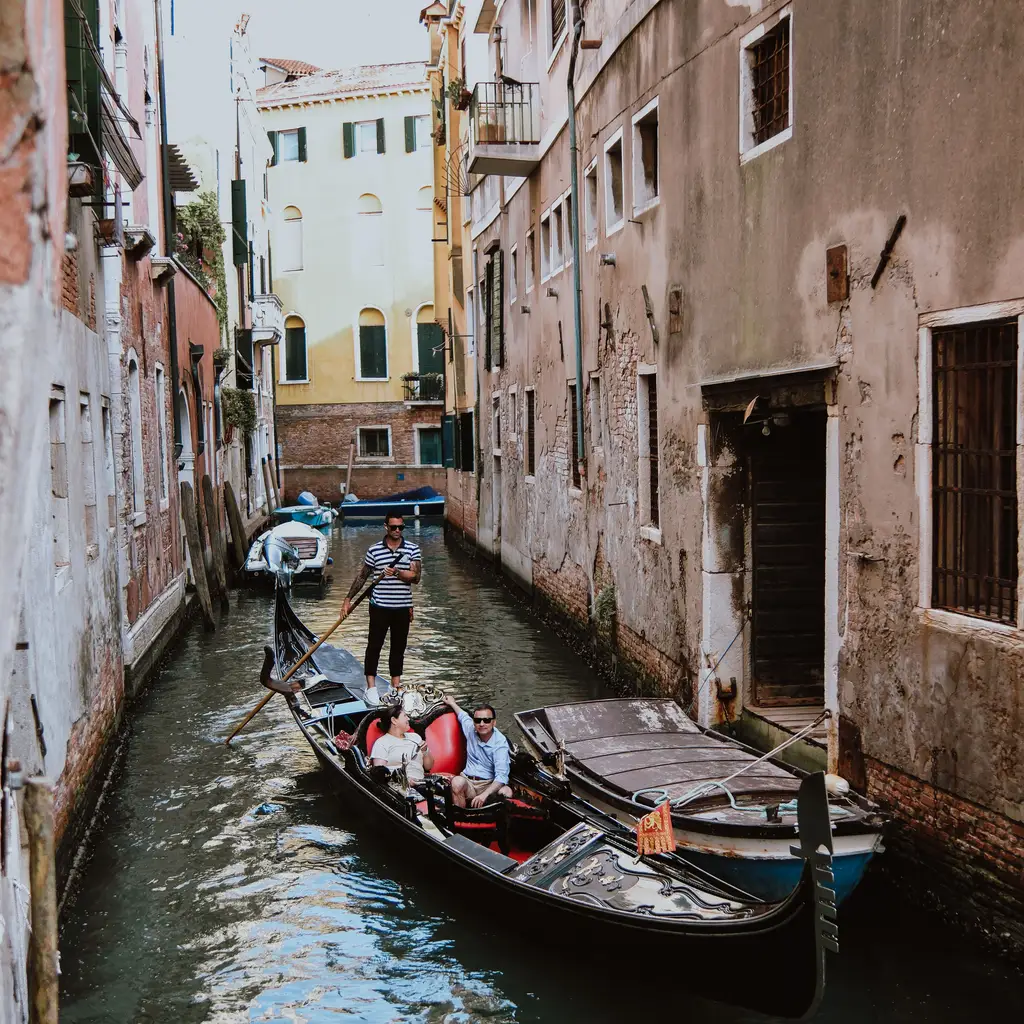
You operate gondola rides that take passengers along waterways, where risks range from dockside injuries to incidents while passengers are aboard the boat. The transition between the dock and the narrow craft is a critical point for safety and liability.
The Southern Agency can review your boat operations and dockside facilities to help you select appropriate insurance. We can help you integrate your marine insurance for the vessels with premises liability for the land-based ticketing and boarding areas.
A step between a fixed dock and a moving boat can lead to a fall against the craft or into the water.
Passing vessels, wind or sudden passenger movement can swamp or capsize a small boat.
A storm, submerged object or collision can damage different assets with different insurance treatment.
Poling, balancing and helping guests create injuries whose legal treatment depends on crew and employer status.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A passenger is hurt against the dock. Marine versus premises liability depends on duties, facts and exclusions.
The boat is damaged and needs recovery. Hull, salvage, and operating-water terms determine protection.
A crew member is hurt assisting a passenger. Maritime status and the injury arrangement determine the response.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Ordinary GL may exclude the craft and passenger activity. Review suitable marine passenger liability and its boarding scope.
Portable equipment may need inland marine, but boats generally require suitable marine hull terms. The policy label alone is insufficient.
Potentially, under appropriate marine or premises protection. The location of the fall does not by itself determine the insurer.
Review legal crew status and duties. Vessel crew and shoreside workers can need different injury arrangements.
Hull terms may address covered damage, sinking, or salvage. Values, waters, causes, and exclusions determine recovery.
Operating waters and weather rules matter to safety and underwriting. They do not insure routine canceled bookings.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.