

Errors in analysis or recommendations
An inaccurate test result or flawed agronomic recommendation can cause crop loss or wasted inputs, leading to professional liability claims from clients.
Try a different word, or check the spelling.
A test report can determine what a grower spends on the next crop. Your insurance needs to account for the advice in that report as well as the instruments and samples behind it.
The Southern Agency can help you review your laboratory services, field activities, and data systems to support your insurance selections.
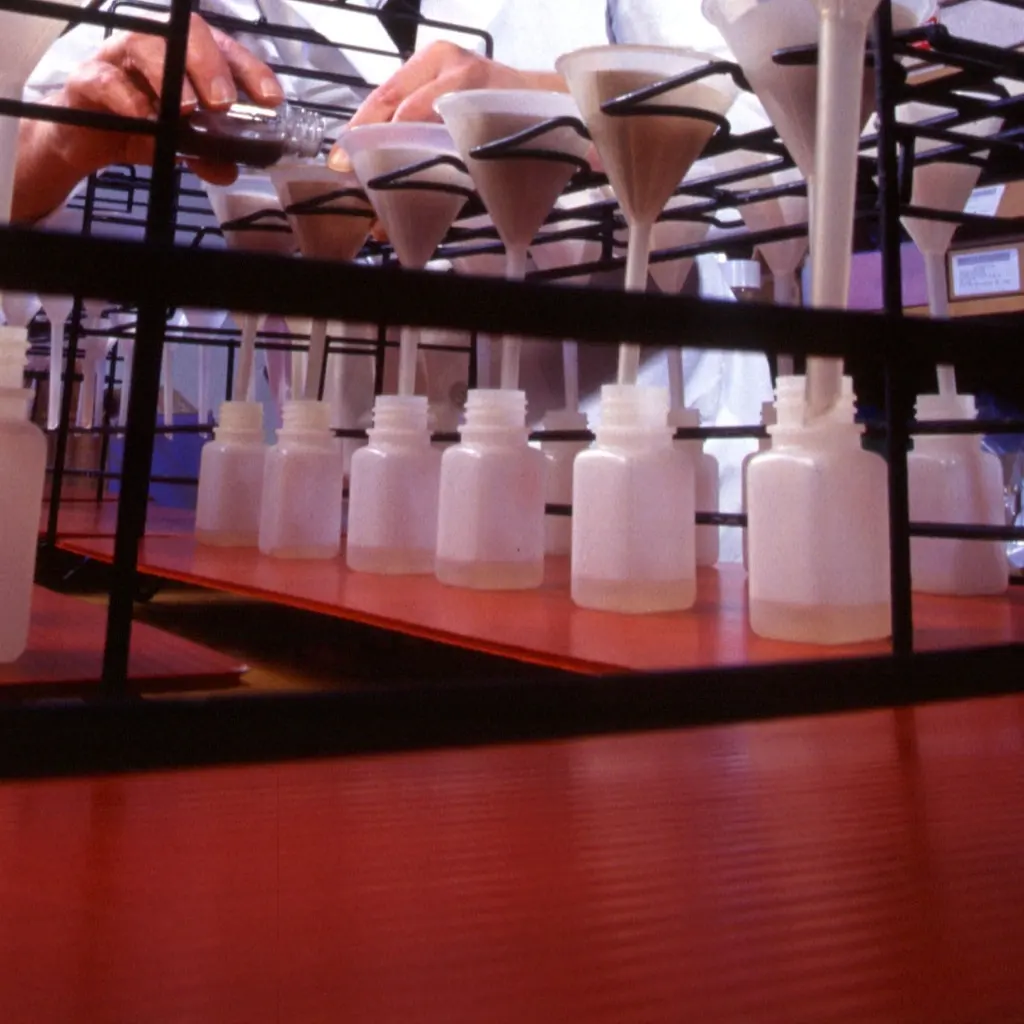
Your soil testing and analysis business relies on precise sampling and interpretation to guide client decisions. If a sample is handled incorrectly or a report contains an error, a client may face financial loss that could lead to a liability claim against you.
The Southern Agency can review your laboratory instruments, field collection procedures, and report-data systems to help select appropriate insurance. For example, we can discuss professional liability for your advisory services.
An inaccurate test result or flawed agronomic recommendation can cause crop loss or wasted inputs, leading to professional liability claims from clients.
Mislabeled, cross-contaminated, or swapped samples can produce wrong results that affect planting, fertilization, or remediation decisions.
Spectrometers, analyzers, drying ovens, and balances are essential to throughput, and a failure can delay results and disrupt client commitments.
Lab solvents, acids, and reagents create exposure to spills, releases, and technician injury during sample preparation and testing.
Technicians driving to farms and remediation sites face vehicle accidents and injuries while collecting samples in varied terrain.
The lab stores field maps, yield records, and proprietary client data that could be exposed in a cyber incident or breach of confidentiality.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a grower alleges that a nutrient recommendation led to wasted inputs and crop loss. Applicable professional terms may address a covered claim and defense, subject to insured services, causes, and reporting. The sampling responsibility, report use, and policy dates matter; disappointing yields or an agreement to refund fees do not alone establish insured negligence or damages.
Hypothetical: a spectrometer fails during peak testing and reports are delayed. Applicable breakdown terms may cover an eligible instrument and cause, subject to wear and other conditions. Repair, affected samples, temporary outside testing, lost income, and promised turnaround penalties have different coverage questions.
Hypothetical: an intrusion exposes field maps, yield records, and client contacts. Applicable cyber terms may address covered response or liability costs, subject to the incident, information, and reporting conditions. Notification duties need qualified review, and data restoration, changed test reports and contractual confidentiality claims are not automatically included in the same payment.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not on its own. Consider the client decisions and potential losses tied to the report, including inputs, crop damage, or a land-use decision. Compare that exposure with defense costs and per-claim and aggregate limits rather than assume a small testing fee means a small claim.
Document who chose and collected it, what the lab agreed to test and how the report could be used. A representative sample and accurate analysis are different responsibilities. Client collection does not automatically remove every professional allegation or insure resampling and refunds.
If coverage is claims-made, compare prior acts, retroactive dates, and claim-notice provisions before the change. Ask how outstanding reports and any extended reporting option are handled. A new policy does not automatically preserve all earlier work.
Not by itself. Establish the physical cause and compare the instrument and failure with the breakdown terms. Repair, repeat analysis, affected samples, outside testing, and client-delay costs can have different treatment.
Have the policy's information and incident definitions reviewed against the records you hold and the providers you use. Incident response, notification, restoring data, altered reports, and contract claims need separate consideration. A confidentiality promise does not expand the policy by itself.
No service label establishes that. Describe the contaminants, site work, laboratory methods, report use, and any remediation advice explicitly. Compare professional, field-release, chemical, and sample-custody terms; finding contamination and causing or spreading it are different issues.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.