

Underground utility strikes
Trenching and boring can hit buried gas, electric, water, or fiber lines, causing dangerous and costly damage the installer may owe for.
Try a different word, or check the spelling.
Your responsibility does not necessarily end when the trench is filled and the water runs. Coverage for work in progress and claims after installation needs to fit the systems you put in the ground.
The Southern Agency can help you identify the insurance needs for your installation work and equipment fleet.
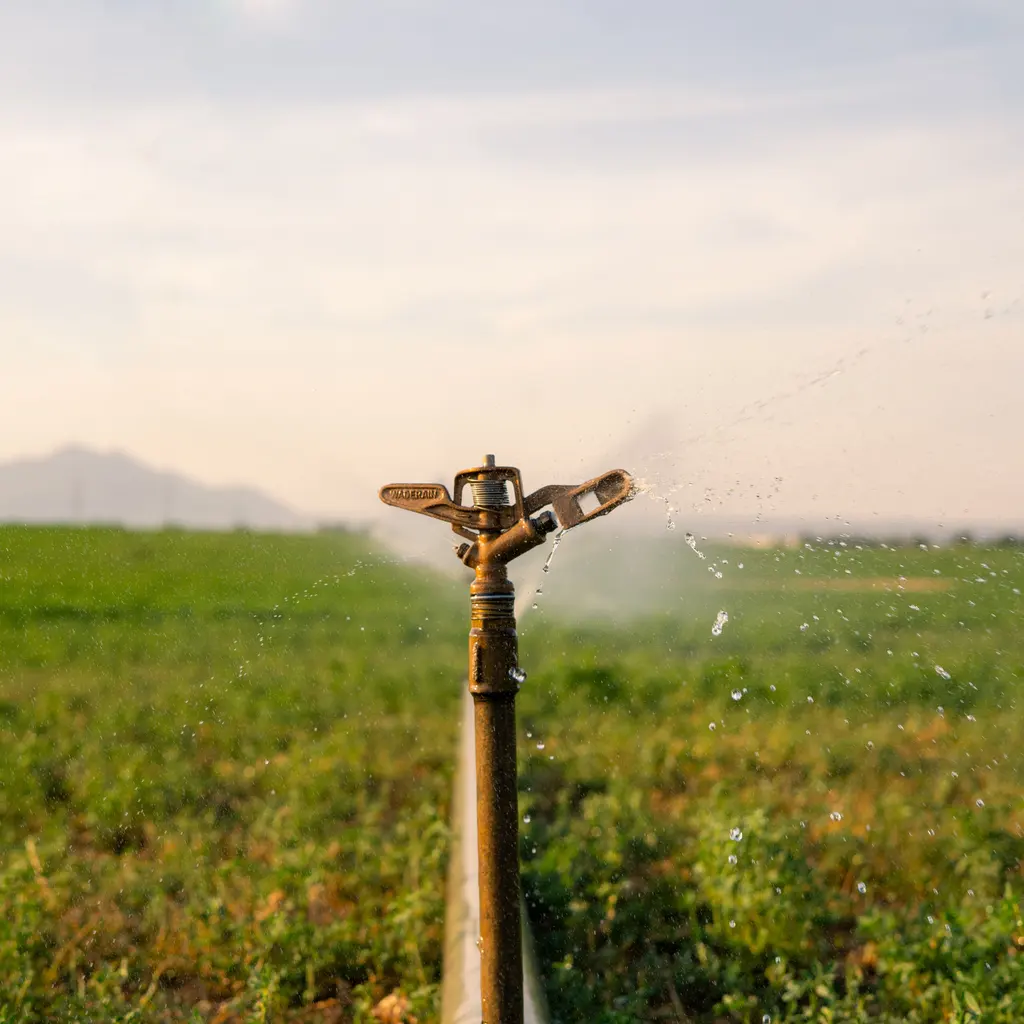
You install and maintain irrigation infrastructure, including trenching, pumping, and wiring for various fields. A utility strike during digging or an inadequate system design that fails under pressure can create significant liability and repair demands.
The Southern Agency can review your installation techniques, subcontractor use, and project types to help you select appropriate insurance. For example, we can help you determine if a performance bond is required for a specific contract or if your equipment needs coverage for field transit.
Trenching and boring can hit buried gas, electric, water, or fiber lines, causing dangerous and costly damage the installer may owe for.
A system that leaks, over-waters, or fails can flood or damage a customer's crop, field, or landscape, raising completed-operations claims.
Excavation, lifting pipe, and outdoor labor expose crews to trench cave-ins, equipment, and strain injuries on the jobsite.
Trenchers, pumps, controllers, and pipe staged on jobs or carried on trucks are exposed to theft and damage away from a fixed base.
Some projects request limits, insured-party endorsements or particular bonds. Agreeing to a contract does not establish availability, compliance or which bond obligations apply.
Wiring pumps, timers, and controls introduces electrical and equipment exposures if components fail or are installed incorrectly.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: trenching cuts an unmarked fiber line, and its owner demands repair costs while nearby businesses claim outage losses. General liability may help pay defense costs and the installer's covered liability for line repairs if the policy includes the underground operations and the claim. An unmarked line does not by itself decide fault or coverage. Assess line repairs and resulting loss of use separately from other business-outage demands. Coverage for the damaged line does not establish payment of every business's outage claim.
Hypothetical: a connection fails after handoff and water damages a grower's crop. Applicable completed-operations liability may address covered resulting property damage. Replacing the connection, redoing the system, crop/work-property exclusions, design allegations and promised yield or watering results are separate questions.
Hypothetical: a trencher and pumps awaiting installation are stolen from a jobsite. Contractor's equipment coverage may help pay to replace the insured trencher. Installation coverage may help pay for pumps included at that location and stage of work. Identify the owners and any rental obligations, then check valuation, deductibles, and theft and security conditions. A truck policy, tools list or base-stock policy does not automatically insure every rented machine, installation material or job-delay cost.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
No. Review actual underground operations, utility/site information, damage, responsibility, and policy exclusions/conditions. Line damage, resulting loss of use and other business-outage demands need separate assessment.
Do not assume so. Review defective components/work, resulting crop or other-property damage, work-property/professional exclusions, and the facts after handoff. Warranty, watering or crop-yield promises are not automatic insurance benefits.
Disclose in-house and subcontracted advice/design and contractual promises. Check professional-service definitions and actual liability forms. If claims-made terms are proposed, prior-service dates, reporting and continuity need specific review; design cover does not establish every construction or performance loss.
Not necessarily. Separate owned/rented equipment from installation stock and customer property, with values, transit/storage, testing, acceptance, and theft terms. A truck or tools policy does not establish all materials or job-delay costs.
Payment and performance bonds have different purposes: payment concerns eligible suppliers/subcontractors and performance concerns the contract's completion duties. Review the actual bond, obligee, conditions, and indemnity; neither label substitutes for liability insurance.
Compare the actual requested insured parties, ongoing/completed endorsements, limits, work scope, and bonds with the issued terms. Contract promises, private requirements and operating/worker rules are distinct; signing or supplying a certificate does not amend a policy.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.