

Design and specification disputes
A client may claim a recommended material, color, or layout caused costly rework or failed to match what was promised, triggering a professional liability allegation.
Try a different word, or check the spelling.
A client's chosen artwork or antique may spend time in your care before it reaches the finished room. Protection for those items deserves attention alongside liability for your recommendations.
The Southern Agency can help you manage your dual exposure as both a professional advisor and a hands-on installer.
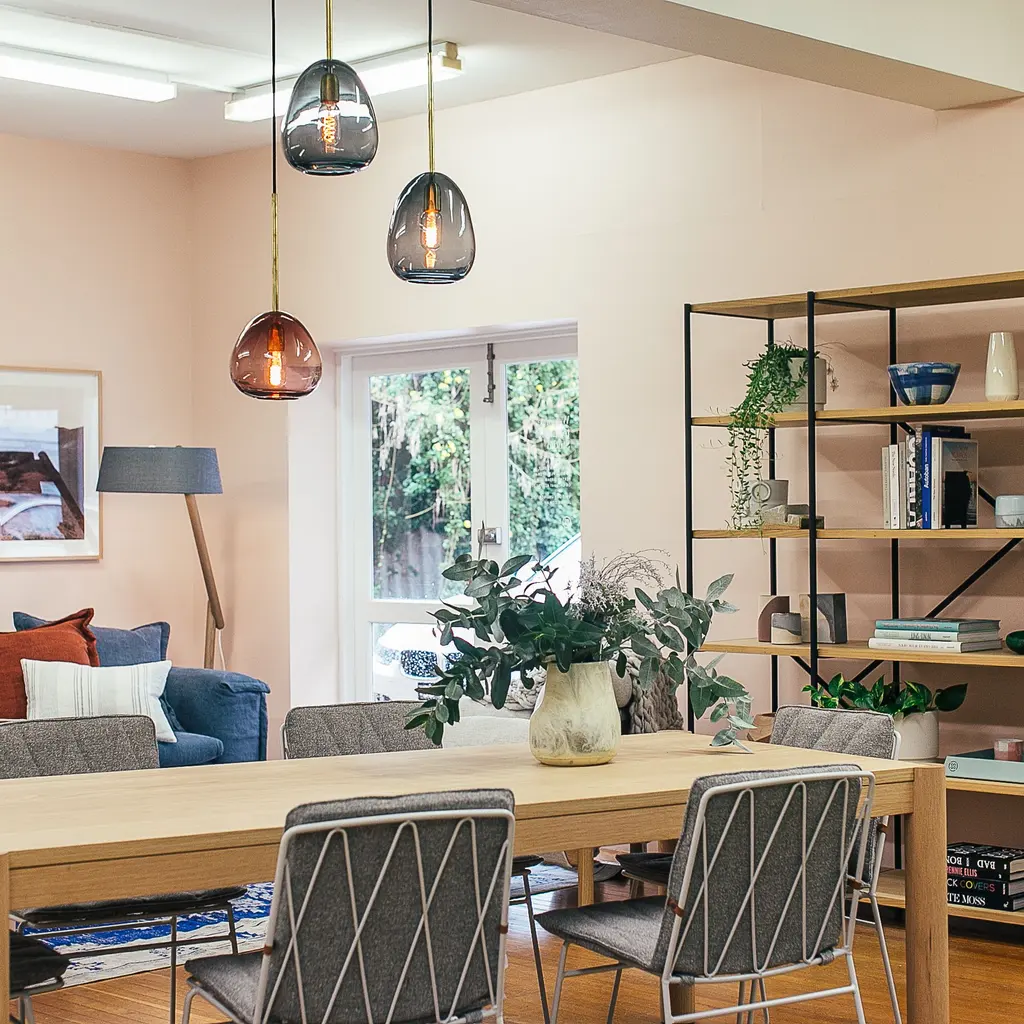
You help clients choose layouts, fabrics and furnishings, then may buy, stage or arrange installation of those pieces. A specification dispute differs from a dropped object or scratched floor. If you handle art, antiques or custom goods, ordinary stock values may not reflect what is at risk.
The Southern Agency can review your advisory, resale and installation duties to help choose insurance. We can compare defined professional services with liability for resulting site damage and protection for goods in your care, separating dissatisfaction or a promised result from an allegation of negligent advice.
A client may claim a recommended material, color, or layout caused costly rework or failed to match what was promised, triggering a professional liability allegation.
Moving furniture, hanging window treatments, or installing fixtures in an occupied home can damage floors, walls, or existing valuables.
Art, antiques, rugs, and custom pieces are frequently moved between showrooms and client sites, where they can be damaged, lost, or stolen.
Clients, household members, or other trades may be injured by tools, ladders, or items staged during an installation.
Fire, theft, or water damage at the studio can destroy sample libraries, fabrics, computers, and held inventory awaiting delivery.
Decorators often direct painters, upholsterers, and installers, and a mistake by an uninsured helper can expose the lead firm.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: an antique table is scratched while a new piece is positioned. Establish whether it was handled or was surrounding property, ownership and documented value, then review custody/work-property and customer-goods terms. GL and inland marine are not interchangeable guarantees.
Hypothetical: an owner says upholstery wore poorly and demands a room redo. Preserve intended use, suitability/care advice, approved sample, supplier and warranty records. Review alleged negligent defined services separately from normal wear, dissatisfaction, product replacement and a promised result.
Hypothetical: custom lighting is stolen en route. Identify title/risk of loss, valuation, carrier and vehicle, handling stage, packing and theft/security terms. Auto insurance on the vehicle or a studio inventory limit alone does not establish protection for the lighting.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Describe the layouts, specifications, sourcing advice or regulated services you actually provide and what the contract promises. E&O may address a covered allegation of negligent defined services, subject to exclusions and reporting terms. Disliking a scheme or demanding a room redo does not by itself establish insured negligence.
Inland marine coverage is commonly used to protect art, rugs, and custom pieces in transit between showrooms and client sites, depending on the specific policy and limits selected.
General liability commonly responds to third-party property damage at a client site, such as scratched floors or marked walls, depending on policy terms and underwriting.
Describe paid advice, purchases, client goods, delivery and any visitors or staff, alongside samples, computers and inventory at home. An eligible BOP may combine specified property and liability, but home-studio use and services need acceptance. Professional advice and high-value goods in transit or processing need separate review.
Not automatically. Identify actual employers, mover/installer duties and issued policies and endorsements. The Southern Agency can compare requested rights with those terms; a certificate alone neither makes a subcontractor insured under your policy nor guarantees a defense for you or coverage for its work.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.