

Property damage during entry or installation
Drilling locks, forcing entry, or installing hardware can damage doors, frames, safes, and electronic panels at a customer's location.
Try a different word, or check the spelling.
A customer's access credentials can remain in your records after the service visit ends. Protecting that information is a different responsibility from covering damage to a door or loss of the van's tools.
The Southern Agency can review your mobile service operations to help you select appropriate insurance.
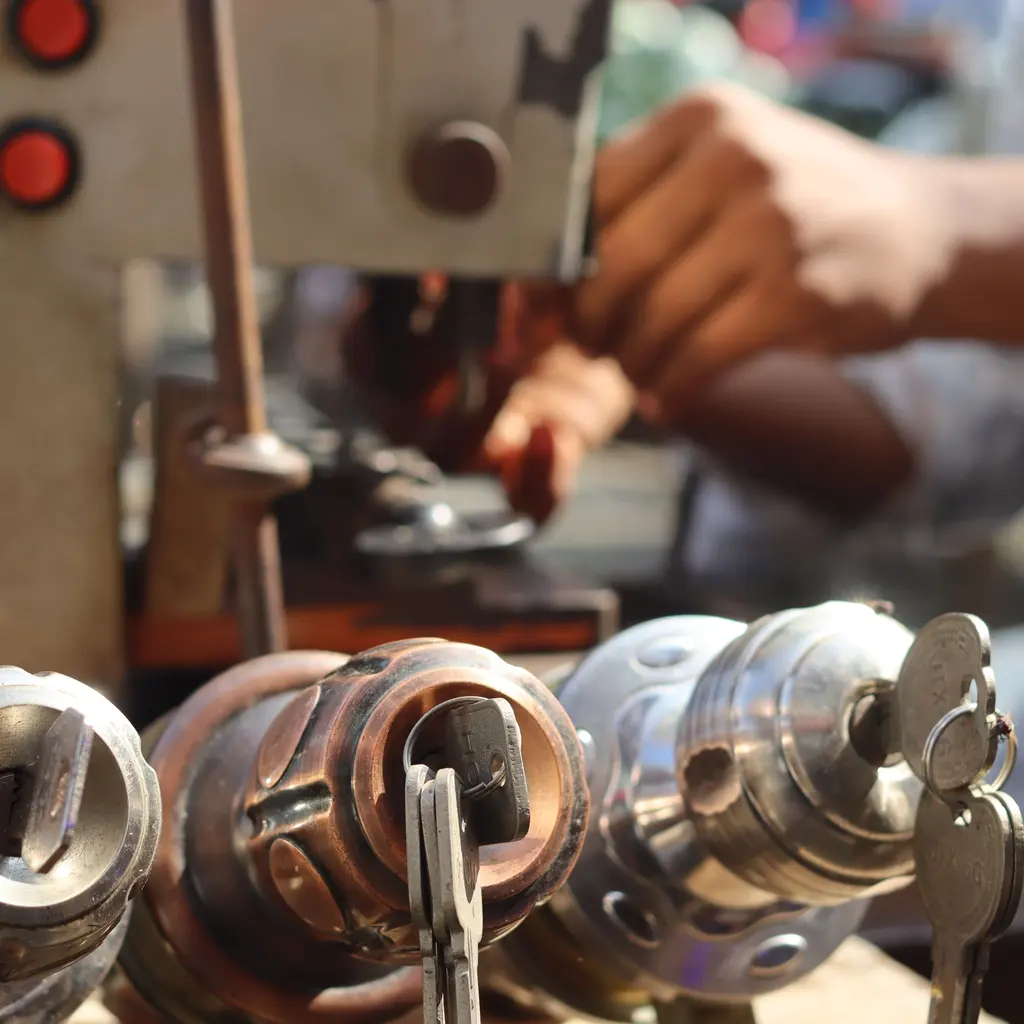
You install and repair locks and electronic access systems, often at customer sites, and you hold keys and security credentials. Your professional access to a client's security systems creates unique crime and liability risks.
The Southern Agency can review your mobile service operations to help you select appropriate insurance. For example, we can discuss how your policy covers theft allegations versus accidental property damage during a service call.
Drilling locks, forcing entry, or installing hardware can damage doors, frames, safes, and electronic panels at a customer's location.
Holding master keys and security codes creates exposure if information is lost or a dishonest employee enables a break-in.
A miswired keypad, card reader, or electronic lock can fail to secure a building or improperly deny entry, prompting liability claims.
A service-van break-in can take picks, key machines, programmers and lock stock along with customer access information. Vehicle damage, equipment loss and compromised credentials involve different interests.
Recommending or specifying the wrong security hardware can lead to allegations of negligence if a customer suffers a loss.
Records of access credentials, codes, and customer security details can be exposed if systems or files are compromised.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: opening a jammed commercial safe damages its door mechanism. Preserve authorized scope and pre-existing condition records and distinguish the serviced mechanism from surrounding harm. Actual work-property/custody terms govern; a repair demand alone does not establish GL coverage.
Hypothetical: master keys are lost and a later burglary occurs. Preserve access, loss/notification and incident records and investigate cause; that sequence does not prove employee theft or causation. Review key/rekey, client-theft and negligence terms separately, not as interchangeable crime/liability protection.
Hypothetical: key machines and tools are stolen from a van. Check insured items/values, theft/security/location terms and deductible separately from van damage and stolen credentials or customer stock. Auto physical damage is not blanket contents protection.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Review actual employee/client-property theft and covered people, proof and reporting terms. A lost key, rekey demand or later break-in does not by itself establish employee dishonesty or insured client theft.
Identify the actual serviced mechanism/door and separate surrounding harm and review work-property/custody exclusions or extensions. Customer ownership or an authorized opening alone does not establish payment to repair the item being worked on.
Specialized tools and machines are commonly scheduled on inland marine, which may cover them in the van and at customer sites, subject to listed limits and policy terms.
If you store access credentials, codes, or customer security records, a breach could expose that data. Cyber coverage may help with response costs, depending on the specific policy.
Separate reprogramming/replacement and a security-performance promise from actual resulting loss or defined negligent advice/services. Review declared electronic/security operations, work-property, professional, and completed-work terms; an ordinary BOP is not proof all are included.
A BOP can bundle liability and property, but crime, inland marine, and auto are often added given key handling and the mobile model. The right mix is subject to underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.