

Rig damaged on location or moving
Derricks, drawworks and mud systems face fire, collapse and handling losses.
Try a different word, or check the spelling.
Your rig travels as components before it becomes a working installation on the next pad. Equipment protection should follow dismantling, rigging and transit without assuming truck liability or ordinary site cover insures the whole move.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
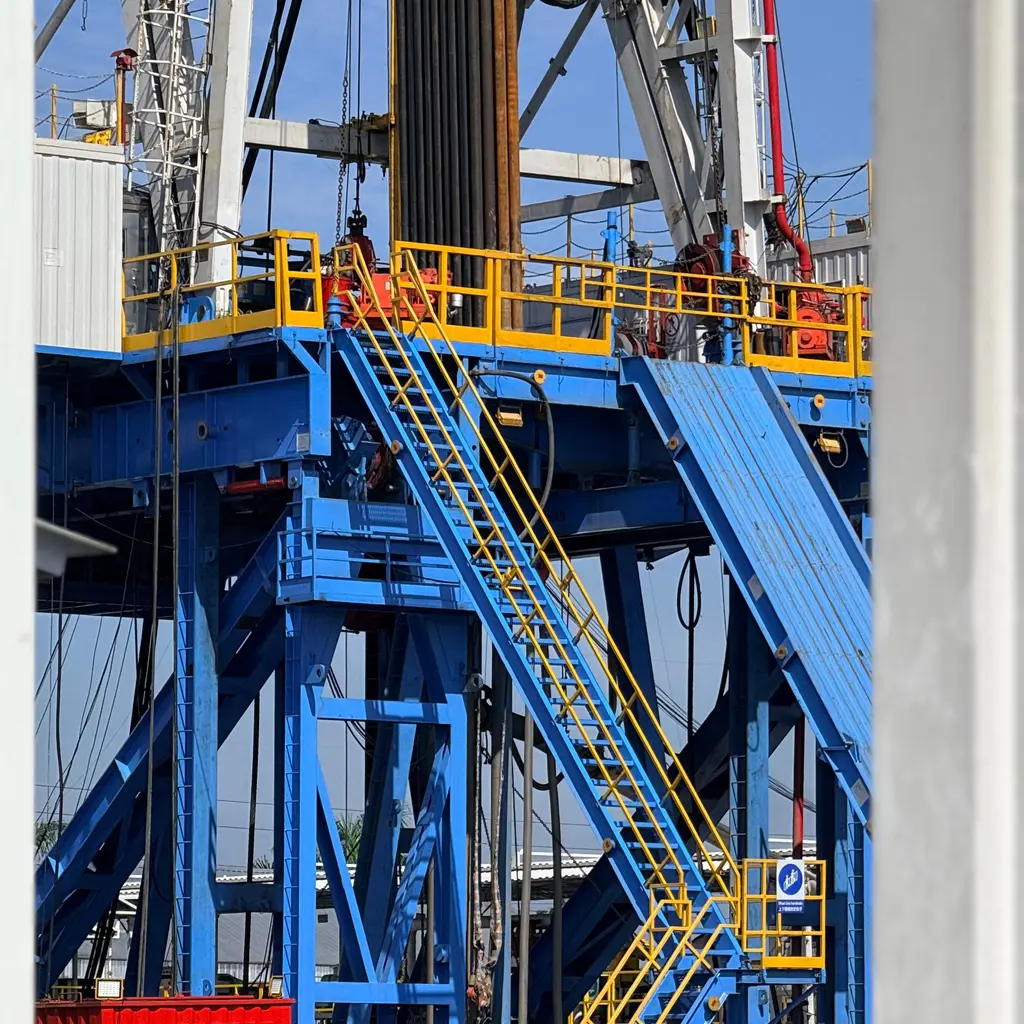
You are a drilling contractor that moves rigs between pads, drills wells, and dismantles equipment for future use. A rollover during transport or a fire on-site can stop your operations and damage your specialized mobile equipment.
The Southern Agency can review your rig moves and drilling responsibilities to help select appropriate insurance. For example, we can help you coordinate mobile equipment protection with crew and road-use liabilities.
Derricks, drawworks and mud systems face fire, collapse and handling losses.
A blowout can create control, property, and pollution expenses that ordinary equipment cover does not combine.
Containment failures can contaminate a pad and surrounding land.
Rotating machinery, heights, and trucking expose workers and the public to severe injuries.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A fire damages the rig during drilling and work stops. Scheduled rig protection may address included physical damage where the phase, equipment and cause are accepted. Ownership, valuation and restrictions matter; lost daily-rate income needs its own applicable interruption terms.
A rig-haul truck overturns, damaging components and another road user's property. Accepted auto terms may address covered road liability and selected truck damage. Transported rig components need suitable equipment or cargo terms for the actual move, not an assumption that the truck's limit insures its load.
Drilling mud escapes damaged containment and contaminates surrounding soil. Contractor pollution may address covered cleanup or third-party claims where the operation, material and event are included. Follow reporting and response terms; repairing containment or controlling a well is not automatically the same insured expense.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Use suitable scheduled rig protection that includes declared locations, rigging, and movement, with ownership and replacement values confirmed.
No automatic inclusion should be assumed. Dedicated well-control arrangements and assigned contract duties need specialist assessment.
Rig moves expose road users as well as the truck. Equipment being hauled is a separate insured interest.
They can request protection and allocate duties; the insurer must independently accept those interests and terms.
Potentially. External damage, qualifying internal failure, wear, and downhole losses can have different treatment.
Rig values, drilling scope, moves, crews, controls, and prior losses inform underwriting. No standard cost is implied.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.