

Original fabric
Fire, water or storm damage can harm historic materials whose repair needs specialist work.
Try a different word, or check the spelling.
Repairing your historic fabric may call for specialist work rather than ordinary replacement materials. Structural restoration values need consideration separately from period furniture and archives, including during a preservation project.
Bring conservation estimates, collection inventories and upcoming project scopes to a review of the house as it is actually used.
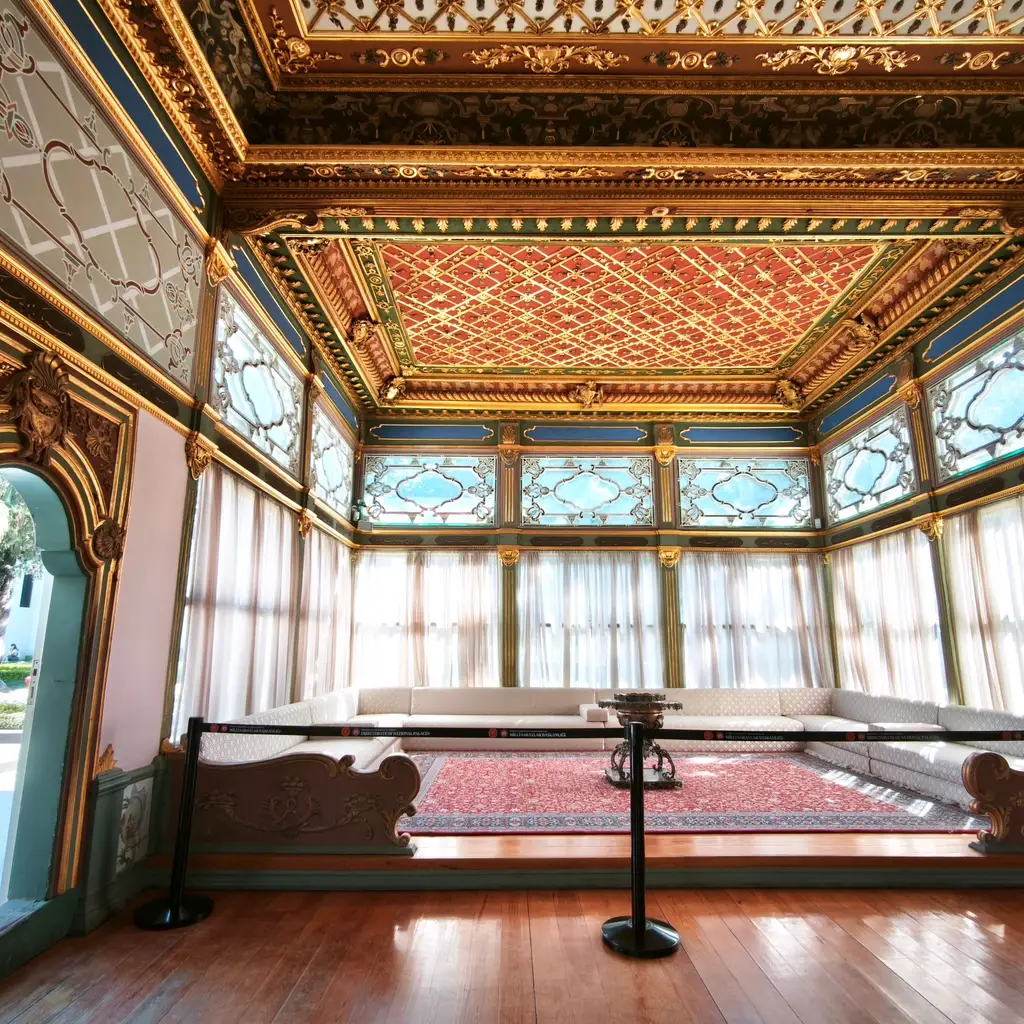
You open period rooms to visitors while preserving a house whose original woodwork, plaster and fittings are part of its historical value. Repairing fire or water damage may call for conservation skills and materials that ordinary reconstruction figures do not capture.
The Southern Agency can review the building's restoration values with you alongside furnishings, loans and planned preservation work. We can compare those property interests with visitor liability and your staff or docent arrangements, without treating an insurance payment as a way to replace lost historical significance.
Fire, water or storm damage can harm historic materials whose repair needs specialist work.
Wiring and heating in an older building can create property and equipment exposures.
Steps, low thresholds, and narrow tour routes can lead to falls.
Period furniture and archives may be damaged by handling, theft or climate conditions.
Contractors on preservation projects and guests at events introduce different duties.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose an electrical fire damages original paneling and later additions in the same room. Property terms determine the insured repair basis for each, including any specialist restoration allowance and limits. A building appraisal does not itself promise period-matched reconstruction or compensate for lost historical significance.
Suppose a guest falls on an original staircase and alleges inadequate lighting during a guided tour. General liability may address a covered injury claim, based on the actual conditions and your duties. The staircase's protected or historic character does not settle responsibility for visitor access.
Suppose rain enters through a roof opening during preservation work and damages a furnished room below. Compare the project policy's treatment of the existing structure and rain entry with the building and collection forms. Contractor responsibility, damage to completed work and the period furnishings are separate questions; builders risk is not automatically all of them.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
The insured value should be compared with the cost of preserving historic fabric and any applicable valuation clause.
Premises liability may address an injury on a tour, according to the condition and facts.
Builders risk can apply during covered work; the policy period and phase of restoration matter.
Period collections can be insured separately, with stated locations, and a supportable valuation basis.
Weddings or lectures add vendor, crowd, and possibly alcohol exposures if actually offered.
D&O may respond to insured board-governance allegations apart from a building loss.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.