

Foodborne illness from held food
Hot and cold buffet items held for long periods and handled by many guests raise time-and-temperature and cross-contamination risk.
Try a different word, or check the spelling.
A hot-well repair and the prepared food it can no longer hold are different costs for your restaurant. Breakdown and stock terms should be understood alongside liability for meals already served.
The Southern Agency can help you assess your buffet restaurant’s liability and equipment protection.
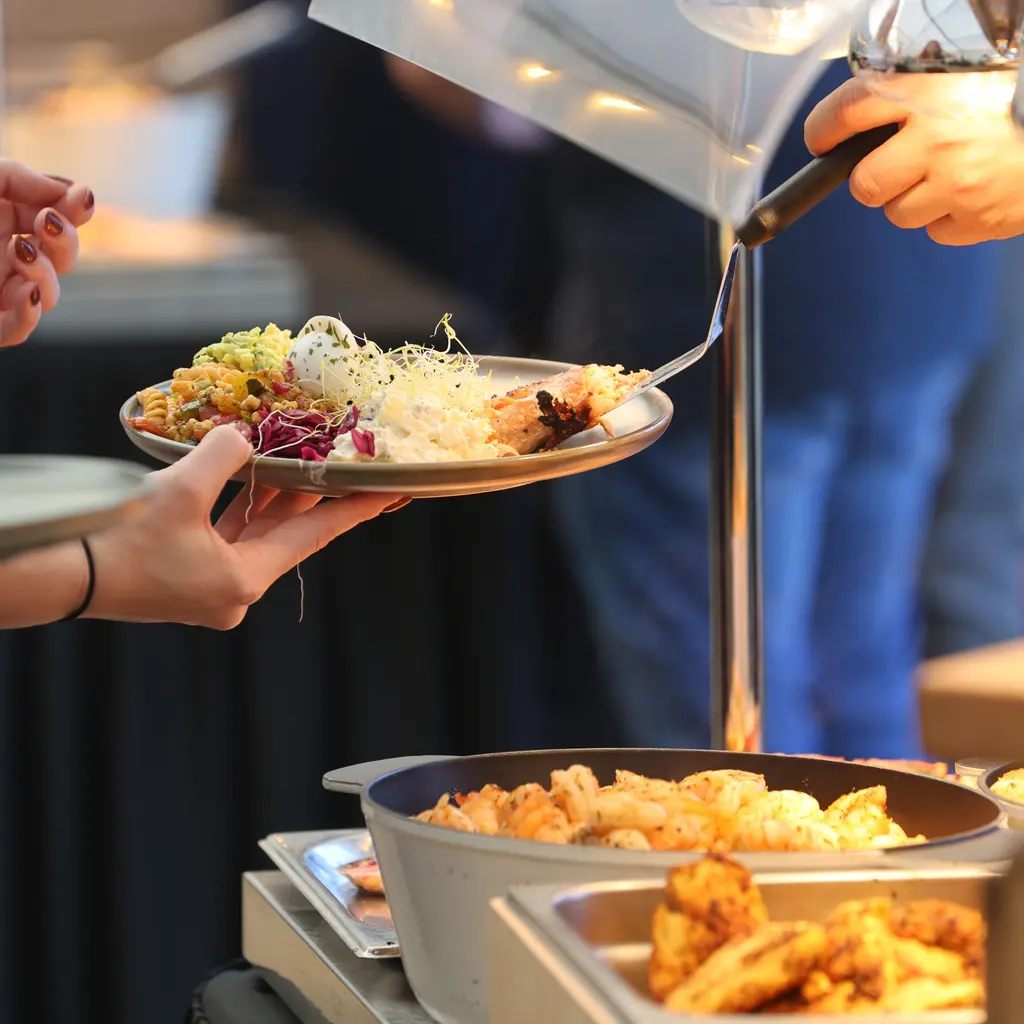
Your restaurant serves meals via self-serve buffet stations, requiring constant temperature monitoring. A spill in the dining area or an allegation of foodborne illness could lead to significant claims against your business.
The Southern Agency can help you review your serving procedures and kitchen maintenance to select appropriate insurance. For example, we can discuss how your equipment breakdown coverage might apply to your hot wells and refrigeration.
Hot and cold buffet items held for long periods and handled by many guests raise time-and-temperature and cross-contamination risk.
Spilled food, crowded stations, and high foot traffic around self-serve lines create frequent slip-and-fall exposure for guests.
Continuous cooking on ranges and fryers, plus grease in hoods and ducts, creates significant kitchen fire exposure.
Failure of refrigeration, hot wells, or cooking equipment can disrupt service and spoil large volumes of prepared food.
High occupancy and large dining rooms increase exposure to crowding, evacuation, and guest property concerns.
Kitchen and line staff face burns, cuts, and repetitive lifting while cooking and restocking buffet stations all day.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Several guests report illness after a busy service and a claim follows. General liability with food-related coverage may respond to defense and damages, depending on policy terms and the facts established. Compare covered food-related harm with actual causation/exclusions; voluntary food disposal or closure is not automatically insured.
A guest slips on dropped food near a serving station and is injured. General liability coverage may help with medical and liability costs, subject to the specific policy and conditions. Review spill inspection/cleanup facts and premises terms; buffet status alone does not establish fault.
A walk-in cooler fails overnight and prepared inventory spoils. Equipment breakdown and spoilage coverage may respond, depending on policy terms and the endorsements in place. Check covered equipment/utility cause and included spoilage limits; ordinary holding-time discard differs.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Holding times, temperatures, and shared utensils affect contamination risk; a buffet format by itself does not establish a higher illness rate. General liability with food-related terms may respond to claims, subject to the policy.
General liability commonly responds to guest slip-and-fall injuries around serving stations. Coverage depends on policy terms, exclusions, and the facts of the incident.
If any alcohol is served, liquor liability is commonly needed to address claims tied to intoxicated guests. Coverage availability depends on underwriting and operations.
Equipment breakdown with spoilage endorsements may respond when refrigeration fails and held food is lost. Coverage depends on the specific policy, endorsements, and exclusions.
Continuous cooking and grease in hoods raise fire exposure, so insurers review suppression and cleaning. Strong maintenance may help with terms, depending on underwriting.
Business income coverage may respond when a covered loss closes the restaurant, helping with lost revenue. Coverage depends on the specific policy and exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.