

Salmonella and pathogen contamination
Raw poultry inherently carries pathogens, so a control failure can cause illness, recalls, and regulatory action across many accounts.
Try a different word, or check the spelling.
Your cutting crew repeats precise work in cold, wet conditions throughout a shift. Employee-injury protection needs to reflect those duties, separately from repairing the line or addressing poultry-stock and product claims.
The Southern Agency can help you evaluate your poultry processing risks, from pathogen control to ammonia-refrigeration safety.
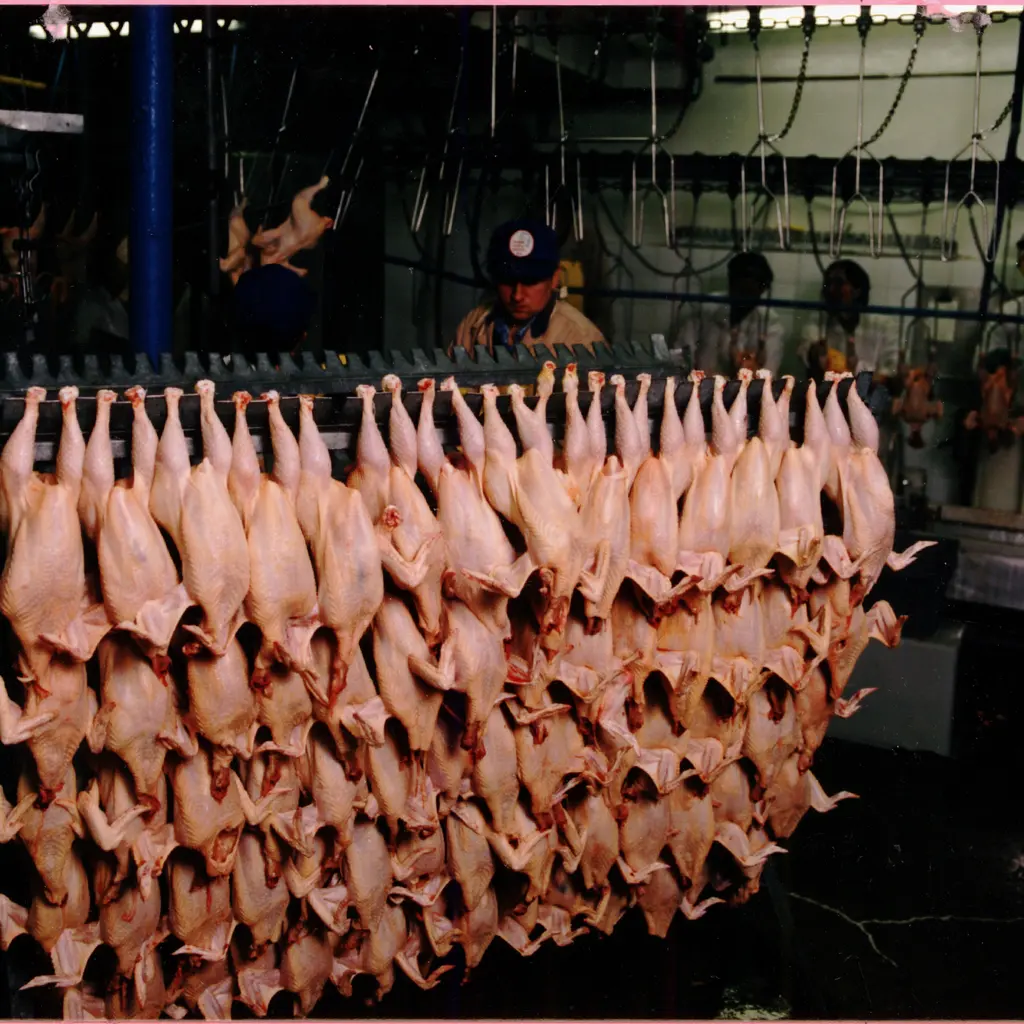
Your plant processes poultry, involving high-speed cutting lines and large-scale industrial refrigeration. A pathogen-related recall or an ammonia release from your cooling system can cause significant harm to your staff, neighbors, and business reputation.
The Southern Agency can review your pathogen-control and industrial-refrigeration risks to help you select insurance that covers your specific operational hazards. We can discuss how your policy might protect your high-value poultry stock and help address the liability associated with your processing plant.
Raw poultry inherently carries pathogens, so a control failure can cause illness, recalls, and regulatory action across many accounts.
Fast deboning and cutting lines create laceration and repetitive-motion injury exposure.
Large ammonia systems carry toxic-release and explosion risk affecting workers, neighbors, and the environment if a leak occurs.
High-value perishable poultry can spoil rapidly when chillers or cold storage fail or power is lost.
Failure of chillers, evisceration, or cutting equipment can stop a federally inspected line and idle perishable product.
Processing generates high-strength wastewater and byproducts that create pollution and discharge exposure for the plant.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A poultry lot is linked to salmonella illnesses and recalled from retailers. Product liability coverage may respond to resulting claims, depending on policy terms, endorsements, and the facts of the loss. Separate covered consumer harm from eligible recall/withdrawal expenses; positive testing does not establish every cost.
A worker suffers a serious cut on a fast deboning line. Workers' compensation may respond to medical care and lost wages, subject to policy terms and applicable state requirements. Review employer/worker status, state arrangements, and work-related benefit terms.
An ammonia leak forces evacuation and cleanup. Environmental liability coverage may respond to cleanup and third-party claims, depending on the specific policy and exclusions. Check covered release/location, cleanup/reporting, and employment exclusions; worker benefits, fines, and routine compliance differ.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Raw poultry inherently carries pathogens, so contamination can cause illness claims and recalls. Product liability may respond, depending on policy terms and underwriting.
Cutting and repetitive deboning create injury exposure. Review payroll/classes, employer arrangements, safety, and loss history with the insurer.
Ammonia introduces toxic-release and explosion exposure that underwriters review closely. Environmental and property coverages may respond to a release, depending on operations and policy terms.
Equipment breakdown and property coverage may respond to repairs and covered spoilage when a covered cause idles refrigeration, subject to policy terms and exclusions.
Poultry processing generates high-strength wastewater and byproducts, so environmental liability may help with related pollution claims, depending on operations and policy terms.
Use actual bird/component lots, treatment and distribution records. Products liability concerns covered harm to others, not automatically withdrawal. Recall/contamination cover needs an eligible event, insured product and purchased expenses; quality rejection, refunds, rework and routine spoilage are not automatic cover.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.