

Resident falls
Older residents with mobility limitations are prone to falls, creating potential care or premises liability allegations.
Try a different word, or check the spelling.
Your residents may need help with a transfer, a medication routine, or finding their way safely through the day. Care and supervision protection needs to fit the support you provide, without assuming premises liability includes neglect or abuse allegations.
The Southern Agency can help you coordinate resident-care, property, and liability protections for your assisted-living community.
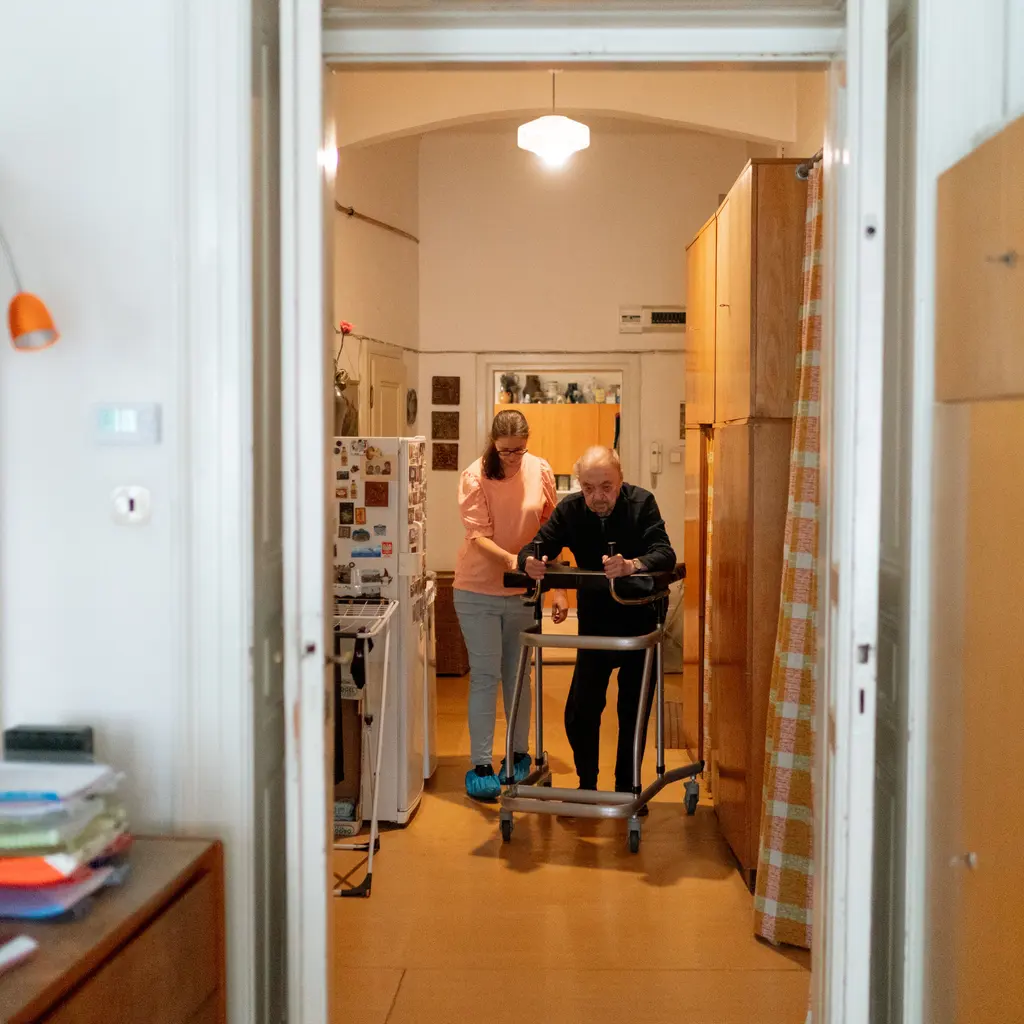
You provide a home and daily support for older adults who depend on your staff. Help with transfers, medication routines and supervision can lead to care-related claims if a resident is injured. Your responsibilities vary with the support you provide and any outside clinicians involved.
The Southern Agency can help you compare your services and resident needs with professional and premises liability coverage. We can also review abuse-related terms and the property, relocation and staff-injury questions that affect continuity of care.
Older residents with mobility limitations are prone to falls, creating potential care or premises liability allegations.
Assisting residents with medications creates exposure if doses are missed, duplicated, or given incorrectly.
Residents with cognitive decline may wander or leave unsupervised, exposing the community to supervision and negligence claims.
Resident-care settings face distinct abuse, molestation, and neglect exposure requiring dedicated coverage and protocols.
Aides assisting residents with transfers and personal care face strain and musculoskeletal workers' compensation claims.
Fire, storm, or water damage to residential buildings and common areas can disrupt care and damage resident property.
Resident health and billing records held electronically create privacy exposure; determine actual HIPAA covered-entity or business-associate status.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A resident falls and sustains a fracture, and the family alleges inadequate supervision. Professional liability coverage may respond to defense and indemnity, depending on policy terms and the facts. Assess care versus premises facts and insured entity; a resident fall alone does not establish negligence or cover.
A resident receives an incorrect medication dose. Professional liability coverage may respond to resulting claims, subject to the specific policy, endorsements, and exclusions. Match the actual assistance/administration duty and authorized provider with insured services and reporting terms.
A family alleges a resident received inadequate care. Coverage addressing professional liability and abuse-related claims may respond to defense costs, depending on policy terms and exclusions. Neglect and abuse definitions can differ; inspect dedicated terms, exclusions, and limits instead of assuming both sections respond.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
These communities commonly carry professional liability, general liability, property, workers' compensation, cyber, and abuse-related coverage. The right mix depends on care level and residents, subject to underwriting.
Professional liability may respond to claims tied to falls and supervision, depending on resident acuity, facility protocols, underwriting, and policy terms.
Resident-care settings carry distinct abuse exposure. Dedicated coverage may help respond to related claims, depending on the specific policy and exclusions.
Professional liability may respond to claims arising from medication-assistance errors, depending on the specific policy, endorsements, and the facts of the claim.
Property coverage may extend to certain community property, and resident-belongings terms vary. Coverage depends on the specific policy and endorsements.
Communities hold resident health and payment records. Cyber coverage may help with breach response and liability if systems are compromised, depending on the specific policy.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.