

Crowd circulation
Seating, aisles, and concentrated arrivals can affect injury severity.
Try a different word, or check the spelling.
Your renter can set the program while you retain premises and setup duties of your own. Venue liability needs to define who handles aisles, seating, volunteers and alcohol rather than rely on the renter's policy alone.
Bring the permitted event range, peak layouts and booking terms, including who sets up, serves and cleans.
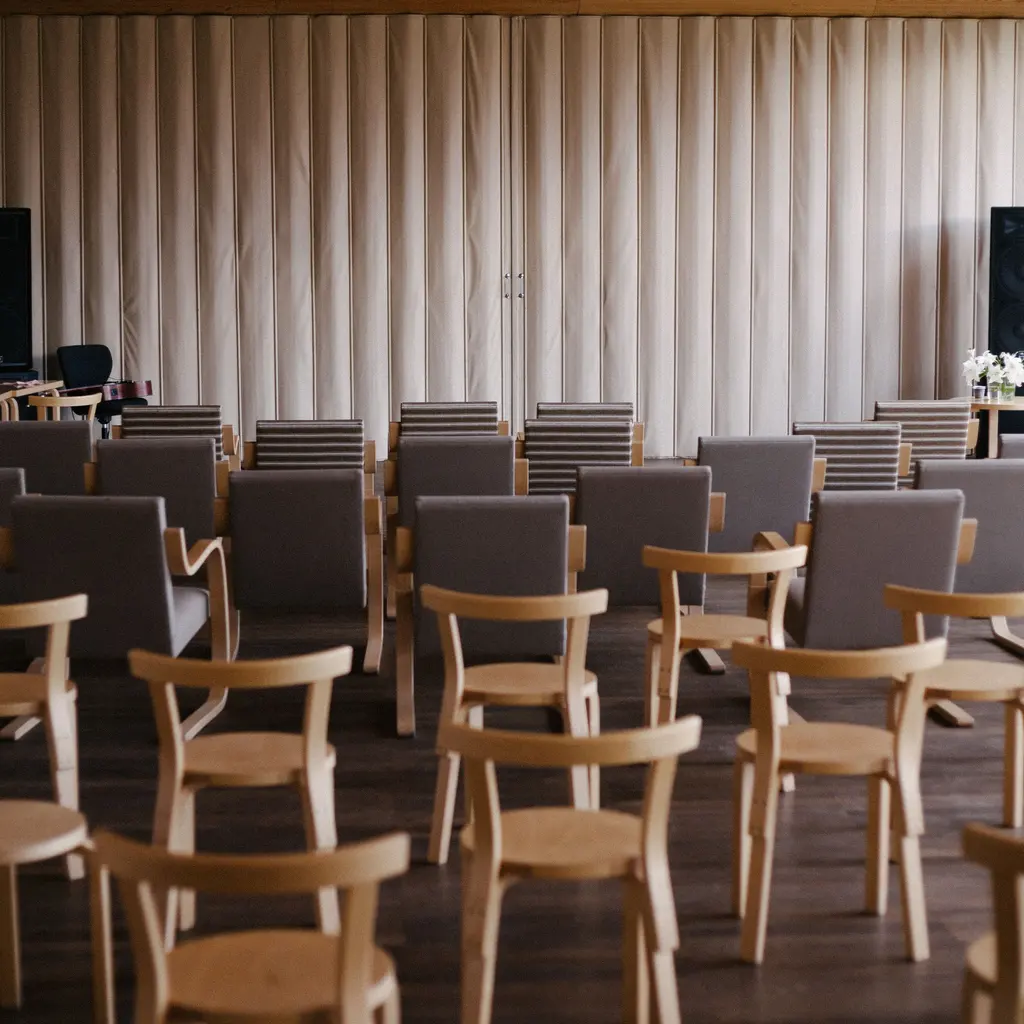
You host gatherings like meetings or services, often arranged by outside groups. Changing layouts or events run by others can create liability exposure for your hall.
The Southern Agency can review your building and range of permitted events to help you select appropriate insurance. For example, we can help explain how your premises liability functions alongside insurance provided by your renters.
Seating, aisles, and concentrated arrivals can affect injury severity.
Renter activities may expose the hall to claims alongside organizers.
Folding chairs, stages, and spills can create trip hazards.
Roof, electrical or water damage can interrupt scheduled bookings.
Setup workers, volunteers, and occasional alcohol have different insurance questions.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose an attendee trips over a folding chair during a meeting. Review who selected and placed the seating, the alleged condition and the hall's accepted activities. General liability may address a covered claim, but the fall alone does not establish the hall's or renter's fault.
Suppose a guest alleges injury during a renter-run program and names the hall as well as the organizer. Compare actual program and premises duties, insured parties and any applicable additional-insured endorsement. A certificate or booking agreement does not itself transfer every claim.
Suppose a storm damages the roof and bookings stop during repairs. Property and purchased income terms may address covered damage and eligible earnings loss. Check the cause, deductible and restoration period; refunds, lost deposits and every canceled event cost are not automatically included.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Renter cover does not necessarily include the hall or its own negligence; compare insured parties and duties.
Certificates help document a renter's insurance, but endorsements and exclusions determine actual protection.
Occasional service still needs review of who supplies, sells, and controls the alcohol.
Peak occupancy and layout affect the exposure; no universal limit follows from the hall label.
Volunteer injuries may not receive employee benefits. Describe their work and applicable arrangements.
An older structure needs supportable values and condition information, including roof and electrical systems.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.