

Motor failure damaging customer equipment
A winding fault or bearing failure can cause the driven machine to fail or overheat, leading to product-liability and property-damage claims.
Try a different word, or check the spelling.
Your motor is only one part of the equipment it drives. Product protection should separate damage to that surrounding machine from replacing your motor, warranty chargebacks, and a recall demand.
The Southern Agency can help you evaluate your motor manufacturing risks, from shop floor hazards to long-tail product liability.
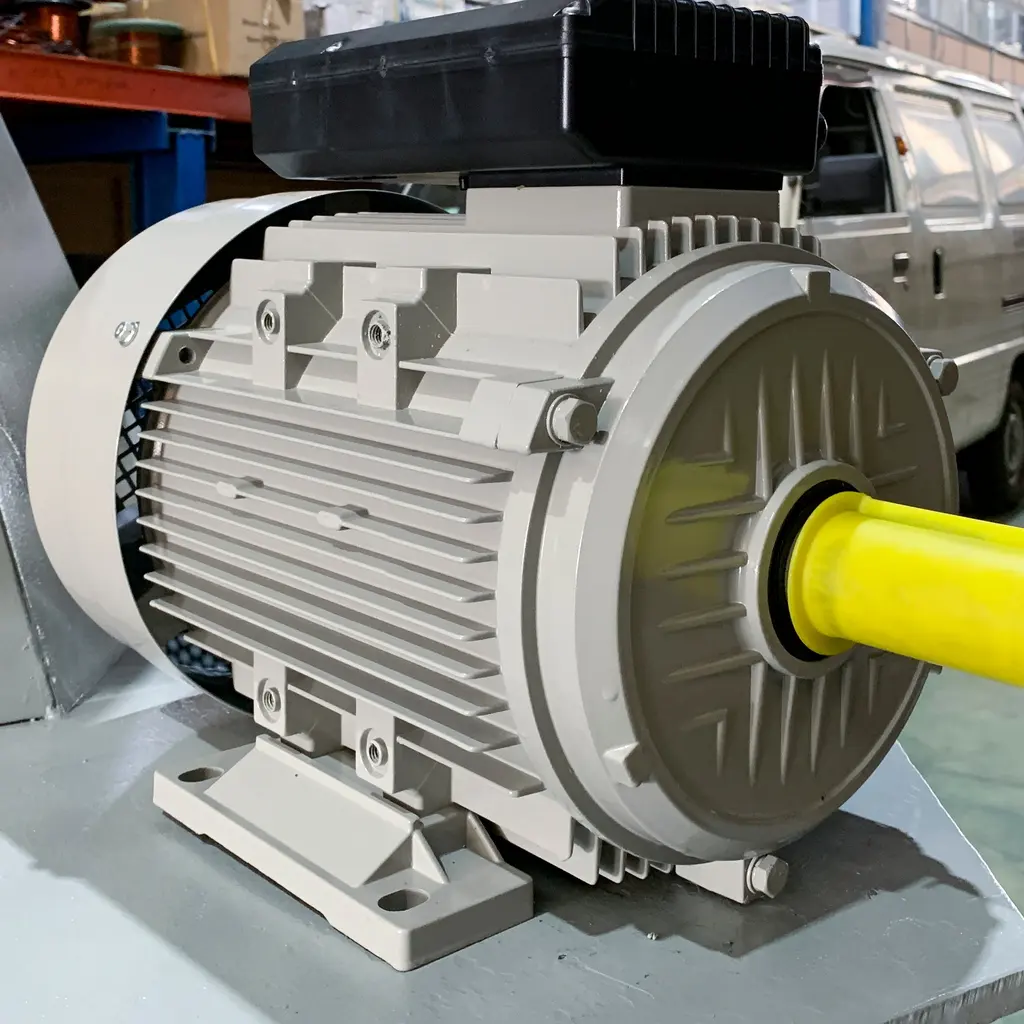
You manufacture motors for industrial and HVAC use, creating long-tail product risk if a winding fails or a motor overheats in service. Your shop involves varnish processes and metalworking that create fire and machinery injury risks, which could interrupt your ability to meet customer orders.
The Southern Agency can review your winding and assembly processes to help you select appropriate insurance. For example, we can discuss how your product liability coverage applies to your motors once they are integrated into customer machines and how inland marine might help during transit.
A winding fault or bearing failure can cause the driven machine to fail or overheat, leading to product-liability and property-damage claims.
An insulation or varnish defect can short a motor in service, potentially igniting or damaging equipment at the customer's site.
CNC machining, lamination stamping, and balancing create caught-in and struck-by hazards for production workers.
Dip-and-bake varnish lines and solvent cleaning introduce ignition and flammable-vapor risk on the production floor.
Winding machines, ovens, and test stands are production-critical, and a breakdown can idle the line and scrap in-process units.
Motors embedded in customer machinery can trigger warranty chargebacks or recall demands if a defect pattern emerges.
Finished motors shipped to integrators can be damaged in transit or while staged at off-site locations.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A buyer alleges a defective winding caused a motor to fail and damage their production equipment. Product liability may respond to defense and damages, depending on the policy and claim facts. Check the motor, load and design duties included and actual damage to other equipment separately from the motor itself, impaired-property provisions, and contract or warranty terms.
A fire starts at the dip-and-bake varnish line and damages part of the plant. Review the fire cause and any covered internal failure separately under property and equipment breakdown terms. Identify equipment and stock by owner, valuation, and purchased income protection. Varnish-quality problems or stalled motor orders alone do not insure repair or lost production.
A shipment of finished motors is damaged en route to an integrator. Inland marine may respond, depending on the policy, endorsements, and exclusions. Check ownership, the packing, loading or carrier cause, valuation, and limits. Payment need not equal the sales price or include every obligation for damage during processing.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Product liability is central because motors fail inside customer equipment. Property and equipment breakdown also matter for the plant. The right mix depends on operations and underwriting.
Identify the motor, load and design duties and any injury or resulting damage to other equipment. Check products included, own-product, impaired-property, professional, and contract terms. Failure alone does not insure motor replacement, driven-machine rework, lost output, warranty, or recall.
Dip-and-bake varnish and solvent use create ignition exposure. Commercial property may respond to resulting fire damage, though suppression and controls affect terms and underwriting.
Often. If you ship finished motors or stage components off-site, inland marine may help cover them in transit or storage, depending on the specific policy and facts.
Equipment breakdown with business income coverage may help with repair costs and lost output when a covered failure stops production, subject to policy terms.
Review the remedy and product separately. Ordinary injury or property-damage liability does not itself include motor warranties, chargebacks, or withdrawal expenses. Any proposed special terms need a product and trigger expressly included, expenses, limits, and exclusions. A warranty or customer request does not prove insurance or an endorsement is available.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.