

Volunteers and guests in the studio
Residents and guests can be hurt by lights, cables, or set pieces while using the studio.
Try a different word, or check the spelling.
Your community producer makes the program, but the station can still receive a demand about what it airs. Media protection should fit that oversight role, alongside shared studio gear, visiting volunteers, and the board's separate management responsibilities.
Review public studio access, equipment ownership and contributor permissions alongside actual staff, volunteer and board roles.
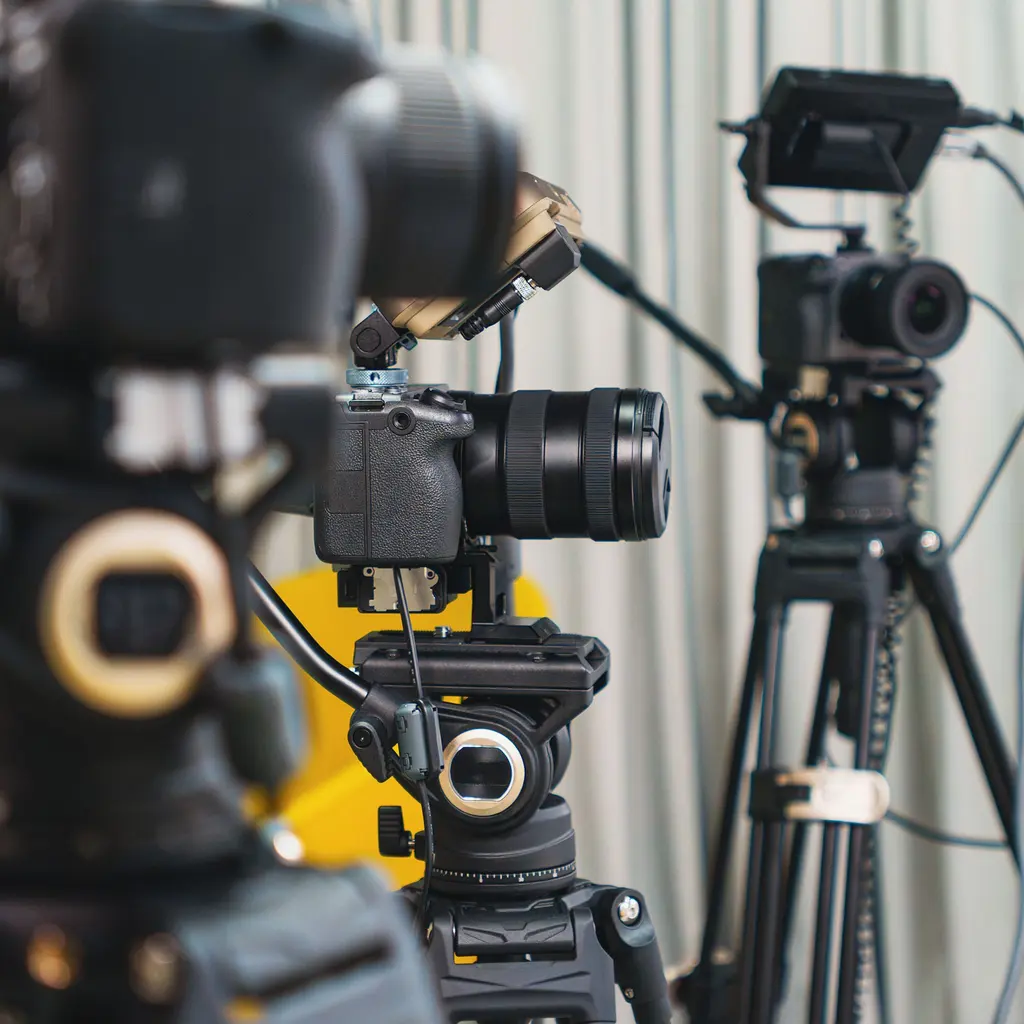
You provide studio space and equipment for community members to produce their own programming. A guest could be injured by your lighting rig, and the station itself could face a claim over content broadcast on air.
The Southern Agency can help you review your facility operations and programming oversight to select appropriate insurance. For example, we can discuss how general liability covers guest injuries in your studio and how professional liability may help with claims regarding community-produced content.
Residents and guests can be hurt by lights, cables, or set pieces while using the studio.
A program made by a community producer can lead to a defamation or privacy claim against the station.
Uncleared music or video in a broadcast can prompt a copyright claim.
Shared cameras, switchers and editing systems can be damaged by fire, accident, or misuse.
Board decisions and employment matters can lead to management claims.
A major studio loss can interrupt programming and municipal or franchise obligations.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A guest on a volunteer-produced talk show makes statements a local business calls defamatory, and the business sues the station. Media-liability coverage may defend a covered claim and may pay eligible damages if liability is established; the program and reporting terms matter.
A volunteer is struck when a poorly secured light falls during a taping. General-liability coverage may defend a covered injury claim; worker status and the facts affect the applicable terms.
An electrical fire damages the control room and forces the station off air. Property coverage may pay for covered physical damage at the listed studio; business-income coverage has its own trigger for lost operations.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Separate an injury to a volunteer from a claim alleging the volunteer injured someone else. Their actual role and applicable injury arrangements affect the first; insured-person definitions and accepted studio or production duties affect the second. A volunteer badge or facility release does not establish either protection.
Yes. A station may face a claim over community programming it airs. Media-liability coverage may defend a covered claim; the content, rights and reporting terms matter.
A board may face claims over management, oversight, or funding decisions. Directors-and-officers coverage may defend a covered claim; it does not cover every disagreement.
Unlicensed music can prompt a copyright claim. Media-liability coverage may defend an eligible claim when the station, program, rights, and policy timing fit.
Property coverage may pay for covered physical damage to the building and listed equipment at the insured location. Ownership, limits, and cause of damage matter.
Funders may request proof of liability coverage or specific terms. Review the request against the actual policy and endorsements rather than assuming it is available.
Prepare facility and equipment values, volunteer and staff counts, programming volume, review practices, funding details, and loss history. An insurer determines whether it will offer terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.