

Advice
A missed hazard or weak recommendation can be challenged.
Try a different word, or check the spelling.
Your advice addresses hazards that could injure people, so an injury exclusion matters to the consulting protection you buy. Audit, training and site-visit terms should fit the agreed scope, alongside travel and personnel-data duties.
Bring actual audit and training engagements, site-access duties, travel arrangements and the client or personnel records you retain.
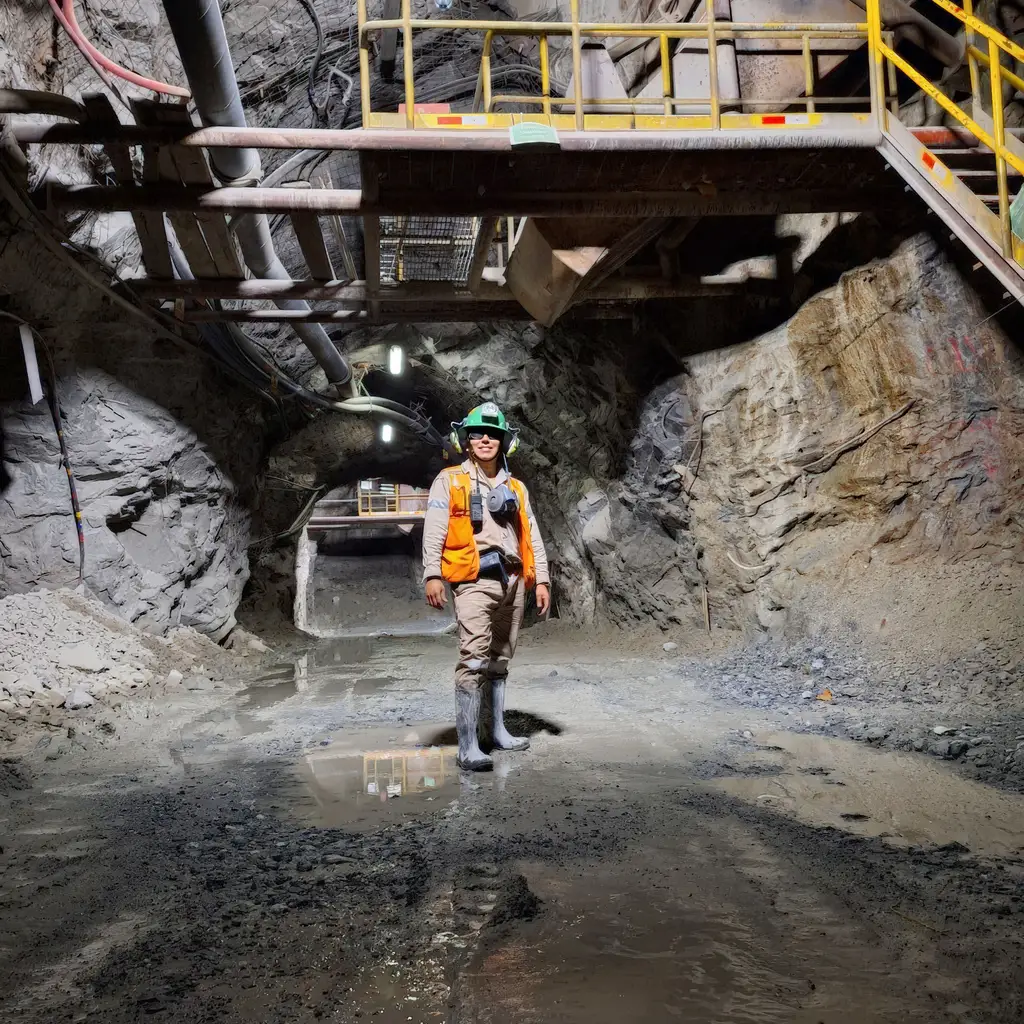
You audit mining sites, recommend safety controls, and train personnel. If an incident occurs, an operator may allege you missed a hazard or provided inadequate advice.
The Southern Agency can review your consulting work and site-visit requirements to help select appropriate insurance. For example, we can examine how professional liability may help defend a covered allegation regarding your advice, while your travel and personnel records create separate insurance interests.
A missed hazard or weak recommendation can be challenged.
Clients may allege instruction did not fit the agreed scope.
Active equipment and uneven ground expose consultants to injury.
Audits and personnel details can be compromised.
Remote driving and broad engagement promises create separate duties.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose a mine operator alleges your audit missed a hazard after a worker is injured. Compare the agreed audit scope, actual advice and allegation with professional-services and bodily-injury wording. Ordinary GL or an E&O label alone does not establish defense of injury-related advice claims or payment of the operator's penalties.
Suppose an intrusion exposes audit findings and personnel details stored for clients. Cyber terms may address an included incident and eligible approved response. Identify the actual data, vendors and notice duties; professional advice liability and contractual confidentiality promises are not interchangeable with every breach benefit.
Suppose a consultant falls during an active-site walkthrough. Injury benefits depend on actual worker status, duties, territory and applicable arrangements. The client's mine policy is not assumed to cover your personnel, and benefits for that injury differ from defending an allegation about your audit.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
The firm's main work product is advice, so professional service and injury-related wording matter.
Visits can create physical third-party claims even for an advisory business.
Confidential safety and personnel records create distinct data responsibilities.
Employee injuries need correct duties and territory; a client site's policy is not assumed to provide benefits.
Compare the actual client's limits and insured-status requests.
Office packaging may fit eligible property and premises interests but does not replace professional cover.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.