

Off-site machines
Equipment can overturn, be stolen, or be submerged.
Try a different word, or check the spelling.
Getting the machine back is part of the rental cycle, but non-return can be treated differently from theft at a job site. Your equipment protection needs those actual handoffs, separately from hauling the unit or defending allegations about servicing and instruction.
Bring unit values, rented-out locations, delivery duties, return inspections and any operator-supplied work for The Southern Agency to review.
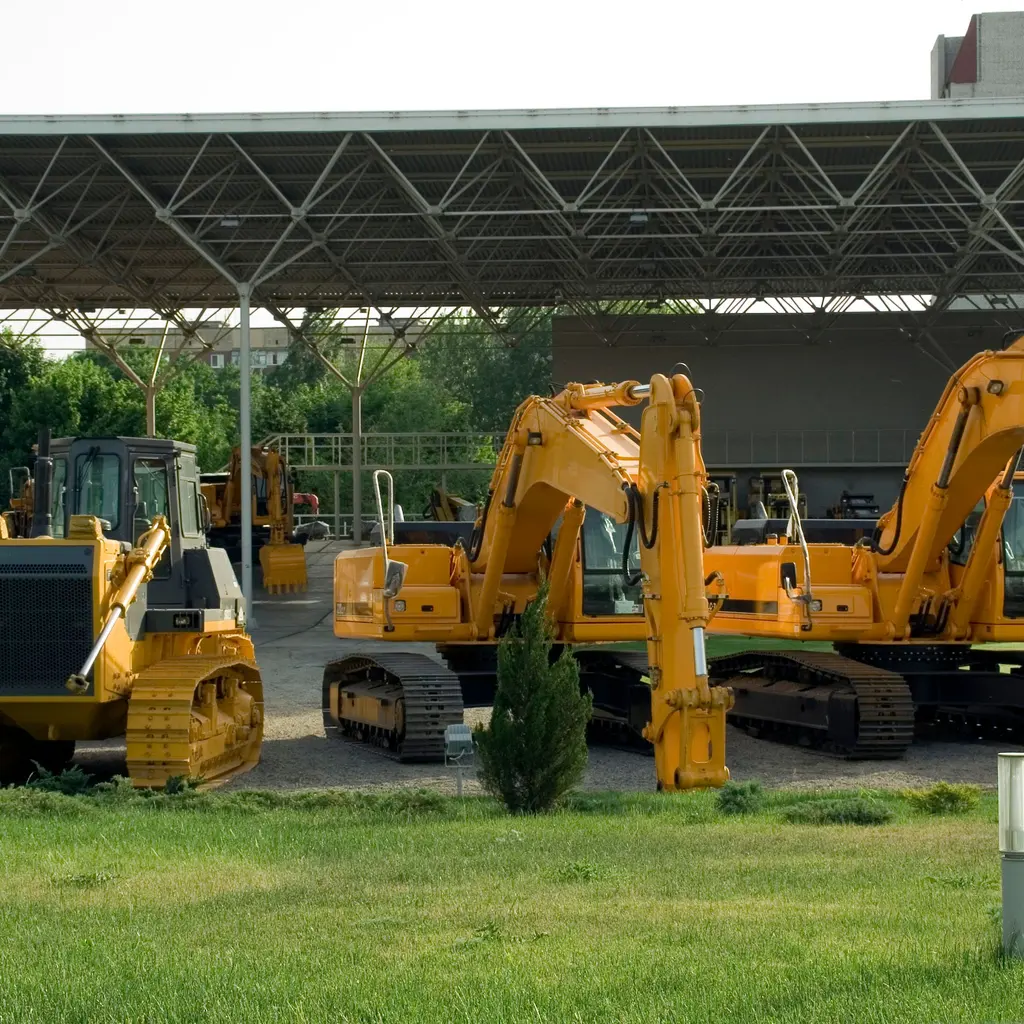
You deliver and maintain machinery like lifts and skid steers for use on customer construction sites. A machine malfunction or injury during operation can lead to claims against your business.
The Southern Agency can review your maintenance and inspection processes to help you select appropriate insurance. We can discuss protection for your machines while they are on job sites and liability coverage for allegations related to the equipment you provide.
Equipment can overturn, be stolen, or be submerged.
Loading and hauling create asset and road exposure.
A later incident may be blamed on servicing or instruction.
Hydraulics, lifting, and moving units threaten staff and visitors.
Waivers and renter insurance may allocate different costs.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A rented lift could overturn at a customer's site. Review rented-out use, accepted perils and location, recovery costs and the machine's valuation. Damage to the lift, injury allegations and a renter's contractual reimbursement are separate interests; the damage waiver does not itself expand the yard's policy.
A skid steer could be damaged while loaded for delivery or during a road collision. Identify the loading responsibility, transit cause and applicable equipment terms. Truck or trailer physical damage does not automatically repair the machine carried, and the hauler's legal liability is a separate question.
Liability may defend a covered allegation; redoing maintenance is not automatically insured.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Rented-out locations and uses need explicit equipment scope.
Responsibility and recovery depend on the agreement and both policies; no automatic payment sequence applies.
Compare requests with available endorsements before agreeing to them.
Truck and trailer liability or damage do not automatically insure the machine carried.
Property should match premises, parts, and equipment allocation.
Review eligible machines and internal-failure exclusions; ordinary wear remains a maintenance issue.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.