

Unit values
One overturn or fire can damage a major asset.
Try a different word, or check the spelling.
Supplying your own crane operator changes the job you accept compared with handing over a bare machine. Rental and lifting liability need that distinction, alongside the unit's value and transport, without assuming every rigging duty or contractual indemnity is insured.
Describe bare versus operated rentals, load and ground duties, highest unit values, transport and repair dependencies for a practical review.
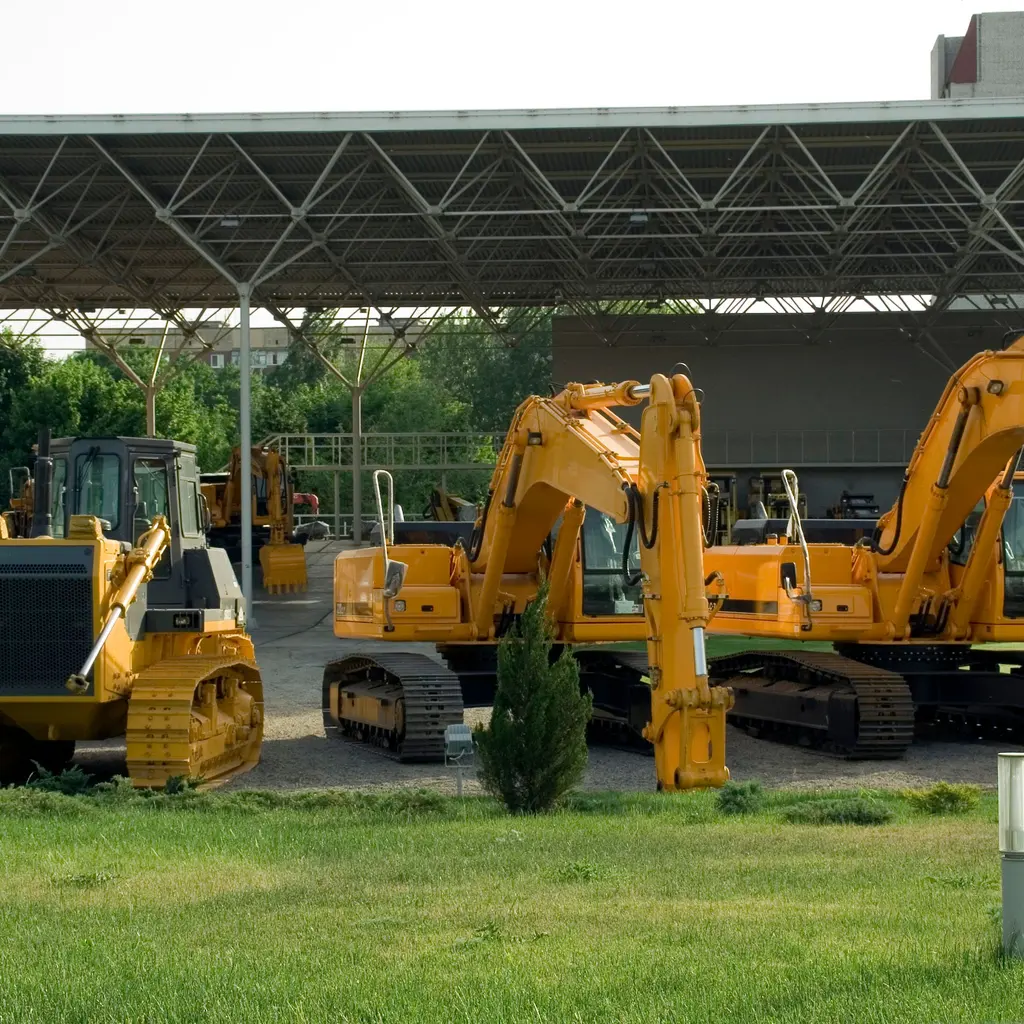
You supply cranes, excavators and other large machines, sometimes with your own operators. A crane incident can involve damage to the machine, nearby property, and people in a single event.
The Southern Agency can review your fleet and service model to help you select appropriate insurance. For example, we can differentiate between bare rentals, where the customer manages the work, and operator-assisted work where your firm maintains control of the machine.
One overturn or fire can damage a major asset.
Supplied operators perform work at customer sites.
Loading and lowboy hauling create damage and roadway concerns.
Complex components create repair and injury risks.
Lift duties and broad indemnities can exceed expectations.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Your supplied crane operator could strike a neighboring building during a lift. Review actual operating, load and rigging duties, accepted activities and exclusions. Repairing the crane, damage to the lifted object and liability to the neighbor need their respective terms; a broad lift indemnity does not establish all three.
An excavator could shift on a lowboy during delivery. Identify who loads, secures and hauls it and review the equipment transit cause, valuation and recovery provisions. The hauling truck's damage policy does not automatically repair the excavator or meet every assumed cargo responsibility.
Eligible machinery and cause determine breakdown treatment; wear is separate.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Rented-out equipment needs accepted sites, perils, and values.
Supplying operators adds operational duties beyond lending the asset.
Hauling vehicle and equipment-in-transit interests need distinct provisions.
Large covered claims may exceed primary limits; excess must accept the same activities.
Mechanical cover depends on eligible machinery and causes, not merely a sudden stoppage.
Accepted duties and applicable compensation rules govern worker benefits.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.