

Users
Powered tools can cut or injure customers.
Try a different word, or check the spelling.
The next customer may receive a tool whose return inspection has not revealed a fault. Your rental-operation and product protection should fit that responsibility, with replacing the tool itself, off-site damage, and non-return reviewed as separate costs.
Describe powered tools, return checks and demonstrations, peak stock away, renter agreements and actual store or shop duties.
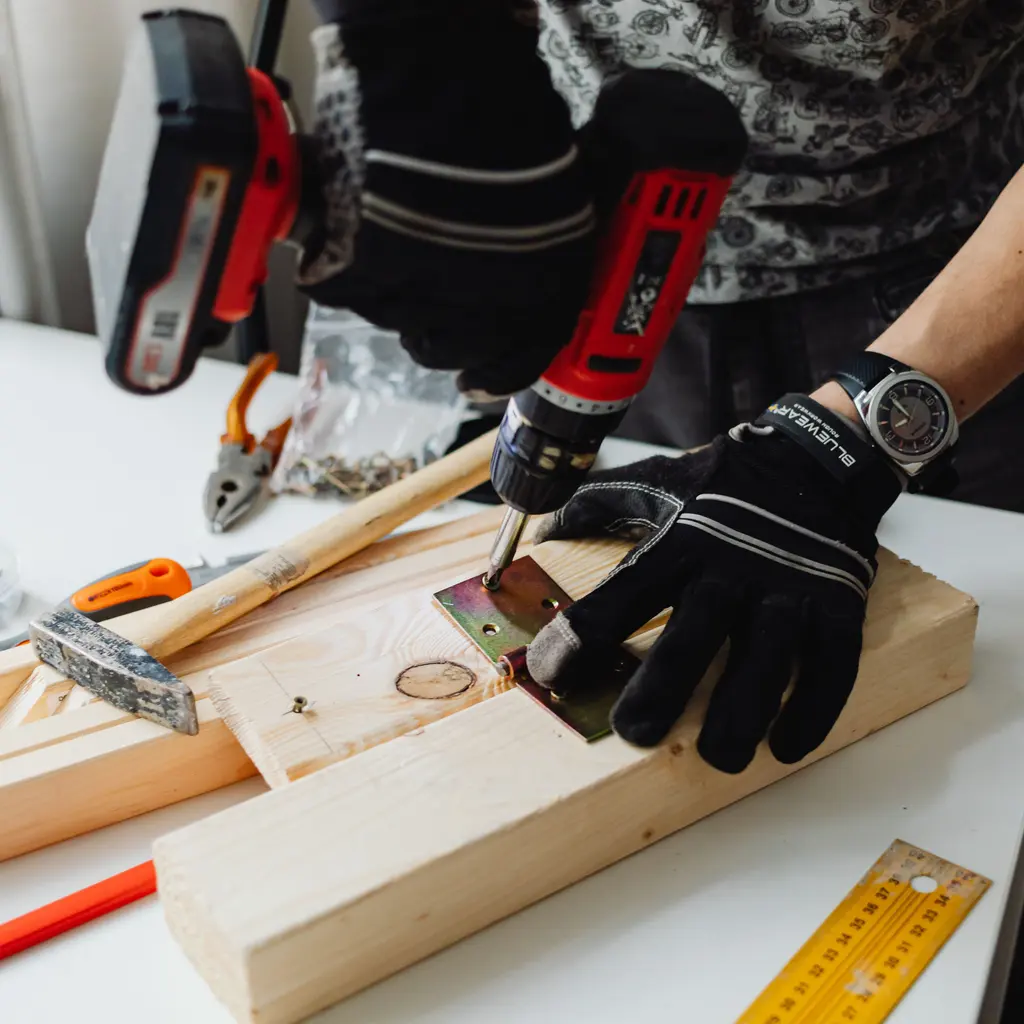
You rent saws, mixers and other portable equipment to customers who may have little experience using them. An injury can lead to an allegation that a tool was unsafe or inadequately inspected before it left your shop.
The Southern Agency can review your inventory and return-inspection processes to help you select appropriate insurance. For example, we can discuss how your product liability coverage responds to equipment claims versus how your inland marine policy protects your tools while they are off-site.
Powered tools can cut or injure customers.
A damaged return can be reissued before a fault is found.
Portable tools can be stolen, damaged, or not returned.
Visitors and loading create premises concerns.
Demonstrations and payments create different responsibilities.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A renter could be injured when a saw kicks back and allege a defective guard or missed return inspection. Review accepted rented-tool operations, maintenance or instruction allegations and product exclusions. The injury does not prove fault; defending a covered claim differs from replacing the saw or promising immunity through a waiver.
Premises facts and liability terms determine review.
Stock values, theft terms, and deductibles govern recovery.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Liability depends on responsibility and the alleged defect; injury alone does not establish fault.
Off-site inventory needs express rental and theft terms, including non-return review.
Premises and stored stock need accurate values and covered causes.
Package eligibility depends on tools, service work, and rental activities.
Counter records and payment processors create cyber questions separate from premises liability.
Accepted duties and applicable compensation rules govern employee injuries.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.