

Service travel
Driving a service van or personal vehicle between calls can lead to a road claim against the business as well as the driver.
Try a different word, or check the spelling.
On a service call, your van, tools, and the appliance you move are different property interests. Mobile-service protection should fit that work, with a scratched cabinet, a later connection claim and redoing the repair considered separately.
The Southern Agency can compare your connections and repair work with completed-operations terms, then review service vehicles and portable tools.
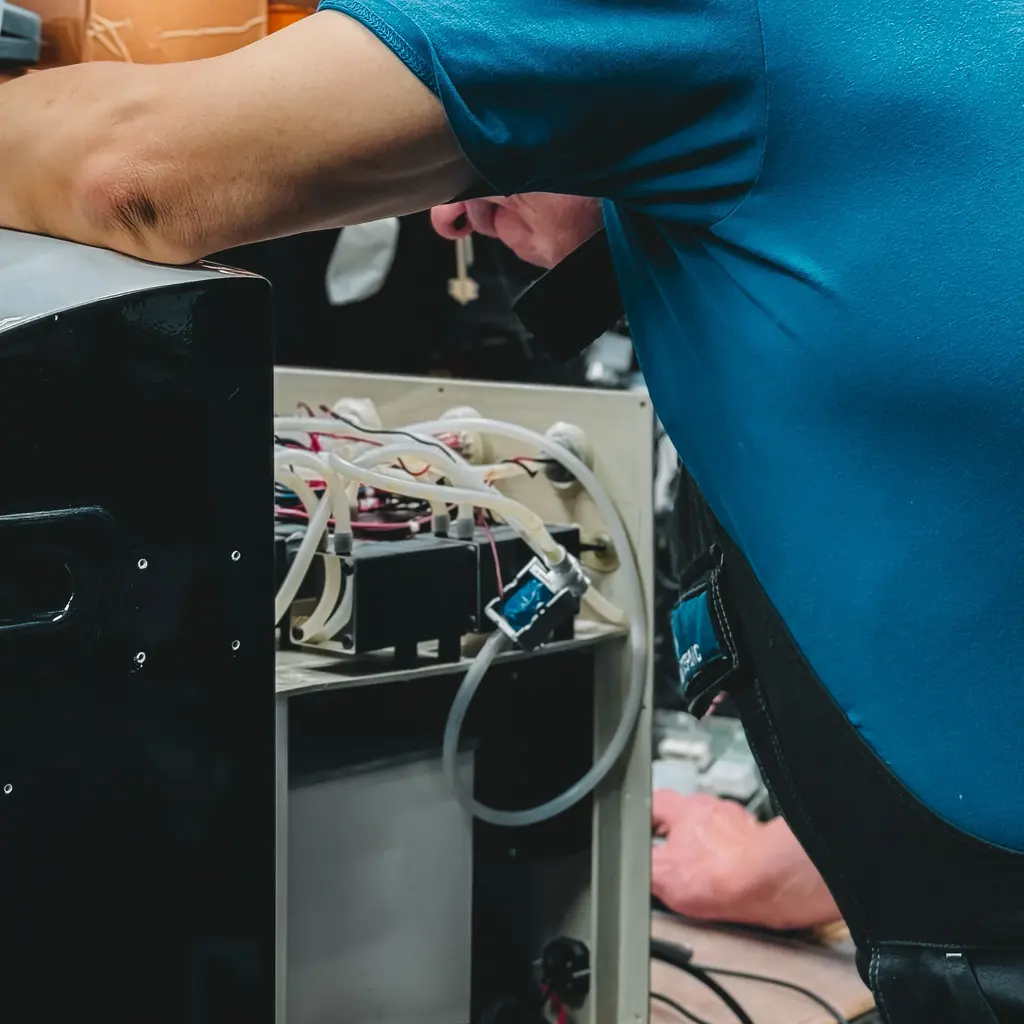
You work around water, gas, and electrical connections in customers' homes. A dishwasher connection that leaks after a visit can cause damage well beyond the appliance being repaired.
The Southern Agency can review your mobile service and shop work to help compare insurance. We can distinguish damage alleged after a completed repair from the cost of redoing your work, then review the tools, parts and vehicles you take to calls.
Driving a service van or personal vehicle between calls can lead to a road claim against the business as well as the driver.
Pulling out a refrigerator or dishwasher can damage surrounding floors and cabinets, or the appliance in your care. Those property interests may have different exclusions.
A water, gas or electrical connection can fail after you leave, causing flooding or fire beyond the repaired appliance. Resulting damage and redoing your own work are different costs.
Tools and replacement parts may be stolen from a van or damaged on a call. Transit, overnight storage and customer-site terms matter as much as shop values.
Moving heavy appliances, working in tight spaces or encountering energized connections can injure technicians. Actual work and employment relationships matter for work-injury benefits.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
After a dishwasher service call, a connection leaks and damages the customer's floor. Accepted completed-operations terms may help with covered defense and resulting damage, subject to faulty-work and handled-property provisions. Fixing the connection or replacing the appliance is a separate cost, not automatically insured because the floor claim qualifies.
A technician rear-ends another car while driving a service van to a call. Accepted auto liability may help with covered third-party injury or damage. Repairing the van needs purchased physical-damage terms; tools damaged inside need their own accepted property protection.
A locked service van is broken into overnight and diagnostic tools are taken. Applicable tool-theft terms may help replace accepted equipment under the written valuation and limits. Compare ownership, inventory proof, storage and security conditions; a locked van or comprehensive vehicle cover does not itself establish a contents payment.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
A collision between calls can involve the driver, business and service vehicle. Describe actual vehicles, drivers and use when comparing liability and purchased repair terms. Tools or parts carried inside and technicians' personal cars are separate interests.
Completed-operations terms may help with covered injury or resulting property damage, such as a leak damaging a floor after a visit. Read faulty-work, handled-property and service exclusions. Returning to redo the connection, honoring a warranty or replacing the appliance is not automatically the same insured loss.
Compare accepted tools and parts, ownership, transit and overnight vehicle-storage terms, theft proof, valuation and limits. Some equipment forms use lists and others broader limits. A vehicle policy, locked door or police report alone does not establish every contents claim.
Actual employers, duties and work states determine the review. Workers compensation may provide medical and qualifying wage benefits for covered work injuries; requirements and owner elections vary. Calling someone a contractor or having them drive their own car does not itself settle status.
Non-owned liability may protect the business for staff driving but does not automatically repair their personal cars.
Vehicles, territory, services, payroll, tools, and losses influence underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.