

Machines after sale or service
An assembly or repair error can allegedly cause injury or damage after a unit leaves. Reworking the unit and paying for resulting injury are different losses.
Try a different word, or check the spelling.
Your service area can hold fueled machines, batteries, and customer equipment with different owners and handling needs. Dealer protection should fit the actual storage, charging and custody arrangements, alongside completed repairs, demonstrations, and any test rides rather than a standard retail label.
Show the actual machinery, repair and assembly work, customer-unit values and outdoor storage, including any transported or demonstrated equipment.
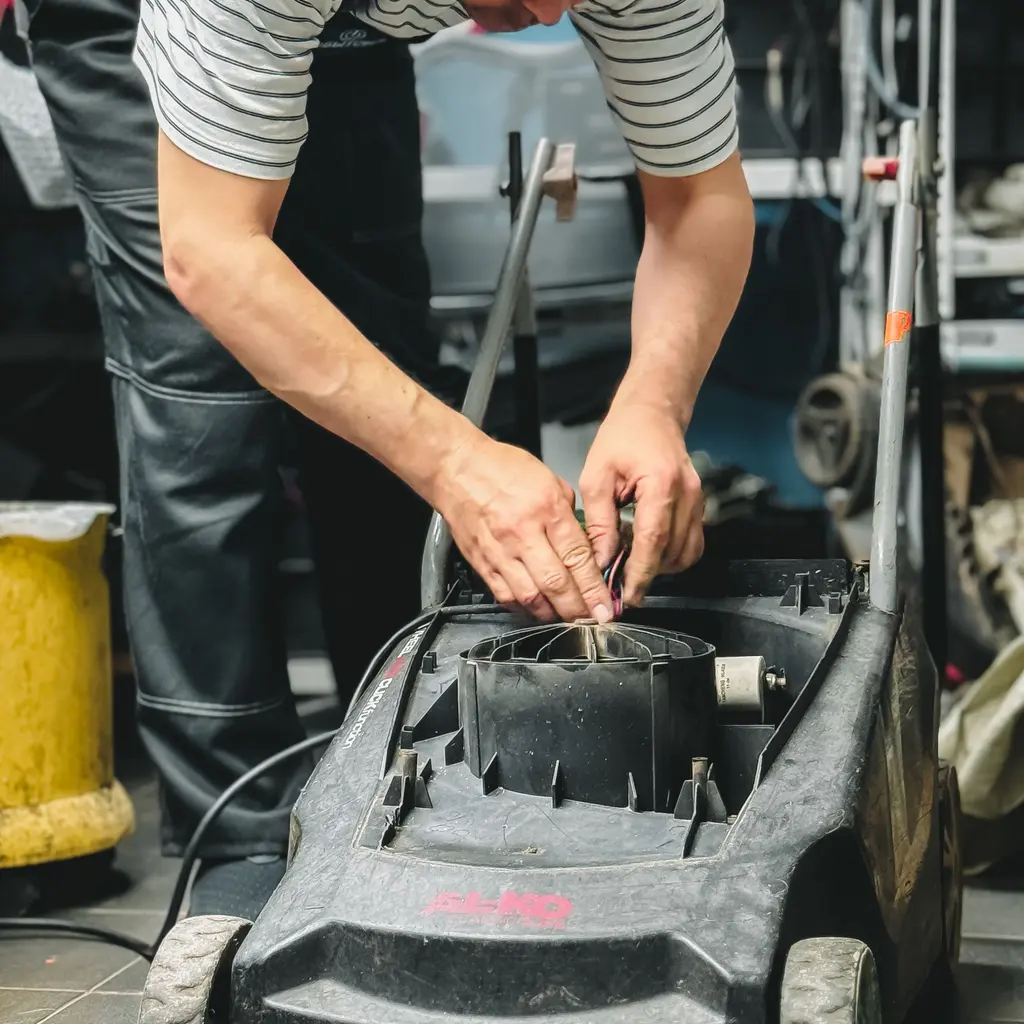
You sell, repair and demonstrate powered machinery like mowers and chainsaws, often assembling units for your customers. A fire in your service area or an accident involving a repaired machine can create unexpected expenses for your business.
The Southern Agency can review your shop, repair operations and demonstrations to help you select appropriate insurance. We can compare actual products/completed-operations terms for alleged resulting harm with property protection for your inventory, tools and customer machines.
An assembly or repair error can allegedly cause injury or damage after a unit leaves. Reworking the unit and paying for resulting injury are different losses.
Test rides can injure participants. Customer machines awaiting service need custody terms that fit storage and repair work.
Fire conditions depend on fuels, batteries, and charging practices. Technicians also face blades, hot engines, and lifting injuries.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A customer might allege that a blade assembly failed after your repair and caused injury. Products/completed-operations terms may help with covered defense and damages if the actual machine and service are accepted. Correcting the assembly or replacing the serviced unit has different own-work, product and custody considerations from resulting injury.
A customer loses control of a demonstration mower. Applicable liability coverage may respond, but the machine classification and demo terms must fit; a waiver does not establish coverage.
A service-area fire could damage owned stock and customer mowers awaiting repair. Compare the covered fire cause, accepted fuel or charging activities, each owner's interest, valuation and limits under actual property/customer-goods terms. Any income or extra-expense benefit needs its qualifying interruption; the value of unfinished repairs is not automatically payable as lost income.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Completed-operations terms may address resulting injury or damage. Reworking the repair and damage to the unit being serviced need separate review.
Only if custody coverage includes the equipment, location, and cause. Outdoor storage conditions can matter.
No. It does not change the policy and its legal effect depends on the circumstances.
Not automatically. Review both the underlying schedule and the additional layer's exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.