

Pallets around shoppers
Forklifts and high racks can cause member or employee injuries. Who was hurt and what equipment was used affect the coverage discussion.
Try a different word, or check the spelling.
A shopper and an employee can be hurt by the same falling pallet. Your insurance review should distinguish their claims, while keeping each department's operator and services clear.
The Southern Agency can review your departments, stock concentrations and handling practices alongside member-data and workforce insurance needs.
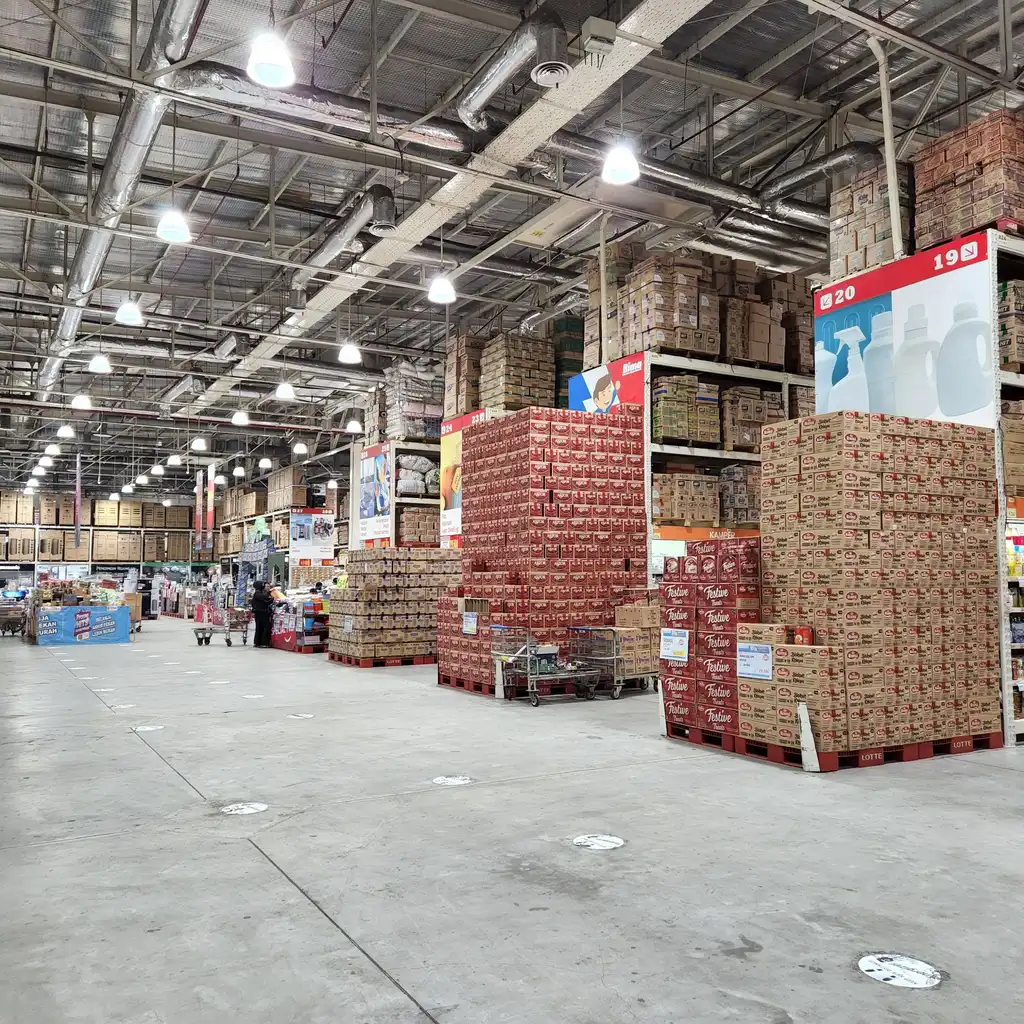
You sell bulk goods from a warehouse-style store, moving pallets and replenishing tall racks while members shop nearby. A falling load can injure someone, and a fire or refrigeration failure can damage a large concentration of inventory.
The Southern Agency can review your stock, handling equipment, and member services to help you choose insurance. We can discuss premises liability and property limits alongside accepted equipment-breakdown benefits, with any additional services considered separately.
Forklifts and high racks can cause member or employee injuries. Who was hurt and what equipment was used affect the coverage discussion.
Bulk stock creates concentrated values. Spoilage after a breakdown differs from ordinary deterioration or lost demand.
Food, fuel, optical or pharmacy operations, if present, have distinct terms. Membership and payment vendors create privacy exposure alongside staffing risks.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A pallet falls during restocking and injures a shopping member and a store employee. Accepted GL may help with the covered customer claim and defense. The employee's work injury needs the actual employer and workers compensation terms; membership or a uniform alone does not decide the role in which someone was hurt. Check equipment and department exclusions and any claims against another operator separately.
An insured compressor breakdown spoils refrigerated stock. Breakdown/spoilage terms may address eligible losses, subject to cause, temperature conditions, and sublimits.
Unauthorized access exposes membership/payment information. Cyber may help with covered response and liability costs, subject to vendor, consent, and reporting terms.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not automatically. Each existing activity must be disclosed and relevant specialty exclusions reviewed.
No. A qualifying cause and included spoilage terms are required; expiry alone is different.
A shopping member's claim generally raises liability questions, while a covered employee's work injury raises workers compensation questions. Establish the person's actual role, employer and activity; membership alone does not decide status, including where someone is both a member and an employee.
Only within its terms and scheduled underlying coverage. It does not automatically fill exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.