

Links
Failures can interrupt important customer services.
Try a different word, or check the spelling.
Your teleport's antennas and amplifiers are terrestrial assets, even when the connection depends on satellite capacity. Ground property and service protection should fit those interests, with interference, orbital assets and SLA credits kept separate from an assumed cyber or equipment-breakdown response.
Bring actual ground-station values and ownership, purchased capacity, customer link commitments and upstream dependencies.
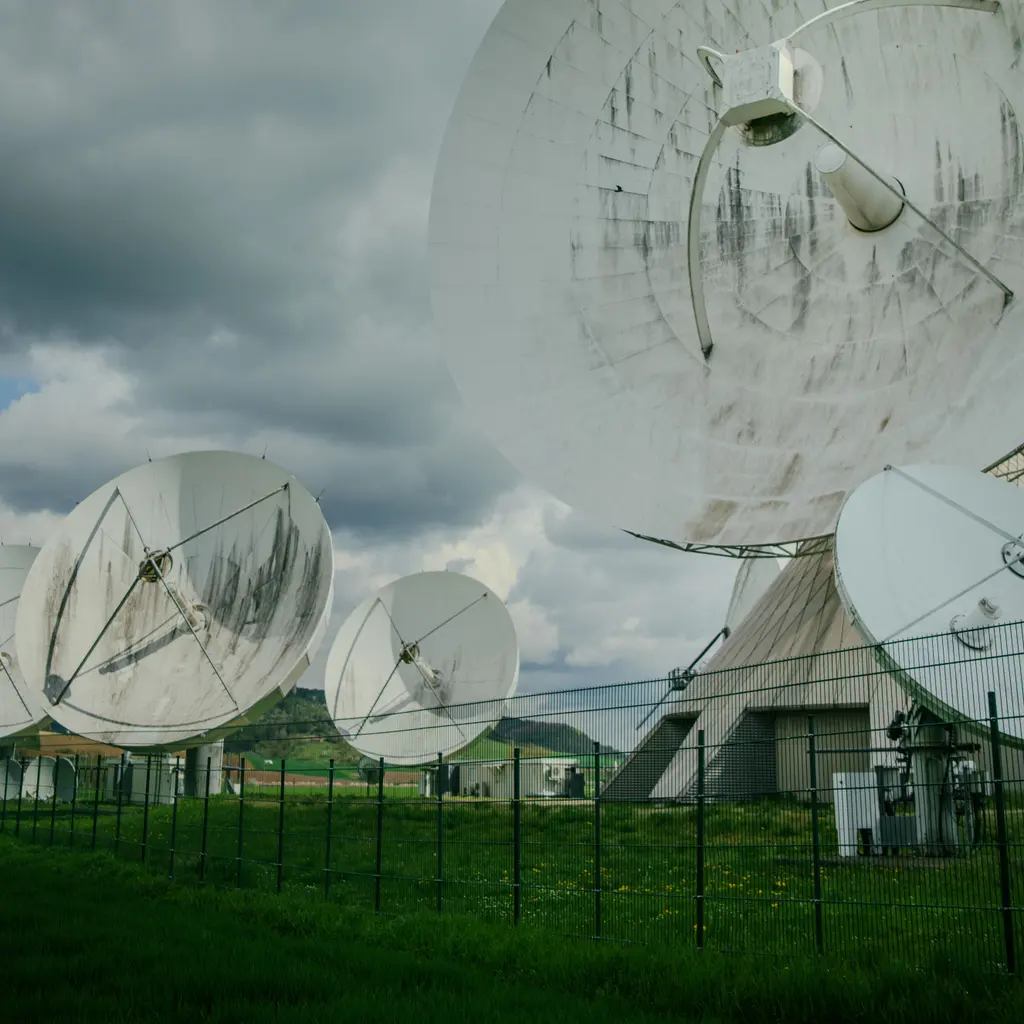
You manage terrestrial links and ground infrastructure for customers. A hardware failure or configuration error can affect multiple connections, leading to potential client claims.
The Southern Agency can help review your ground assets and service duties to select appropriate insurance. We can discuss how to identify and protect your terrestrial equipment rather than assuming one policy covers all orbital interests.
Failures can interrupt important customer services.
Antennas, amplifiers, and backup power can fail.
Teleports concentrate valuable electronics.
Unauthorized access and signal interference can disrupt operations.
Capacity, contracts, and governance create different liability questions.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A ground-station amplifier could fail and interrupt several customer links. Purchased breakdown terms may help with accepted equipment costs, while E&O separately addresses covered link-service allegations. Review the actual failure and customer duties; credits, penalties, your own income and orbital assets do not automatically share that response.
Cyber scope and affected systems determine response.
Lightning could damage terrestrial antennas and support electronics at a teleport. Property may help with insured physical damage under the actual cause, values, limits and deductible. Purchased income terms need their qualifying interruption and restoration provisions; a damaged ground antenna does not establish insurance on the satellite.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Coordinate ground property, technology, data, equipment, and management interests for the real operation.
Accepted link or configuration errors may produce covered client financial-loss allegations.
Penalties, credits, and guarantees may remain contractual costs even after an outage.
Describe the traffic, credentials, customer information and network access actually handled. Accepted cyber terms may help with covered response and privacy/security claims; radio jamming or interference is not automatically a cyber event.
Own ground hardware needs suitable property and breakdown terms; orbital assets are not presumed included.
Use actual customer requests and compare them with available limits and exclusions.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.