

Guests boarding and exploring
Visitors unfamiliar with rail equipment can fall at steps, platforms, or open-air cars.
Try a different word, or check the spelling.
Losing excursion dates in your peak season can affect more than the repair bill for a locomotive. Scenic-rail protection should fit the actual income trigger and guest activities, without treating poor weather, restoration work, or every canceled trip as a covered shutdown.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
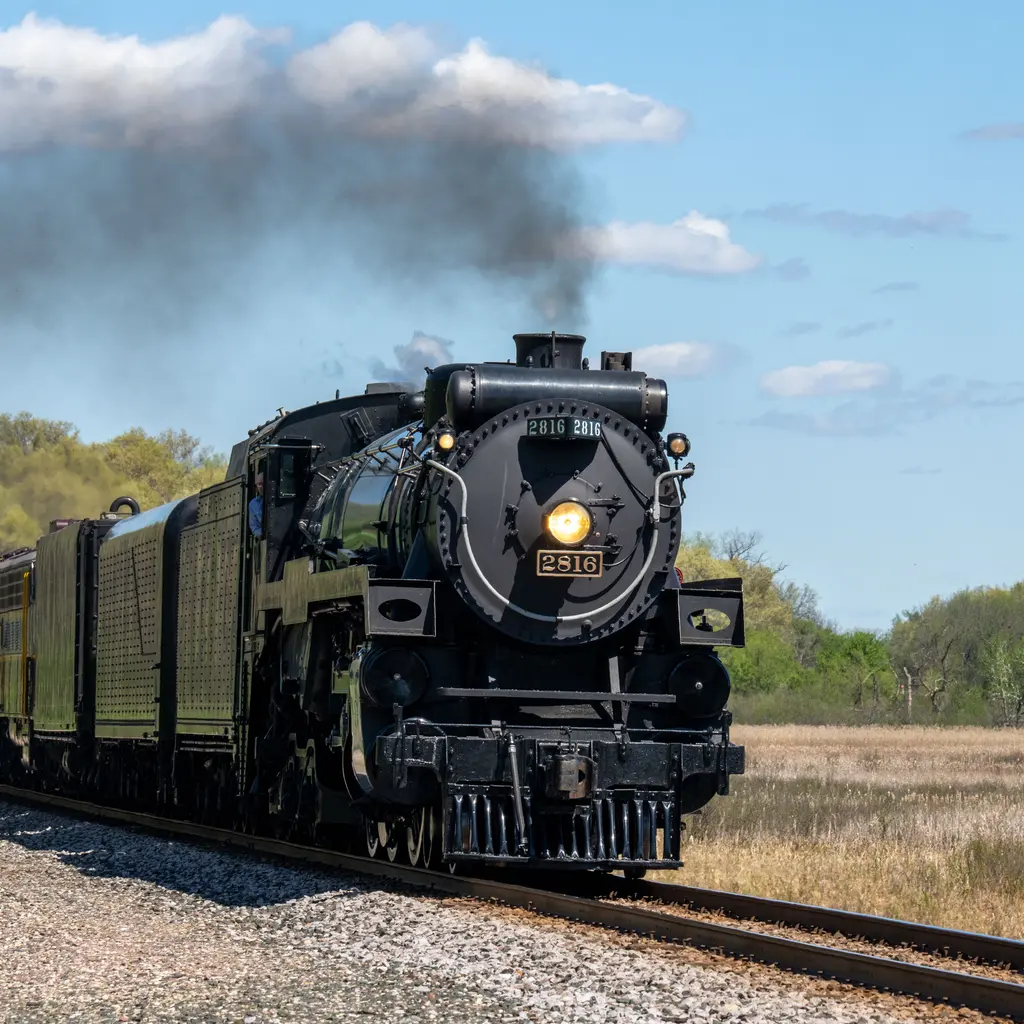
You provide excursion experiences, which may include themed events, depot shops, or dinner services. Connecting your hospitality offerings with your rail operations is vital to protecting your seasonal business.
The Southern Agency can help you review your passenger-facing activities and rail excursions to select appropriate insurance. For example, we can discuss how to obtain coverage that explicitly includes your guest facilities and specific rail movements, which ordinary liability policies might exclude.
Visitors unfamiliar with rail equipment can fall at steps, platforms, or open-air cars.
Limited emergency access can complicate an incident; specialized parts can extend a locomotive repair.
Food, alcohol, and retail sales add exposures beyond moving the train.
A covered shutdown during peak trips can have a larger income effect than one during closure. Poor weather alone does not prove coverage.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A guest alleges unsafe access. Excursion passenger liability and the facts govern the response.
A claimant links an injury to onboard service. Liquor terms depend on the service and insured entities.
Booked excursions stop. Qualifying breakdown and linked income terms determine eligible repair and revenue losses.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Review rail passenger liability and attraction services together, then property, staffing, and income dependencies specific to the operation.
Alcohol service needs direct review of suppliers, venues, and liquor terms; a dinner-train name does not establish coverage.
Match income values and restoration periods to peak bookings, but protection still needs an insured interruption trigger.
They affect emergency access and recovery planning. Disclose terrain and response arrangements without assuming a particular underwriting outcome.
Only when the insured operations and property schedules include it. Retail products and rail passenger claims may have different terms.
Covered breakdown and linked income protection may apply. Routine maintenance, aging, and every refund are not automatically covered.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.