

Machines exposed outdoors
Wind, hail, and theft can affect several tractors or implements at once.
Try a different word, or check the spelling.
The tractor on your lot may be driven for a demonstration and then loaded for delivery. Check protection for the machine as it moves beyond parked display stock.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
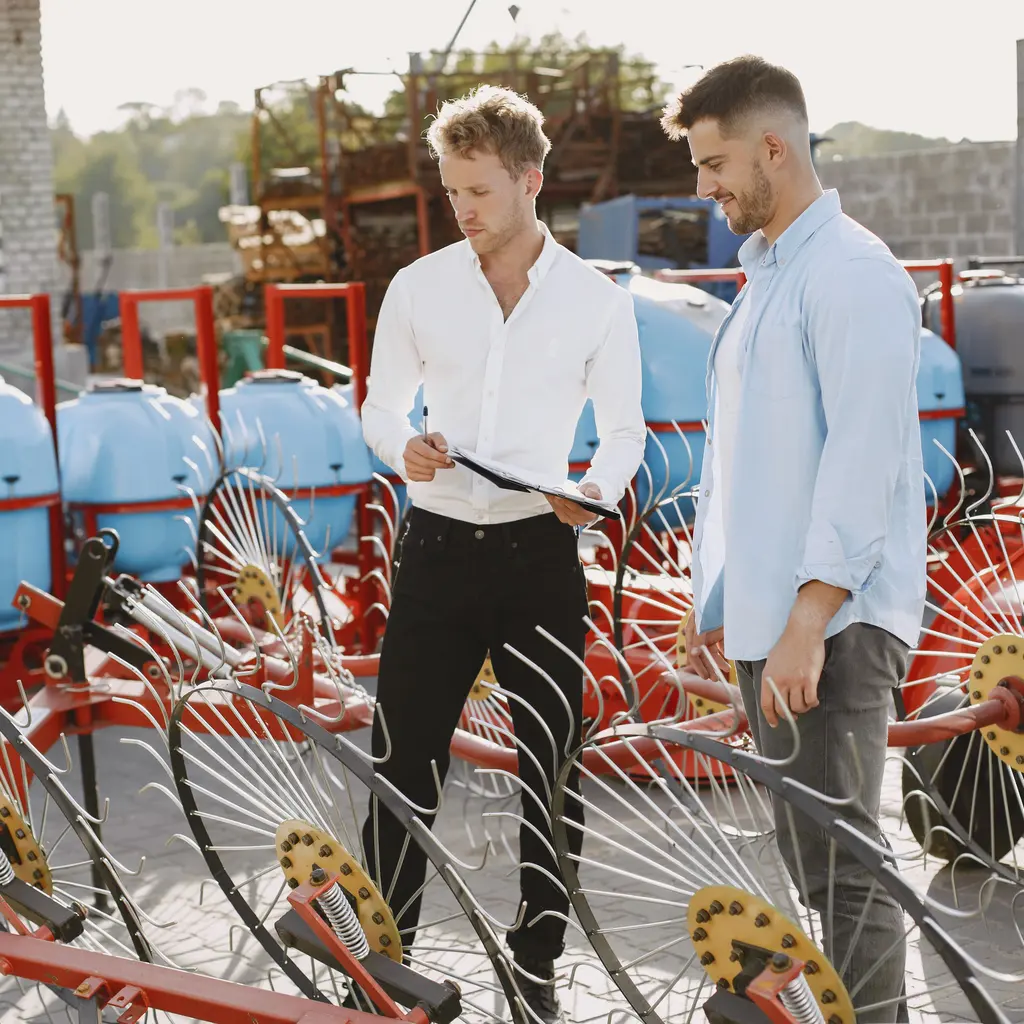
You manage outdoor machinery stock and demonstration sites, which are exposed to weather-related damage, visitor injuries, and transit risks during equipment hauling.
The Southern Agency can review your yard and service activities to help you select insurance for outdoor inventory, powered demonstrations, and vehicle transport.
Wind, hail, and theft can affect several tractors or implements at once.
Blades, hydraulics, and moving equipment can injure customers or damage nearby property.
An alleged defect or service error can cause injury after delivery.
Stock builds before growing seasons, while loading, delivery, and shop work expose staff and valuable units.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Farm and Garden Machinery and Equipment Distributor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hail damages several tractors awaiting sale on the display lot. Property or dealer-stock protection may address covered physical damage if outdoor units and their values are included. Weather deductibles and any per-unit or combined limits can change the recovery.
A mower demonstration injures a customer standing nearby. Review liability terms for powered demonstrations, the location and who controlled the machine. Damage to the demonstrated mower requires its own property review.
A farmer alleges a supplied implement failed and damaged other equipment. Product liability may address covered resulting damage, depending on the product and claim. Warranty replacement, service correction and lost growing time are different cost questions.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Only when the property terms include it; check outdoor locations, hail deductibles, and theft conditions.
Suppliers can face allegations about equipment they resell. Review product protection alongside repair and recall exclusions.
Use peak stock rather than an average month, including equipment awaiting delivery.
Injury liability and damage to the demonstrated machine need separate review, especially away from the lot.
Declare repairs, parts, and customer machines. Faulty work, custody, and shop breakdown do not share one coverage grant.
Suitable cargo or transit protection is needed in addition to auto, with loading and unloading included where required.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.