

Materials affect fire spread
Foams, chemical components, and packaging create different hazards; not all insulation is combustible.
Try a different word, or check the spelling.
Your customer's energy-saving expectation is not the same claim as physical damage caused by a siding or insulation product. Distribution cover needs the actual materials and any foam chemicals, with performance promises, replacing panels, and bulky jobsite delivery considered on their own terms.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
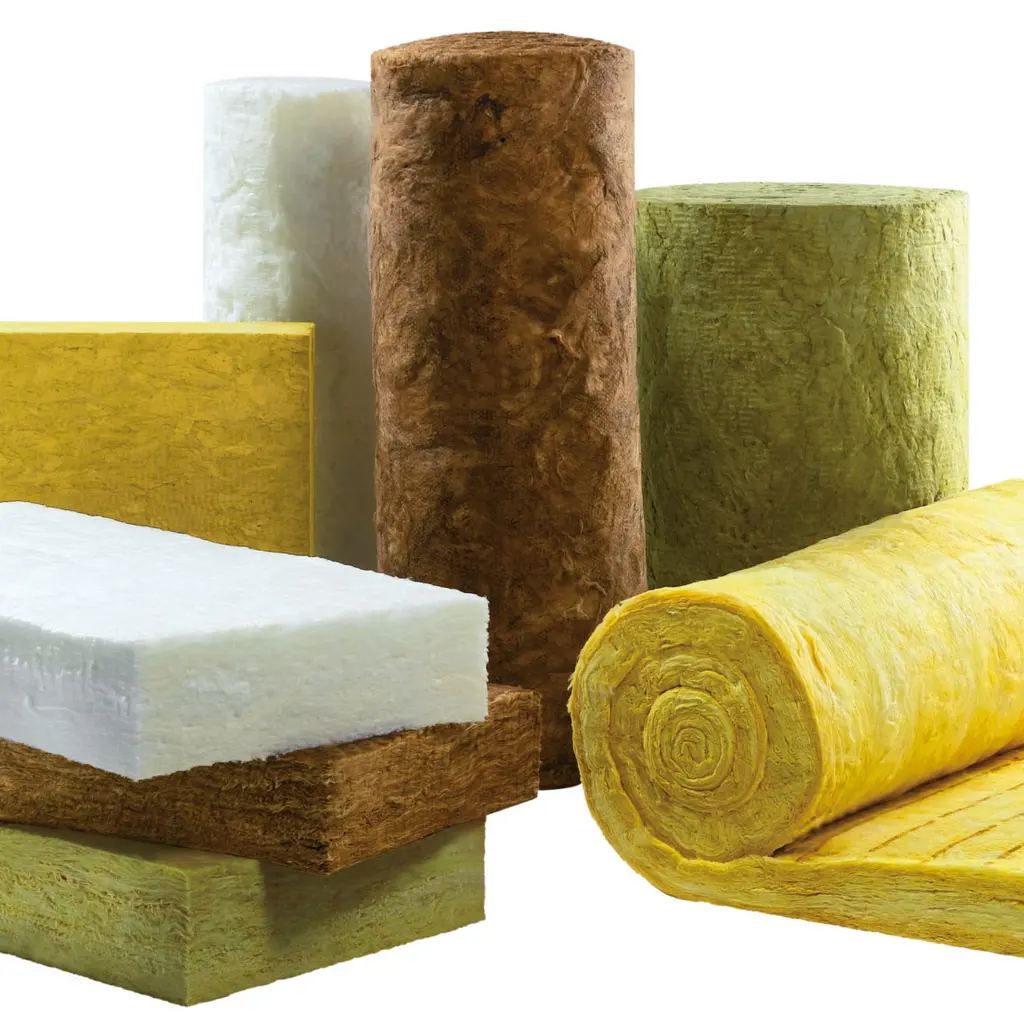
You supply bulky siding and insulation to builders, with foam chemicals included if that is part of your catalog. Stock can be damaged in the yard or during unloading, and an installed product can draw a moisture or performance claim. Combustibility and chemical hazards vary across the materials you sell.
The Southern Agency can review your warehouse operations and supply logistics to help you select appropriate insurance. We can discuss coverage for your foam-chemical inventory and how to define your product liability regarding installation and performance.
Foams, chemical components, and packaging create different hazards; not all insulation is combustible.
Long panels and lightweight bundles can be damaged or strike people during loading.
Warping, moisture or thermal-performance allegations may involve resulting damage or only warranty costs.
Component leaks, manual handling, and account breaches require different protections.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Siding and Insulation Material Distributor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A fire spreads through foam-board bundles and damages stock and the warehouse. Property may help with insured physical damage, with the actual material mix, peak values and protective conditions considered. Purchased income terms address the eligible disruption; replacing stock does not by itself fund every delayed builder order.
A builder reports warped siding after installation and demands new panels and labor to remove the old ones. Establish the cause and whether any other property was damaged. A warranty or appearance dispute alone does not establish product-liability payment for panels, removal or reinstallation.
A long bundle slips while being unloaded and damages a customer's landscaping. Review who controlled unloading, the truck or machinery involved and how auto and general liability allocate that operation. Liability for the landscaping is separate from damage to the bundle itself and from any employee injury.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Actual foam, chemical, and packaging concentrations matter; fiberglass and other materials should not be treated as uniformly combustible.
A reseller can face defect allegations, but warranty replacement, and performance shortfalls are not automatic liability cover.
Yes. Identify formulations, quantities and storage/handling for property, environmental, and employee review.
Coordinate road travel, unloading, and customer-site duties under the actual auto/GL wording.
Suitable cargo/transit protection should match goods, causes and handoffs, separately from the truck.
Ordering/account data can create privacy and downtime losses; financial fraud requires explicit terms.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.