

Outdoor materials
Rain, wind, theft, and gradual weathering can affect yard stock differently. Outdoor property and water exclusions need explicit review.
Try a different word, or check the spelling.
A builder's rejection of out-of-spec material is different from a claim that it damaged the structure. Your materials insurance needs those product boundaries as well as actual outdoor-stock and unloading terms, without assuming every refund, matching cost or construction correction is covered.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
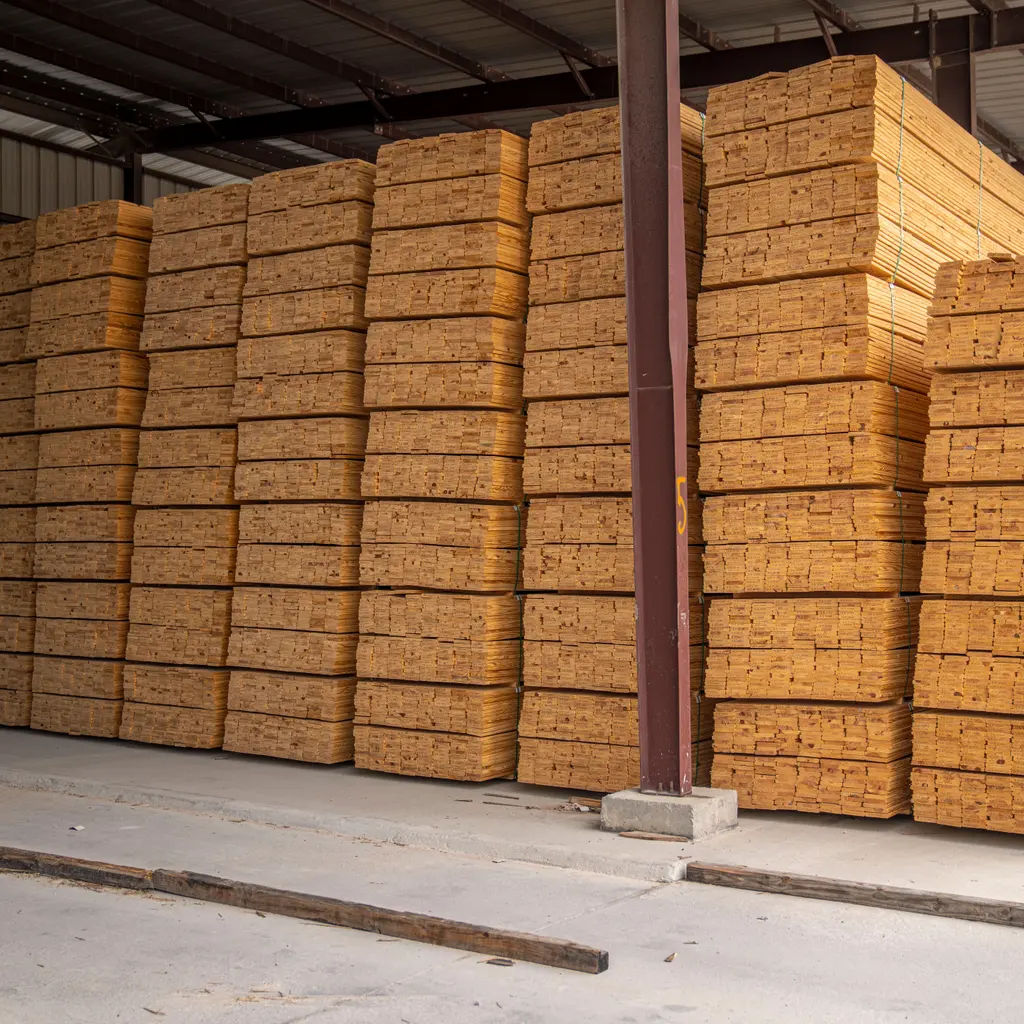
You distribute building materials like lumber or masonry, often keeping stock in outdoor yards and delivering via flatbed or boom trucks. Dropping materials during heavy unloading or experiencing storm damage to an outdoor yard can create losses unique to your operations.
The Southern Agency can review your yard storage and jobsite delivery methods to help you select appropriate insurance. For example, we can compare how inland marine protects materials in transit versus how general liability addresses accidental damage at a jobsite.
Rain, wind, theft, and gradual weathering can affect yard stock differently. Outdoor property and water exclusions need explicit review.
Forklifts and boom trucks can damage loads or jobsite property. Auto/mobile-equipment classifications and unloading boundaries matter.
Materials may be blamed for structural damage. Commercial rejection, warranty replacement, and correcting a construction defect are not universally insured.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A storm damages outdoor packaged materials. Property may address an insured loss if outdoor stock and the cause are included; gradual exposure is different.
A delivery boom damages a customer's structure. Applicable auto/GL terms may address covered damage depending on equipment classification and operation; cargo loss is separate.
A builder alleges supplied material contributed to property damage. Products cover may address a covered resulting-damage claim; replacing out-of-spec material and assumed guarantees need separate review.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not automatically. Outdoor stock, moisture, and weather exclusions can limit payment.
The machinery classification and operating circumstances matter. Coordinate auto and GL terms.
Only if the form includes that interest. Do not assume all motor truck cargo is direct owned-stock cover.
It may be a commercial dispute without covered injury or damage. The allegations and exclusions govern.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.