

Alcohol-related liability is alleged
Serving or sampling and wholesale supply can create different duties under applicable law.
Try a different word, or check the spelling.
Supplying a restaurant and pouring at a tasting can create different alcohol-liability duties for your business. Wine and spirits insurance needs those actual activities and jurisdictions, with premium bottle values, temperature or breakage losses and contamination claims distinguished from intoxication allegations or licensing changes.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
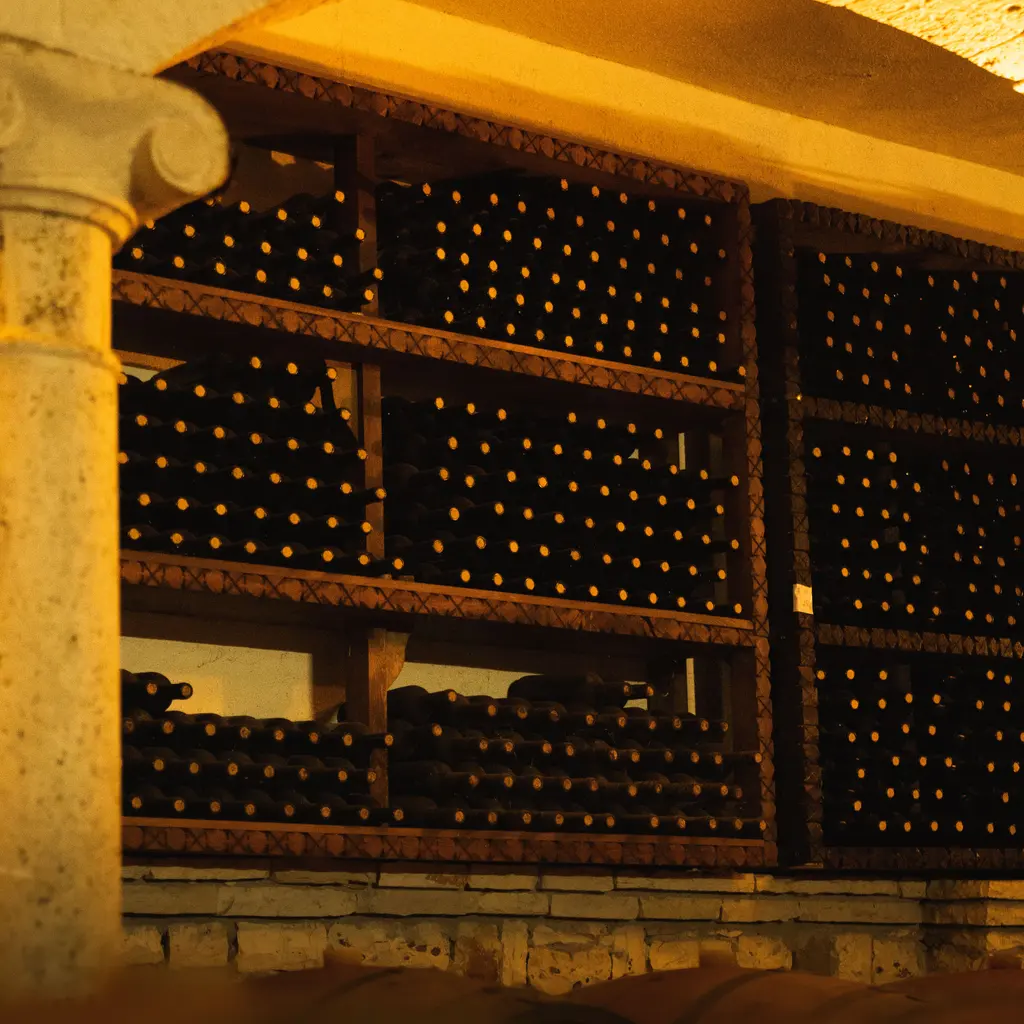
You distribute wine and spirits to restaurants and retail accounts, which involves keeping fragile stock during storage and transit. A broken pallet or a heat-damaged shipment can quickly result in loss, while sampling events introduce unique liability risks.
The Southern Agency can help you review your storage environment, delivery methods, and sampling activities to help you select appropriate insurance. For example, we can help determine how your coverage applies to temperature-related damage during transit.
Serving or sampling and wholesale supply can create different duties under applicable law.
Premium stock can concentrate value at storage and delivery stops.
Wine needs suitable storage; actual alcohol strength and quantities affect fire considerations.
Vehicle accidents and contaminated or defective products create distinct liability and cargo interests; licensing changes can also interrupt trade.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Wine and Distilled Alcohol Beverage Distributor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
After a tasting your staff hosted, an attendee alleges alcohol service contributed to an injury. Review the serving duties, jurisdiction and liquor or event terms. Supplying bottles and pouring drinks should not be assumed to have identical liability protection.
Cases of wine break when a delivery truck stops suddenly. Cargo terms need to accept the goods, breakage cause and packing arrangements. Auto protection for the truck does not itself insure the bottles.
Rare bottles are stolen from the warehouse overnight. Property theft terms may address covered stock loss, with valuation and security conditions met. Employee involvement would require separate review of any crime protection.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Assess applicable supplier/furnishing duties and any tastings. Do not assume either universal need or no exposure solely because staff usually do not pour.
Only suitable property or cargo terms accepting the breakage cause apply; ordinary inventory damage limits are insufficient.
Review outside theft and employee dishonesty separately, with peak values, security, and ownership.
Specific temperature/spoilage terms may be needed; ordinary heat, poor storage, and delay can be excluded.
Auto addresses selected road interests; cargo must accept the bottles, breakage, theft, and temperature causes.
Covered contamination or defect harm may qualify, while liquor allegations, withdrawal, and replacing stock need separate treatment.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.