

Frost, heat, and water stress
Cold, heat, and inadequate water can damage avocado trees or reduce fruit production. Describing those risks does not mean the farm's property policy insures the trees or crop.
Try a different word, or check the spelling.
An irrigation repair can be finished long before an affected avocado block recovers. Your insurance needs to distinguish the cost of fixing equipment from the crop you depend on.
The Southern Agency can help you align your avocado farm's insurance with its specific infrastructure and harvest needs.
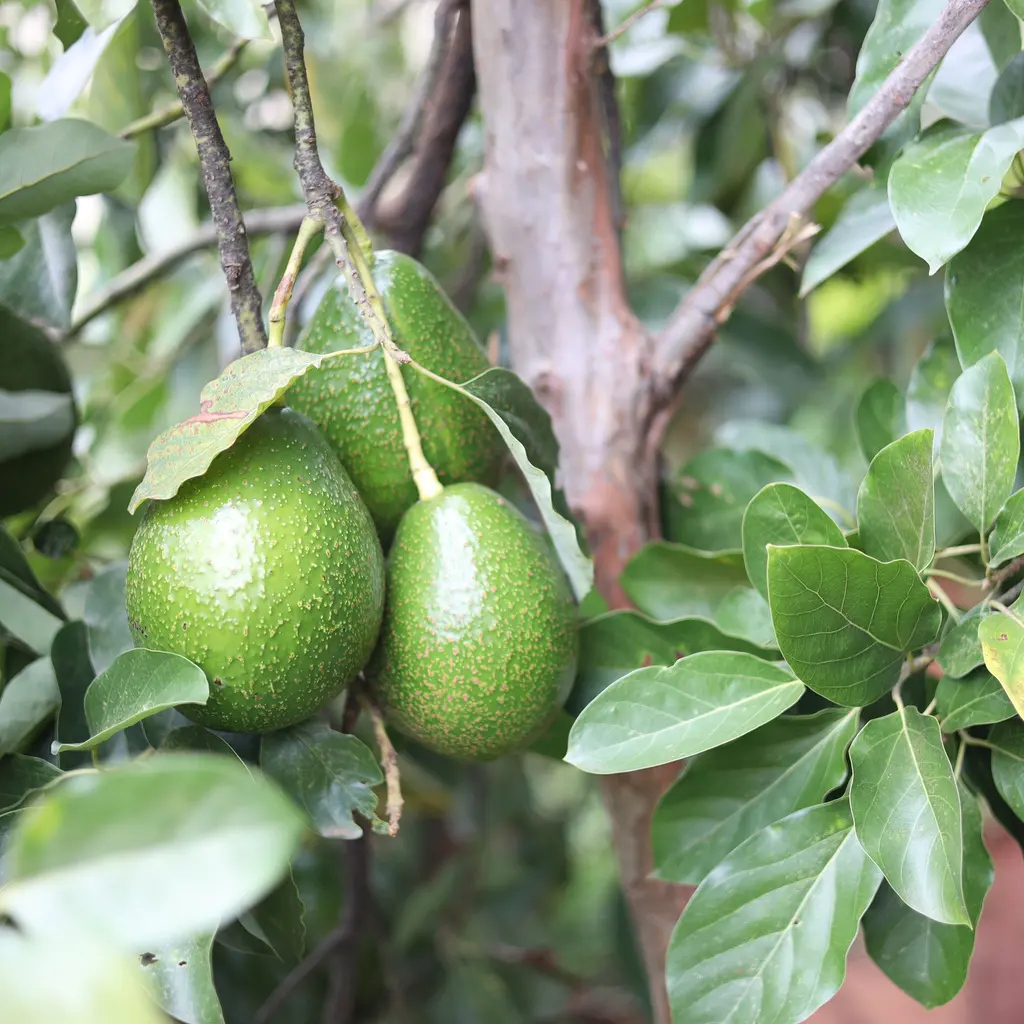
You tend avocado trees through the growing season, relying on irrigation and harvest crews to bring the crop to market. Frost, fire or a failed pump can damage property or stress the crop, while picking and work on slopes create injury risks.
The Southern Agency can review your grove, irrigation equipment, and harvest arrangements to help you select insurance. We can discuss property and equipment protection alongside seasonal-worker needs, with living trees and fruit given separate attention.
Cold, heat, and inadequate water can damage avocado trees or reduce fruit production. Describing those risks does not mean the farm's property policy insures the trees or crop.
Where wildfire exposure exists, trees, irrigation lines, buildings, and equipment may be damaged in one event. Access and dispersed values affect the loss picture.
Pump, filtration, or delivery-system failure can interrupt water to affected blocks, creating equipment repair costs and a separate threat to the planting.
Theft of fruit from trees or harvested bins can reduce saleable inventory. The stage and location of the fruit matter when checking whether it is insured property.
Where picking takes place on hillside terrain, ladders, poles, and uneven access create fall, strain, and cut exposures for crews.
Fertilizer, pesticide, and fuel handling can lead to alleged soil or water contamination, including at storage and mixing locations.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A pump motor fails electrically and water cannot reach part of the grove. Equipment breakdown may address covered motor repairs. The resulting tree stress or lost avocado production needs its own insured cause and coverage; it is not automatically part of the repair claim.
An outside driver's fall leads to an allegation that the loading area was unsafe. General liability may address a covered premises claim. The driver's employment status, vehicle involvement, and any contractual assumption of liability can change which policy applies.
A container leaks and contaminates soil beside the chemical store. Premises pollution may address covered cleanup if that site and condition are within scope. Historical contamination, known conditions, or a form limited to off-site work can restrict payment.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Coverage for trees and crop loss from named perils may be available depending on the operation, but it is often arranged separately. The scope depends on the specific policy and underwriting.
Equipment breakdown coverage may respond when pumps or motors fail mechanically or electrically, depending on the specific policy, limits, and exclusions. Property coverage may apply to other infrastructure.
Property coverage may respond to fire damage to buildings and equipment, but availability and terms in high-wildfire areas depend heavily on underwriting and the grove's location.
Chemical storage and application can create pollution exposure that standard policies commonly exclude. Environmental liability coverage may help, though availability depends on underwriting and operations.
Crews hand-harvesting on slopes carry injury exposure, and workers compensation is often required once you use employees, depending on operations and applicable state rules.
Premiums commonly reflect acreage, irrigation value, regional perils, equipment, payroll, and loss history. Final pricing depends on underwriting and the specifics of your grove.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.