

Damage to customer equipment in your care
Tractors and combines left for repair can be damaged by fire, theft, or mishap while in the shop's custody, an exposure general liability usually excludes.
Try a different word, or check the spelling.
A grower needs that combine back in the field, and you need protection while it is in your shop. The insurance questions continue after the repaired machine leaves.
The Southern Agency can help you match your repair and maintenance services with insurance for your shop, tools, and customer property.
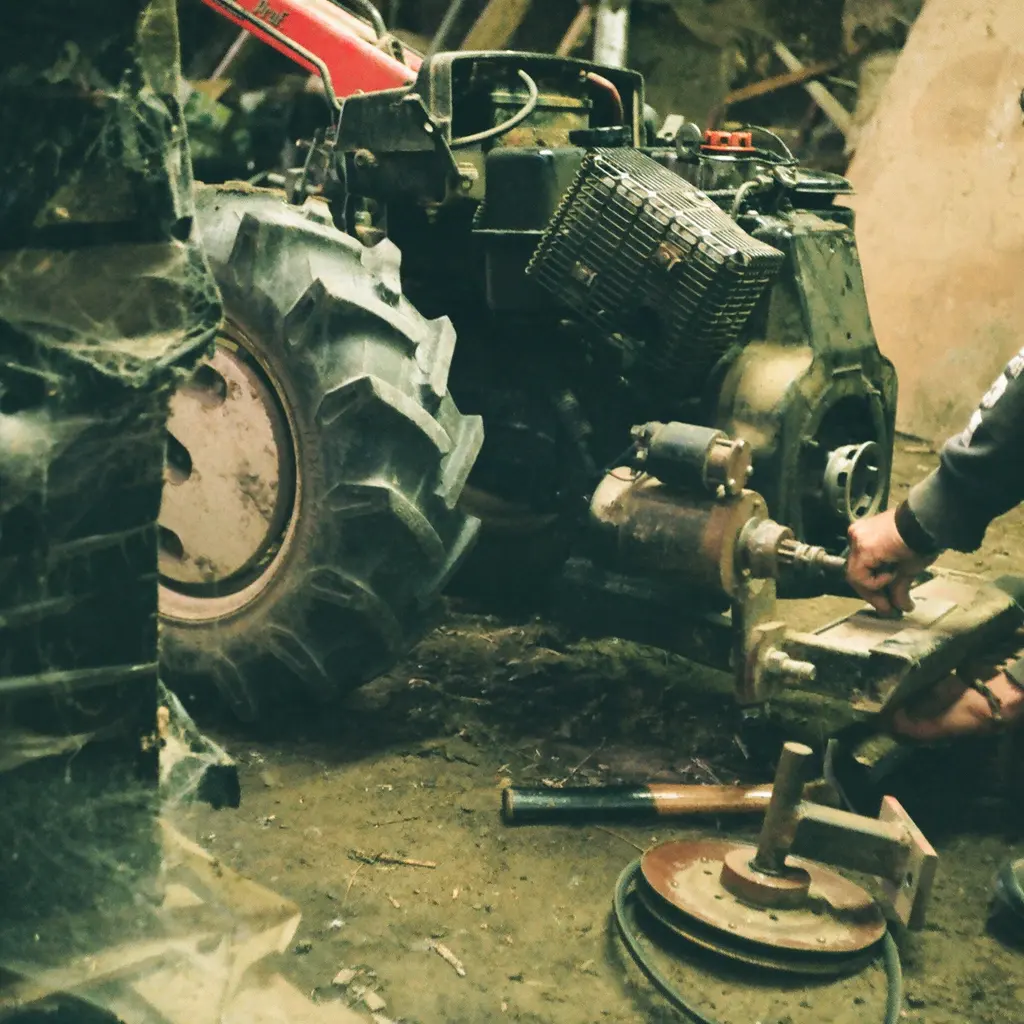
You provide maintenance and repair for tractors, combines and implements in your shop or directly in the field. Your work involves risks like potential damage to a customer's machine during testing or an injury claim if a repaired implement fails while in use.
The Southern Agency can review your shop practices, such as welding, lifting and field calls, to help select appropriate insurance. For example, we can help identify whether your coverage accounts for customer equipment while it is in your custody compared to the liability coverage needed for completed repair work.
Tractors and combines left for repair can be damaged by fire, theft, or mishap while in the shop's custody, an exposure general liability usually excludes.
A repair that fails mid-harvest can cause downtime, crop loss, or further damage, prompting claims tied to the work performed.
Welding, grinding, and handling fuel and hydraulic fluid create ignition sources that threaten the building, parts, and equipment inside.
Heavy lifts, presses, and working under raised implements expose technicians to crush, strain, and equipment injuries.
Repairs performed at a customer's farm during harvest put technicians and tools in changing, off-site conditions away from shop controls.
Diagnostic equipment, specialized tools, and parts inventory can be lost to theft, fire, or damage at the shop or on a service truck.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Farm Equipment Repair and Maintenance Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A support slips during service and damages a combine. Customer-equipment coverage may respond if the machine, activity, and cause fit the form and limits. A garage liability heading alone does not establish custody coverage or payment for faulty workmanship.
A repaired hydraulic assembly fails and damages other property after return. Completed-operations liability may address a covered resulting-damage claim, subject to exclusions. Redoing the repair, refunding the invoice, and paying for a missed harvest are separate questions, not automatic consequences of that coverage.
A welding spark starts a fire that damages shop-owned parts and customer machines. Property coverage may address insured shop assets, while customer machinery needs applicable custody or property-of-others terms. Peak accumulated values and each section's limit can affect recovery.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Do not assume that. Liability from operations and damage to property in custody are different. Confirm the actual customer-equipment or bailee provisions, eligible machines, insured activities, causes, and limits; an auto-focused form may not fit implements.
Separate a covered injury or resulting property-damage claim from correcting your work, warranty promises, and a customer's lost harvesting income. Completed-operations wording and exclusions, not the urgency of the season, determine the scope.
Check the service territory, activities, technicians, customer-machine custody, testing, and transport. Mobile tools need off-site terms; truck physical damage does not itself insure the tools or customer machine.
Use the largest individual machine and the greatest total value in care, including seasonal accumulation and outdoor storage. Review per-item, location, and aggregate limits and how the form values damaged equipment.
Not simply because they are inside the building. Review property-of-others or custody coverage and its terms separately from the shop's building, lifts, tools, and parts.
Provide actual duties, field travel, welding and lifting work, states, payroll, and employment arrangements. Review state workers-compensation rules and policy classifications rather than assuming the agricultural setting determines them.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.