

Moisture intrusion behind cladding
Faulty flashing, sealing, or drainage detailing can trap water behind EIFS, causing hidden framing decay and mold over time.
Try a different word, or check the spelling.
Your finished elevation can look complete while moisture detailing remains hidden behind it. Liability for later resulting damage needs a closer look than cover for mixers, sprayers, and scaffolds alone.
The Southern Agency can review your installation practices and project requirements to help secure appropriate coverage.
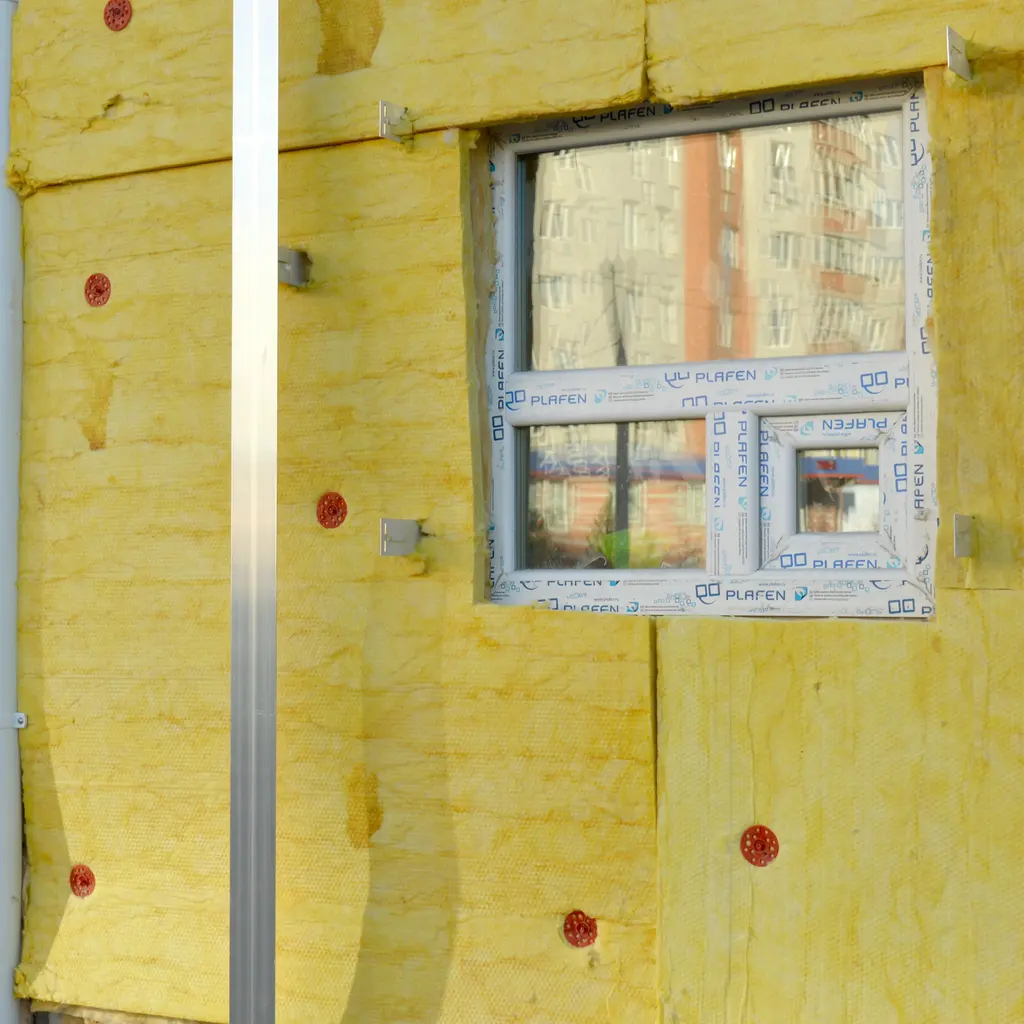
You install multilayer synthetic-stucco cladding, a process that requires precise moisture detailing and sealing. If water infiltrates behind the cladding, it can lead to long-term rot or mold growth that may not be discovered for years, potentially resulting in complex liability claims.
The Southern Agency can review your actual EIFS systems, detailing duties and project requirements to help you choose insurance. We can check primary and excess exclusions for the work, separate damaged framing from cladding correction, and review the policy history relevant to a later moisture claim.
Faulty flashing, sealing, or drainage detailing can trap water behind EIFS, causing hidden framing decay and mold over time.
Moisture damage often surfaces months or years after installation, producing late, sizable, and frequently litigated claims.
Applying cladding across multi-story elevations from scaffolds and lifts exposes crews to serious fall injuries.
Wet base and finish coats can be marred by weather, other trades, or contact before curing, requiring rework.
Disagreements over substrate preparation and detailing responsibility can fuel disputes when a wall later fails.
Mixers, sprayers, and scaffold systems are valuable and exposed to theft and damage as crews move between sites.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Exterior Insulation and Finish System and EIFS Contractor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Rotted framing is found behind EIFS two years later. Review actual EIFS acceptance/exclusions, resulting framing/interior damage, cladding correction, water/fungi and policy timing separately. Neither delayed discovery nor a completed-operations limit establishes cover for the whole wall claim.
A flashing detail is blamed for wall failure. Identify the agreed design, substrate and interface responsibilities, actual approvals, and the defined professional service. Review resulting harm separately from correction or warranty work; a detailing dispute does not automatically become an insured professional claim.
An applicator falls while finishing an upper-story wall and is injured. Workers' compensation may respond to medical care and lost wages, subject to the policy and state rules.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
EIFS contractors commonly carry general liability with completed operations, workers' compensation, inland marine, business auto, and often professional liability. The right mix depends on systems and projects, subject to underwriting.
Trapped water behind EIFS can cause hidden decay that surfaces years later, driving large claims. Insurers may scrutinize detailing practices, and coverage availability depends on underwriting.
Yes, but first confirm that the actual EIFS system and work are accepted. Compare the damage dates, policy history and completed-operations terms, including EIFS, water and fungi restrictions. A later discovery does not identify the responding policy, and replacing defective cladding is separate from resulting framing or interior damage.
Describe the design or detailing you actually perform and who approves the assembly. Any offered professional form must accept those services and be coordinated with GL, especially injury, property-damage and manufactured-product exclusions. A missed performance promise or correcting the wall alone is not automatically a covered professional loss.
Inland marine commonly covers scaffolds, mixers, and sprayers at job sites and in transit. Coverage depends on the specific policy and how items are scheduled.
Workers' compensation may respond to medical costs and lost wages from falls at height, subject to policy terms and state requirements.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.