

Work over and in the water
Crews operating from barges and shorelines face drowning, struck-by, and vessel hazards. Actual duties, locations, employers and vessel connections need separate state, Longshore or vessel-crew review.
Try a different word, or check the spelling.
The people placing stone for your project may work from shore, a barge or both. Their actual duties matter when reviewing injury benefits, just as afloat equipment needs its own insurance attention.
The Southern Agency can review your marine operations and project requirements to help you select appropriate insurance.
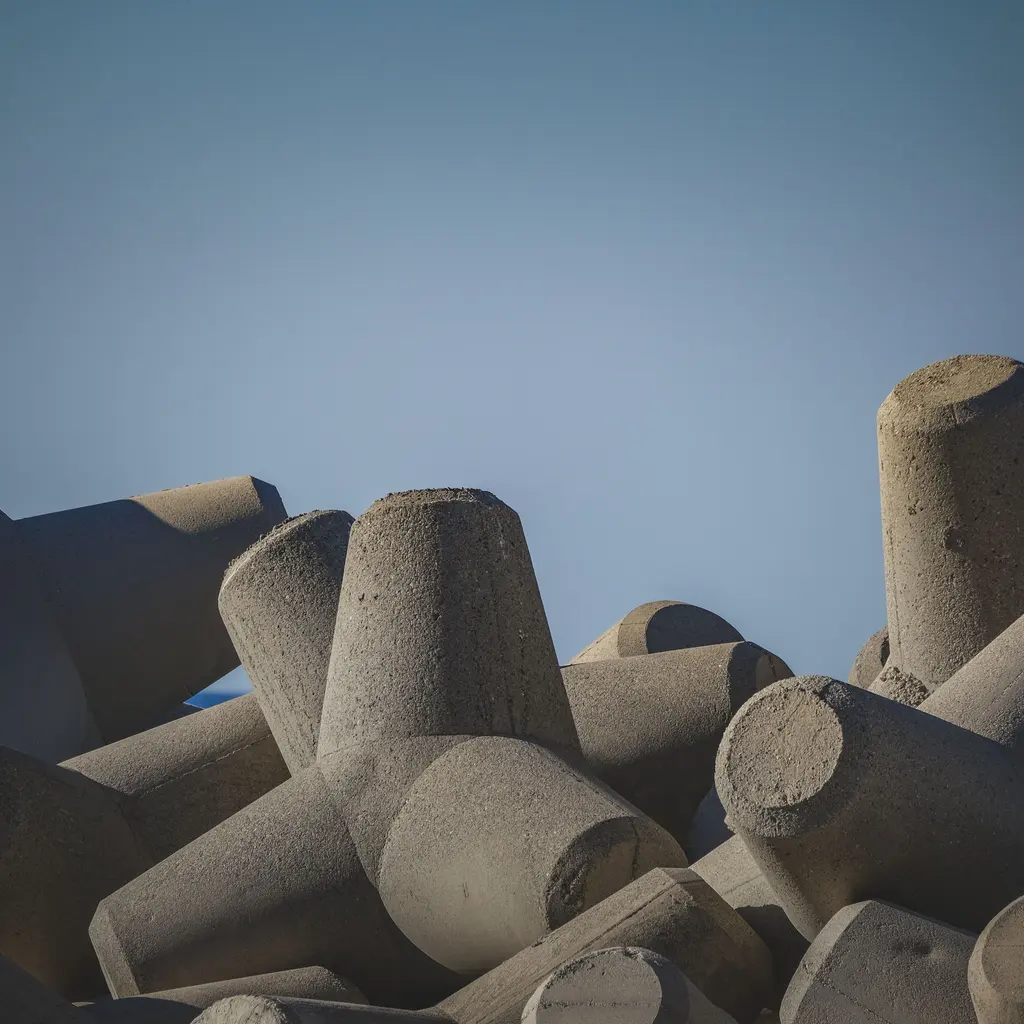
You build or repair shoreline structures like jetties using heavy equipment and barges in tidal or storm-exposed waters. The environment creates risks such as equipment capsize, sediment disturbance, or storm damage to unfinished work.
The Southern Agency can review your shore and afloat duties, equipment interests and project requirements to help choose insurance. We can examine worker status separately from vessel or contractor liability, and compare accepted storm and pollution terms with the owner's requests. A generic maritime endorsement does not settle every worker's benefits.
Crews operating from barges and shorelines face drowning, struck-by, and vessel hazards. Actual duties, locations, employers and vessel connections need separate state, Longshore or vessel-crew review.
Hoisting armor stone and concrete units from floating plant creates dropped-load and capsizing exposure on unstable surfaces.
Seabed disturbance or spilled fuel can prompt cleanup demands and claims involving sediment or known contaminants. Actual releases, permit duties and ordinary turbidity controls need separate review; a permit issue is not itself proof of insured pollution damage.
Waves, currents, and storms can damage partially completed structures and stranded equipment before a project is finished.
Barges, tugs, cranes, and amphibious machines are high-value assets exposed to sinking, collision, and breakdown.
An actual shoreline contract or applicable rule may require performance or payment bonds, specified liability limits, or proof of pollution coverage. Issued terms and separate surety approval need comparison with those requests.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Jetty or Breakwater Construction Contractor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a lifted armor stone damages a nearby vessel. Review accepted marine/rigging operations and watercraft, custody and load terms for covered third-party damage. Identify the vessel owner, lift contractor and floating-plant interests; ordinary GL does not automatically cover the vessel, dropped unit and crane together.
Hypothetical: placement equipment releases fuel into the water. Pollution terms may address included response or third-party claims if the actual equipment, material, location and operation are accepted. Preserve incident and notification records; routine sediment controls, normal disposal, fines and project delay are separate questions.
Hypothetical: a storm scatters partially placed breakwater stone. Project-property terms may address covered physical loss if the actual storm/tidal cause, work stage, ownership and period are included. Establish physical loss and restoration needs separately from original placement deficiencies, ordinary maintenance or promised channel access.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Floating plant, vessel operations, coastal sediment and worker duties raise different liability, property and legal questions. Hull, equipment, contractor liability, pollution and applicable worker terms may address different covered interests. Review the actual operations and policies; one contractor policy or the fact that work is over water does not establish all those interests are insured.
State workers' compensation or Longshore terms may provide qualifying employee benefits, while vessel-crew remedies under the Jones Act require separate review. Establish actual duties, employer, location and vessel connection under applicable law. A state policy or generic maritime endorsement does not settle every worker's status or ensure no gap.
Read the actual permits and contracts for requirements. Environmental terms may address covered cleanup or third-party claims from included sediment or fuel releases. Review accepted operations, pre-existing contamination and reporting; a permit requirement is not proof of coverage for every release, fine or ordinary compliance cost.
Identify the owner's and contractor's actual insurance duties, insured interests, stone/unit values and placement stages. Project-property terms may address included physical loss during the insured period, but review storm, wave, tidal and flood restrictions and ending events. Correcting placement, maintenance or a promised channel depth is not automatically insured.
Check the actual public/private contract and obligee. Performance and payment bonds address different bonded obligations, subject to terms and surety approval; they are not the contractor's accident or storm insurance.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.