

Transit damage to home sections
Oversize modular sections can be damaged or struck while being hauled from the plant or dealer to the home site.
Try a different word, or check the spelling.
Your customer's home changes from a transported section into an assembled building over several handoffs. Protection needs to address the unit during hauling, lifting, and site assembly, not only the trailer or crane.
The Southern Agency can help you match your installation and transit risks with tailored insurance options.
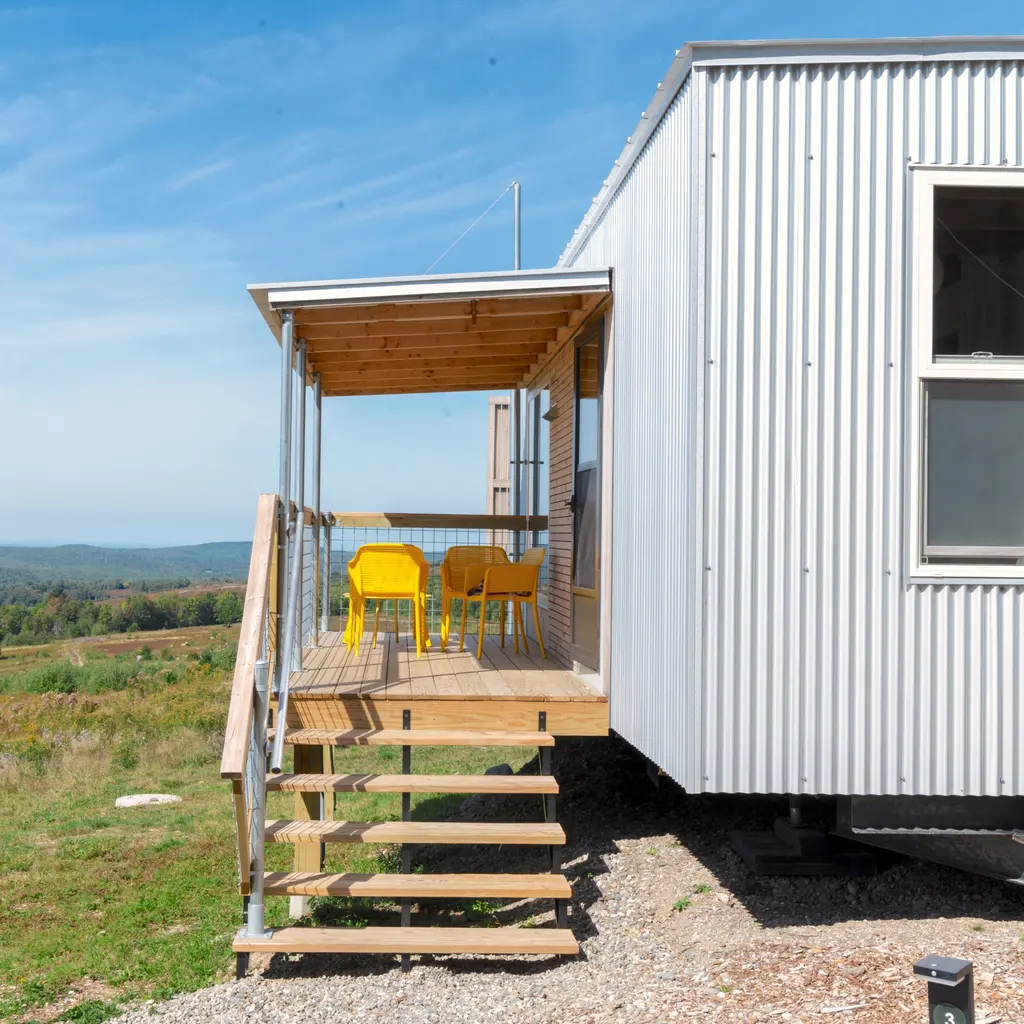
You set factory-built homes or join modular sections on prepared foundations, with transport and utility work handled by your crew or other contractors. A dropped section can damage the home before handoff, while anchoring or connection errors can cause water or structural damage later.
The Southern Agency can help you review your assembly and site preparation duties to select appropriate insurance. For instance, we can discuss how your policy covers a modular unit while it is being craned onto a foundation versus when it is in transit on a trailer.
Oversize modular sections can be damaged or struck while being hauled from the plant or dealer to the home site.
Lifting and placing a section onto the foundation risks dropping or misaligning a high-value unit in the contractor's care.
Improper piers, anchoring, or tie-downs can lead to settling, shifting, or water intrusion that emerges after the home is occupied.
Connecting electrical, gas, plumbing, and HVAC creates fire, leak, and code-compliance exposure if work is faulty.
Workers joining modules, crawling under units, and rigging lifts face fall, crush, and strain injuries during set and finish.
Marriage-line leaks, trim defects, or finishing problems can prompt callbacks, warranty claims, and customer disputes.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
Ready to compare options?
Get a quote for Manufactured or Modular Home Contractor Or call 1-800-777-1TSAThese hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A modular section is struck and cracked while being hauled to the site. Inland marine transit coverage may respond, depending on policy terms, limits, and exclusions.
A storm damages a home being assembled on its foundation before completion. Builders risk may respond to covered damage, subject to the specific policy and provisions.
Improper anchoring allows a home to shift, leading to a damage claim. Liability and completed-operations coverage may respond, depending on the policy and the facts.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Review actual home ownership, insured interests/values, carrier responsibility, and loading, transit, storage, and unloading terms. Inland marine is a category, not proof fragile home sections or every stage are insured.
Often yes. Once a home is being assembled on its foundation, builders risk may respond to fire, storm, or theft before turnover, subject to policy terms and provisions.
Read actual dealer/owner, hauler and crane/set contracts and preserve condition/lift records. Responsibility and first-party home damage versus riggers liability depend on facts and terms; temporary custody alone does not establish a covered loss.
Disclose actual gas, electrical, and plumbing tasks and accepted operations. Review resulting injury or other damage separately from reconnecting defective work, the serviced unit, and any warranty/code promise.
Review actual employees, subcontracted setting crews, and applicable state requirements. Small crew size, subcontractor status or a certificate alone does not establish an exemption or the setter's policy rights.
Review actual carriers, vehicle classification/scheduling, road liability/physical damage, and oversize practices. Separate permits and carrier contracts from home-section cargo/transit terms; auto physical damage is not blanket load coverage.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.