

Cracked or chipped slabs
Costly marble can crack or chip during fabrication, lifting, transport or installation, requiring repair or replacement.
Try a different word, or check the spelling.
The piece you template and polish still has to survive delivery and fit safely in place. Stone protection during handling deserves its own attention alongside cover for the saws and other fabrication machinery.
The Southern Agency can help you protect your fabrication equipment and material handling operations.
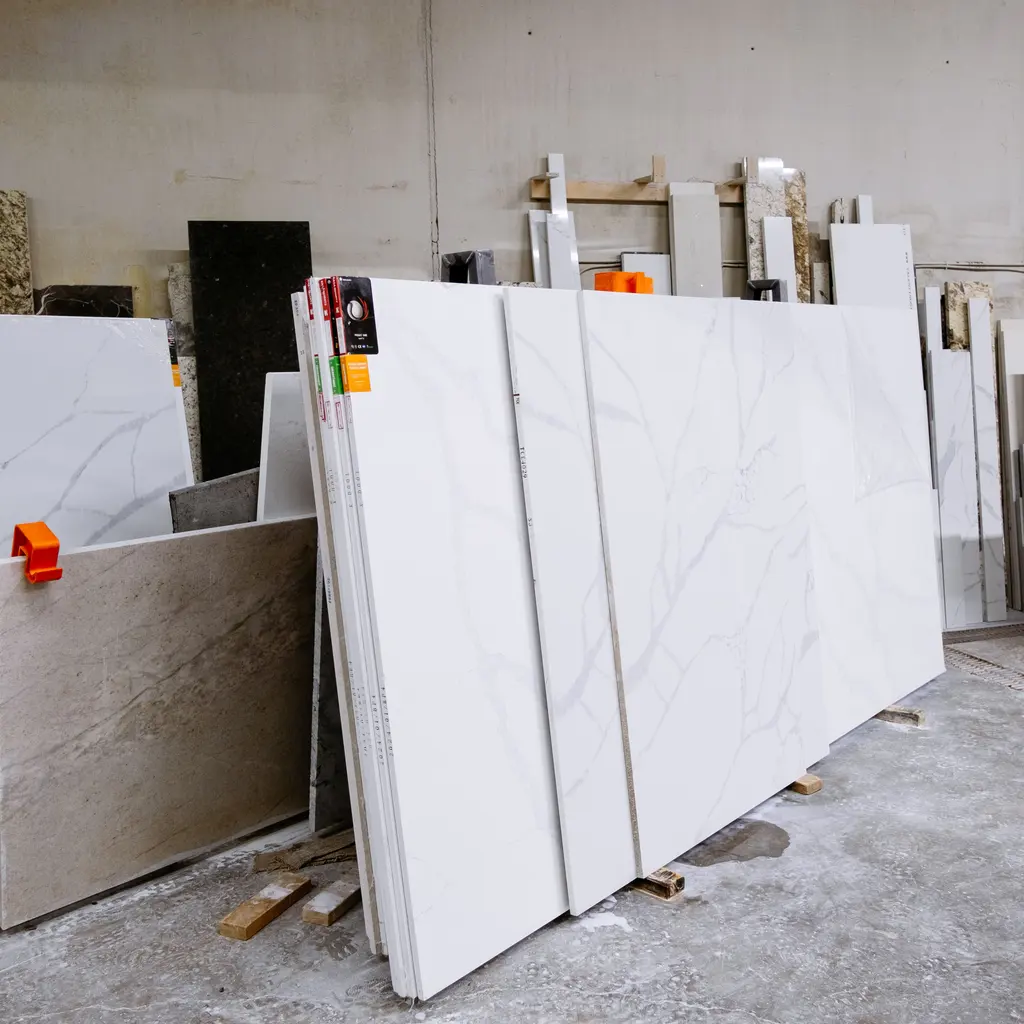
You fabricate and install heavy, fragile natural stone for countertops and decorative features. A crack during transit or a failure of an inadequately supported piece can lead to expensive losses and potential injury claims.
The Southern Agency can help you review your shop fabrication and on-site installation processes to choose appropriate insurance. We can discuss, for example, how to secure coverage for stone slabs during transit separately from mechanical breakdown protection for your CNC machines.
Costly marble can crack or chip during fabrication, lifting, transport or installation, requiring repair or replacement.
Assess actual stone content, tasks, and controls in the shop and on site. Natural marble generally contains much less crystalline silica than many granite, quartzite, or engineered products. Low content is not proof every task is safe, and mixed shops should disclose all materials.
Heavy slabs and countertops create serious crush, pinch, and strain hazards for shop and installation crews.
Improperly supported countertops or stone cladding can detach or collapse, injuring people or damaging cabinetry and finishes.
Bridge saws, CNC machines, polishers, and slab inventory can be damaged, break down, or be stolen.
Templated and polished pieces are fragile and can be damaged en route from the shop to the job site.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a polished top cracks while being set on cabinets. Installation/property terms may address covered loss if ownership, cause and setting stage are included. Check values and fragile-material/processing restrictions; custody alone does not insure re-fabrication. Separate the cracked piece from any injury or cabinet damage.
Hypothetical: an island top fails and injures a homeowner. GL may address covered resulting injury under accepted installation and completed-work terms. Preserve support, substrate and handoff records; correcting the top or its supports is separate from injury liability and a workmanship promise.
Hypothetical: an electrical failure stops a bridge saw. Equipment breakdown may address covered repair to the insured machine; investigate cause separately from wear and maintenance. Lost income or extra expense needs its own covered trigger, terms and waiting period, not just an idle shop.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Property or installation coverage may address a covered loss to insured stone. Check material, ownership, value and storage, transit, cutting or setting stages with breakage and processing restrictions. Equipment insurance or custody alone does not establish that every crack or re-fabrication cost is insured.
Actual stone, silica content, tasks, and shop and field controls matter. OSHA distinguishes natural marble's generally low silica content from higher-content stones and some engineered products, without treating low-content work as automatically safe. Provide material and exposure-control records rather than a marble-only assumption for a mixed shop.
Completed-operations terms may address covered resulting injury or other-property damage. Review those claims separately from replacing the top, correcting supports or honoring a finish or performance warranty. Failure after handoff alone does not establish coverage.
Equipment breakdown may help repair an eligible insured machine after a covered electrical or mechanical failure. Check saw, CNC, and polisher terms separately from wear and maintenance. Income or extra expense requires its own covered event, limits, and waiting period; listing a machine does not insure every shutdown.
An eligible shop may combine liability with specified property in a BOP. Describe actual fabrication, machinery, stock, and customer interests. Review off-site stone handling, vehicles, employees and breakdown separately rather than assume a package includes them all; a shop location alone does not establish eligibility.
Inland marine may insure covered loss to included stone loads. Provide vehicle and A-frame trailer details, load values, and handling or securement responsibilities and check fragile-material transit terms. Truck or trailer physical damage does not automatically insure the stone.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.