Skip to content

Swimming Pool Contractor Insurance

If you service a pool as well as build it, your responsibilities continue into pumps, heaters and chemical handling. Those duties need to fit the coverage rather than rely only on protection arranged for construction.

The Southern Agency can help you protect your business through coverage that spans excavation, construction and long-term liability.

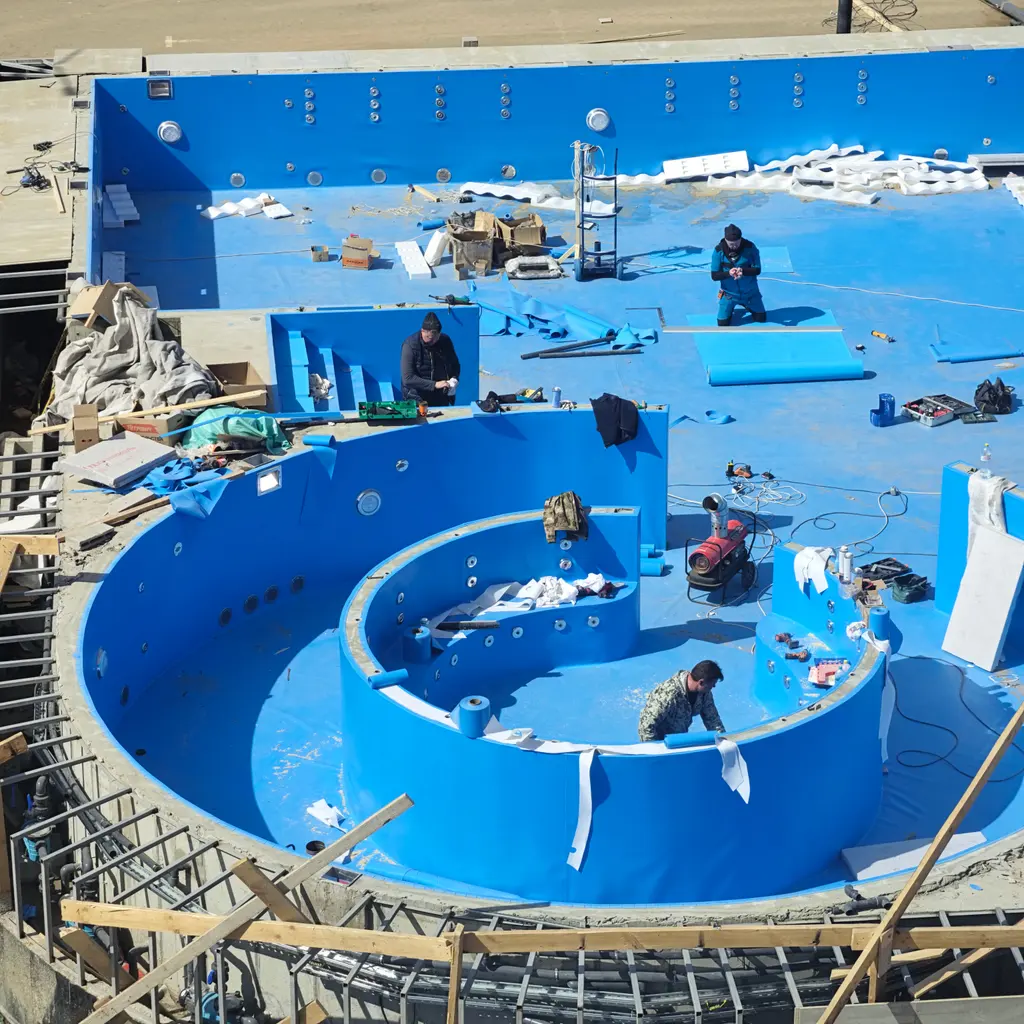
Workers fitting the blue waterproofing and built-in features of an unfinished swimming pool.

Industry overview

Your work involves heavy excavation and complex electrical and plumbing systems, where open pits and water features create significant safety hazards. Even after construction is complete, you may be held responsible for leaks or safety-related accidents if your work is questioned.

The Southern Agency can review your construction and maintenance services to help you select appropriate insurance. For example, we can discuss how builders risk insurance may cover materials and work during construction, separate from the product liability coverage for pool components like pumps and heaters.

Risks worth discussing

Drowning and diving injuries

Drowning or diving injuries can lead to allegations about a builder’s safety features, markings or completed work. The builder’s responsibility depends on its duties and the facts; the pool’s existence alone does not establish liability.

Electrical and bonding defects

Faulty wiring or improper bonding of pumps and lighting around water can cause shock injuries and serious liability.

Excavation cave-ins and falls

Open pool excavations expose workers and visitors to cave-in, fall, and equipment hazards during construction.

Structural and shell defects

Cracking, leaking, or settling of a gunite shell can lead to costly rework and property-damage claims.

Pool chemical handling

Describe chemical products, quantities and storage, transport or service duties. Review any release, injury or cleanup allegations under the relevant terms rather than treating every pool chemical as having the same hazards.

Equipment failure and leaks

Pumps, heaters, and filtration systems can fail or leak, damaging the pool, decking, or surrounding property.

Equipment and tool loss

Excavators, gunite rigs, and tools are valuable and exposed to theft and damage on site and in transit.

Situations to think through

These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.

  1. Hypothetical: Diving injury at a completed pool

    A guest is seriously injured diving into a pool the contractor built, alleging unsafe depth markings. General liability completed-operations coverage may respond, depending on policy terms and the facts.

  2. Hypothetical: Cracked gunite shell

    A pool shell cracks and leaks months after completion, damaging surrounding decking. Review the actual resulting damage separately from correcting the shell and any completed-work exclusions. Construction property coverage may already have ended; it is not automatically a source of payment for a post-completion leak.

  3. Hypothetical: Electrical shock from pool lighting

    Improper bonding leads to a shock injury near pool lighting. General liability may respond to the resulting claim, subject to the specific policy, endorsements, and exclusions.

Before you talk to an agent

What to have ready

Tick items as you gather them. Nothing here is saved or sent.

Questions to raise

  • Allocate excavation, steel, plumbing, gunite, electrical, bonding, and subcontracted duties, including any continuing service.
  • Keep safety-feature, marking, inspection, and owner-handoff records; a barrier or certificate does not establish that every injury allegation is insured.
  • Review completed-work liability and distinguish shell or equipment correction from resulting injury or damage elsewhere.
  • Confirm who insures the pool work and materials, with testing, use, and completion dates, and list excavators, gunite rigs and tools separately.
  • Describe chemical products, quantities, storage, transport and service duties and compare primary and excess exclusions with the actual operations.

What the agent conversation looks like

Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.

  1. ListenReview your operations, current coverage, and past claims.
  2. AssessIdentify potential hazards and discuss ways to reduce risk.
  3. BuildDiscuss policy and carrier options, premium costs, and audits.
  4. SupportReview changes and help you plan ahead as your needs develop.

Questions owners ask

What insurance does a swimming pool contractor need?

Review the trades you perform, employee injuries, vehicles and mobile equipment, then identify who insures the pool work during construction. Service, chemicals and supplied products need disclosure too. Construction property coverage, liability and a requested excess limit address different interests.

Is drowning liability covered after the pool is finished?

General liability may address a covered allegation that your completed work contributed to an injury. Review the actual safety-feature, marking or other duty alleged, relevant dates and pool-related exclusions. The pool’s existence or an accident after handoff does not itself establish builder liability or payment.

Why are umbrella limits important for pool builders?

A serious injury can create a large liability demand. Compare the exposure and written project requirements with the policies and exclusions the excess layer follows. Higher limits do not turn an excluded pool operation or warranty obligation into covered liability.

How is my excavation and gunite equipment insured?

Inland marine commonly covers excavators, gunite rigs, and tools against theft and damage on site and in transit, subject to scheduled values and policy terms.

Are pool chemicals an insurance concern?

Disclose the chemical products, storage, quantities, transport, and service duties. Review injury, property and pollution terms separately; a truck policy or liability limit does not automatically insure every drum, release or cleanup expense.

What if a pump or heater I installed fails?

Separate replacing the failed pump or heater from injury or damage it caused elsewhere. Review the product supplied, installation duties, relevant dates and products and completed-operations exclusions. Product liability is not an automatic equipment warranty.

Talk through your swimming pool contractor coverage

Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.

How can we help you get started?

Choose the quote that fits, and we’ll take it from there.

Have a question? Contact us