

Defective pour and rework
Errors in mix, grade, reinforcement, or finishing can be costly to correct once concrete sets, leading to workmanship claims.
Try a different word, or check the spelling.
You have a limited working window once the concrete arrives. Coverage for your placement equipment and resulting property damage needs to be understood separately from the cost of redoing a poor pour.
Tell us about your structural and flatwork jobs, crew payroll and owned or rented placement equipment.
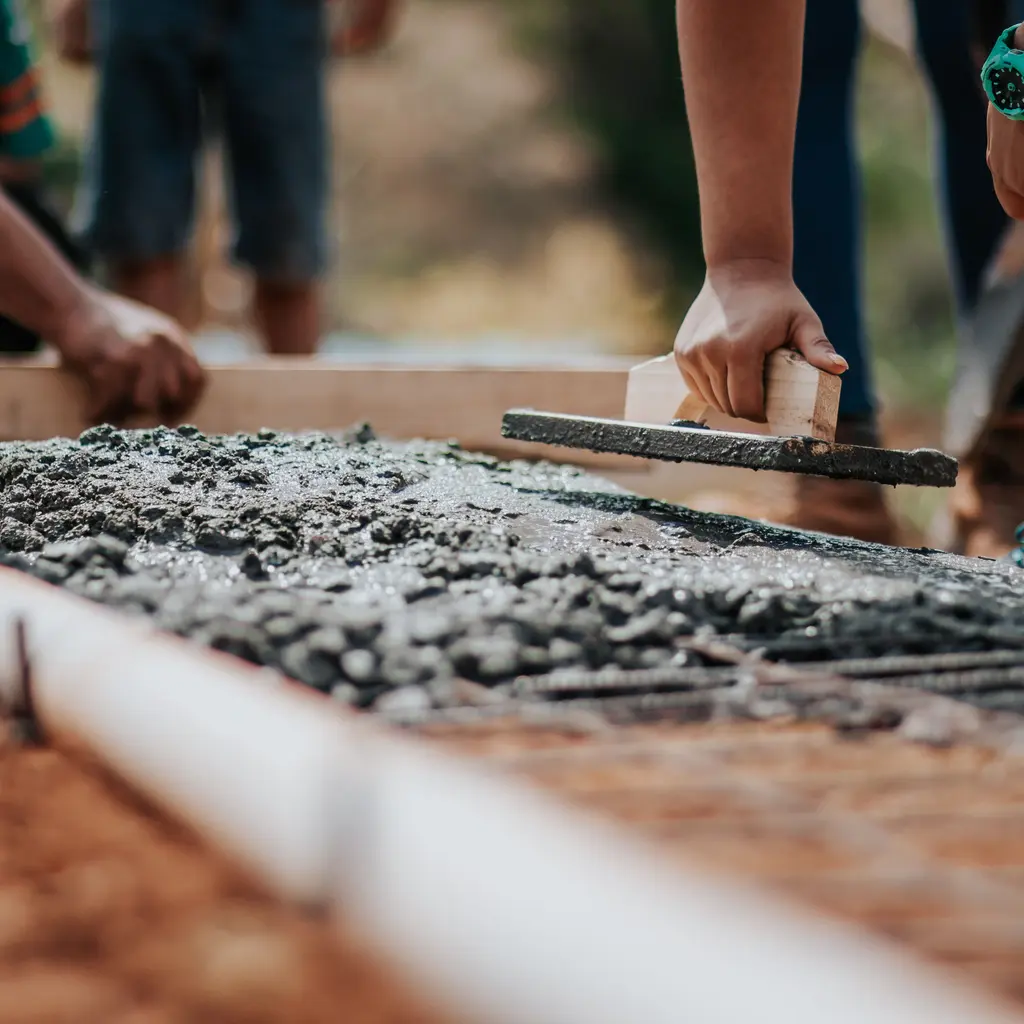
You pour and finish concrete foundations and slabs, which requires precise timing and heavy machinery. A stopped pump during a pour or a cracked slab after completion can cause expensive delays and repair costs that require careful insurance planning.
The Southern Agency can review your concrete operations and equipment use to help you select appropriate insurance. For example, we can help you distinguish between coverage for third-party damage caused by your work and the separate costs associated with repairing a defective concrete pour.
Errors in mix, grade, reinforcement, or finishing can be costly to correct once concrete sets, leading to workmanship claims.
A foundation or slab that later cracks, settles, or fails can produce completed-operations and property-damage claims.
Wet concrete is caustic, exposing crews to chemical burns and skin damage during placement and finishing.
Setting forms, placing rebar, and moving screeds expose workers to lifting, crush, and back injuries.
Pumps and moving placement equipment bring struck-by and contact hazards. Cutting or demolishing concrete can release respirable silica; disclose actual tasks and controls rather than treat every machine or finishing step as the same dust exposure.
Pumping, pouring, and equipment movement can damage neighboring surfaces, landscaping, or buried utilities.
Pumps, trowels, and forming equipment moving between sites are exposed to breakdown, damage, and theft.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a commercial slab develops cracks and the owner alleges defective work. GL may address covered defense and resulting injury or property-damage claims under actual completed-operations terms. Establish whether there is separate harm; correcting the slab alone or removing and repouring it is a separate cost, not an automatic warranty payment.
Hypothetical: a finisher suffers chemical burns from prolonged contact with wet concrete. Workers' compensation may provide qualifying medical and wage benefits under applicable law. Identify the actual employer and duties; an injury to another contractor's worker requires separate liability review.
Hypothetical: a pump motor fails halfway through a commercial slab pour. Equipment breakdown may help repair it if the machine and cause qualify. Spoiled concrete, replacement pump hire and idle-crew wages need separate review before you count on reimbursement.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
GL may address covered defense and resulting injury or property-damage claims under actual completed-operations terms. Correcting defective concrete alone differs from harm to other property. Keep work, handoff and damage dates and review exclusions and governing law; a workmanship allegation does not automatically insure removing and repouring the slab.
Applicable law, payroll classifications, actual duties, and loss history matter. Disclose burns, lifting, silica controls, excavation, and elevated work rather than assume one concrete classification covers every service or always has a particular price.
Inland marine may help with covered theft or damage to insured pumps, trowels, vibrators, and forms at sites or in transit. Check values, rentals, storage and causes. Equipment physical damage, internal breakdown and spoiled materials are separate questions; one schedule does not establish all three.
Breakdown terms may help with covered repairs if the actual mobile pump and internal failure qualify. Establish the cause and review eligibility, schedules, and restrictions before counting on payment. Spoiled mix, cleanup, replacement hire, income and delay costs each need separate terms; neither an equipment schedule nor an insured repair includes every stopped-pour consequence.
Many contracts set liability, auto, workers' compensation and excess requirements. Compare the contract with actual policies and endorsements before mobilizing; a certificate alone does not expand coverage.
Underwriters assess structural versus flatwork scope, payroll, owned and rented equipment, vehicles, safety practices, contracts, and claims. The actual submission and insurer determine eligibility and price.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.