

Refrigeration failure and inventory thaw
A freezer, compressor, or power failure can thaw and spoil large volumes of high-value seasonal frozen fruit held to supply year-round demand.
Try a different word, or check the spelling.
Your harvest-season stock may have to supply customers long after fresh fruit stops arriving. Cold-storage values, breakdown and spoilage protection deserve attention beyond the price of repairing a freezer tunnel.
The Southern Agency can help you coordinate cold-chain, property, and product coverage based on your specific freezing and storage exposures.
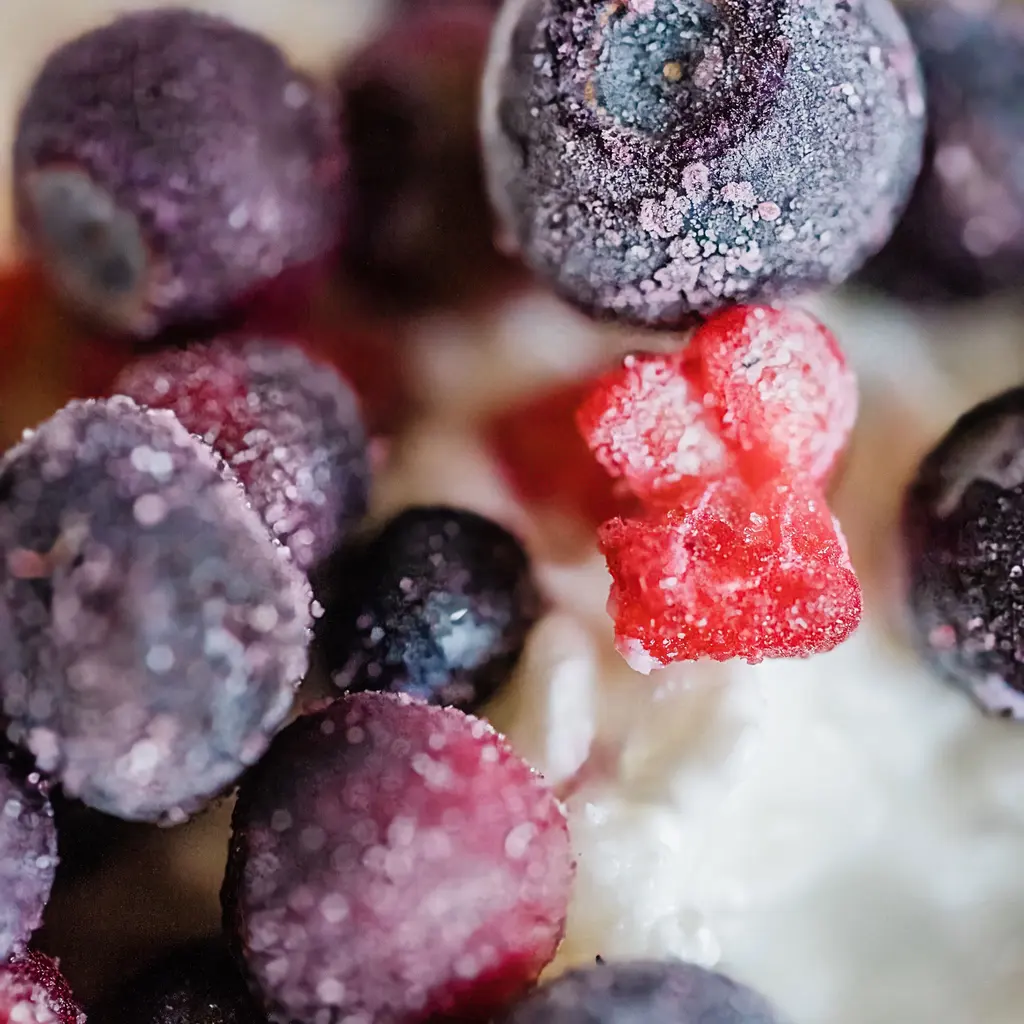
You process seasonal fruit using blast freezers and packing lines to supply grocers and food services year-round. A refrigeration failure or a contamination event can spoil your high-value inventory and threaten your production schedule.
The Southern Agency can help you review your cold-chain dependencies and sanitation processes to choose appropriate insurance, such as equipment breakdown protection to cover the cost of a failed freezer tunnel.
A freezer, compressor, or power failure can thaw and spoil large volumes of high-value seasonal frozen fruit held to supply year-round demand.
Because frozen fruit is often eaten raw, pathogens surviving inadequate sanitation can lead to recalls and illness claims.
Blast freezers, IQF tunnels, and refrigeration systems are costly and production-critical, and a failure can idle the plant and spoil product.
Plants using ammonia refrigeration face chemical-release exposure that can harm workers and the environment and trigger regulatory response.
Heavy harvest-season stockpiling concentrates value in cold storage, magnifying losses from any cold-chain or warehouse event.
Freezing temperatures, wet floors, and packing machinery expose employees to slip, cold-stress, and machinery injuries.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A blast freezer fails during peak season, thawing pallets of berries. Equipment breakdown and business income coverage may respond to spoilage and lost output, depending on policy terms and exclusions. Confirm covered freezer event, stock/income inclusion, and seasonal valuation; thawed stock alone does not establish every expense.
Testing detects Listeria in a frozen-berry lot and shipped packs are recalled. An eligible recall form may help with included collection, disposal or other purchased expenses, subject to its event and consent terms. Product liability concerns covered illness or other harm; a positive test without such a claim does not turn retrieval and replacement into liability damages. Freezing alone does not remove the pathogen concern.
An ammonia refrigeration line leaks, prompting evacuation and cleanup. Environmental liability coverage may respond to remediation and third-party claims, depending on policy terms and facts. Review insured release/location, cleanup/reporting, and exclusions; worker benefits/fines are separate.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Harvest-season stockpiling concentrates high inventory values in cold storage. Property and business income limits should reflect those peaks so a cold-chain loss is not underinsured, subject to policy terms.
Review intended raw consumption, controls, and affected fruit lots. Products liability concerns covered harm to others, not automatically withdrawal. Recall/contamination cover needs an eligible event, insured product and purchased expenses; quality rejection, refunds, rework and routine spoilage are not automatic cover.
Equipment breakdown coverage may respond when freezers or refrigeration systems fail, helping with spoilage and repair, and business income may address lost output, depending on policy terms.
Ammonia releases create chemical and environmental exposure standard liability often excludes. Environmental liability may respond to cleanup and claims, subject to policy terms and the facts.
Retailers and manufacturers commonly require product liability and indemnity. We can help align limits with those contracts, though availability depends on underwriting and operations.
Freezing temperatures, slick floors, and packing machinery drive slip, cold-stress, and machinery injuries. Workers' compensation is commonly required and often legally mandated, subject to state rules.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.