

Customer slip-and-fall claims
Customer traffic across aisles, produce misting areas, entrances, and parking lots creates slip-and-fall exposure.
Try a different word, or check the spelling.
Your shared refrigeration can support several departments, while a deli or bakery adds food-preparation duties to retail sales. Equipment, stock and liability protection need to fit those departments without assuming a package includes any pharmacy or fuel operation.
The Southern Agency can help you review your actual departments and shared cooling, property, food and data responsibilities without assuming one package includes every activity.
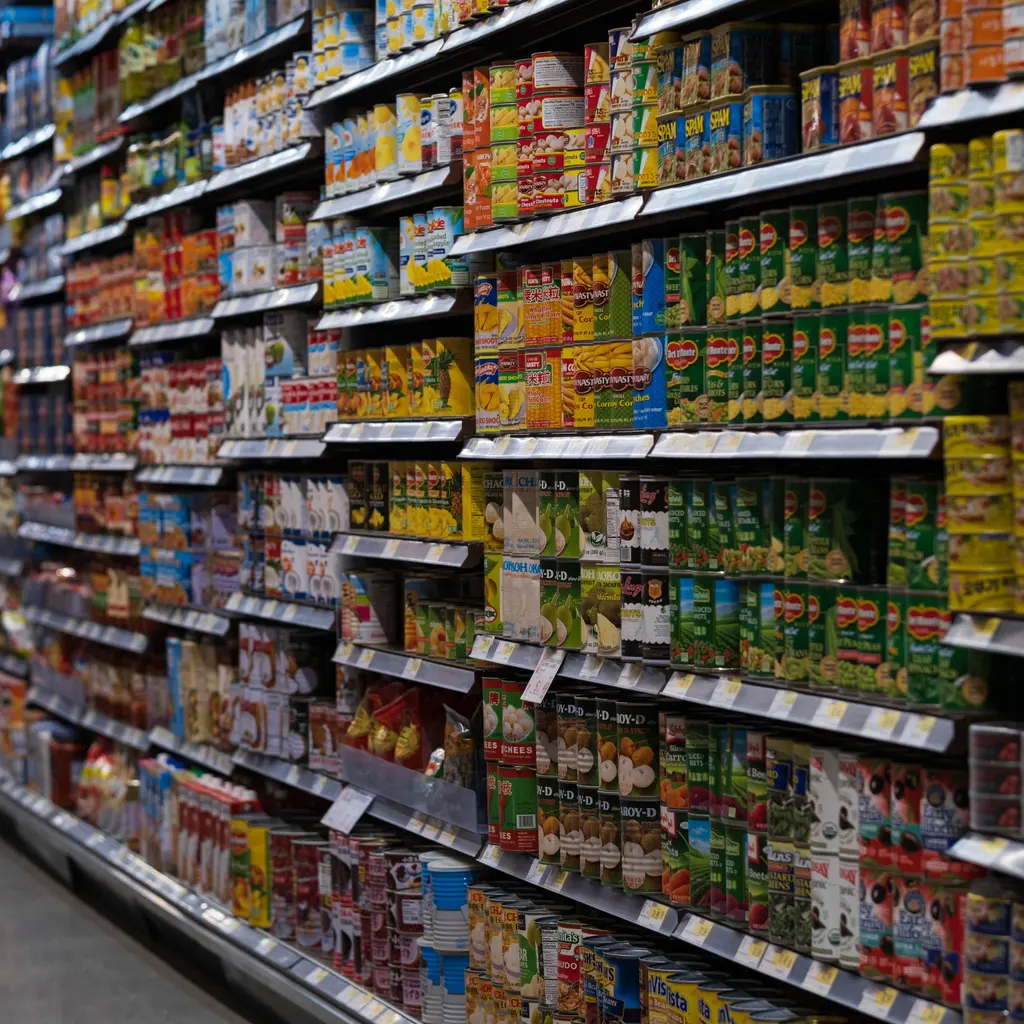
You manage a high-volume retail space with multiple departments like delis or bakeries. A refrigeration outage can spoil vast amounts of stock, while high customer foot traffic increases the chance of a slip-and-fall claim.
The Southern Agency can review your store's layout, departments, and operations to help select insurance, such as equipment breakdown for your cooling systems or liability for shopper safety.
Customer traffic across aisles, produce misting areas, entrances, and parking lots creates slip-and-fall exposure.
Power outages or refrigeration failures can spoil enormous volumes of perishable produce, dairy, meat, and frozen goods.
Delis, bakeries, hot bars, and salad stations create foodborne-illness and allergen exposure across prepared items.
Refrigeration, HVAC, and compressors are critical, and a breakdown can disrupt operations and spoil inventory storewide.
Stocking, lifting, balers, and forklifts expose staff to strains and serious injuries driving workers' compensation costs.
High transaction volume and loyalty programs mean stores handle substantial payment and personal data, raising breach risk.
A fire, storm, or extended outage can close a large store and halt revenue across every department at once.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A compressor failure over a holiday weekend spoils frozen and dairy inventory across multiple aisles. Equipment breakdown coverage may help with the loss and repairs, depending on policy terms and exclusions. Check covered compressor/utility cause and included stock by connected system, peak value, and time limits.
A shopper slips on water near a misting display and is injured. General liability coverage may respond to medical and liability costs, depending on policy terms and the facts. Review actual misting/floor responsibility, injury facts, and premises terms.
Several customers report illness traced to a prepared deli item. A policy may respond to product liability claims, subject to the specific policy, endorsements, and the facts involved. Separate covered food harm from supplier withdrawal, disposal, refunds, or authority closure; each has different triggers.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Review property, general liability, equipment breakdown, product liability, workers' compensation, and cyber coverage against the departments actually operated. Check package eligibility and included coverages; a multi-department store label does not establish fit.
Equipment breakdown and spoilage coverage may help when refrigeration fails, depending on policy terms. Limits should reflect the deep perishable inventory a supermarket holds.
Preparing deli, bakery, and hot-bar items adds foodborne-illness and allergen exposure, so product liability is commonly needed, subject to policy terms.
High transaction and loyalty-data volume creates breach exposure. Cyber coverage may help with breach response and liability if systems are compromised, depending on the specific policy.
Business income coverage may respond when a covered loss forces the store to close, helping with lost revenue. Coverage depends on the specific policy and exclusions.
General liability commonly responds to customer injuries in store-controlled parking areas, though terms vary. Coverage depends on policy terms and underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.