

High-value inventory theft
Premium leather, branded hardware, and finished designer bags concentrate value that is attractive to burglary and employee theft.
Try a different word, or check the spelling.
Your sample line may be with a showroom, buyer or trade event while sale stock stays at the workshop. Portable-stock and crime protection need to follow the actual ownership and custody, separately from replacing a defective bag.
The Southern Agency can help you review leather stock, finished bags, and samples traveling to buyers.
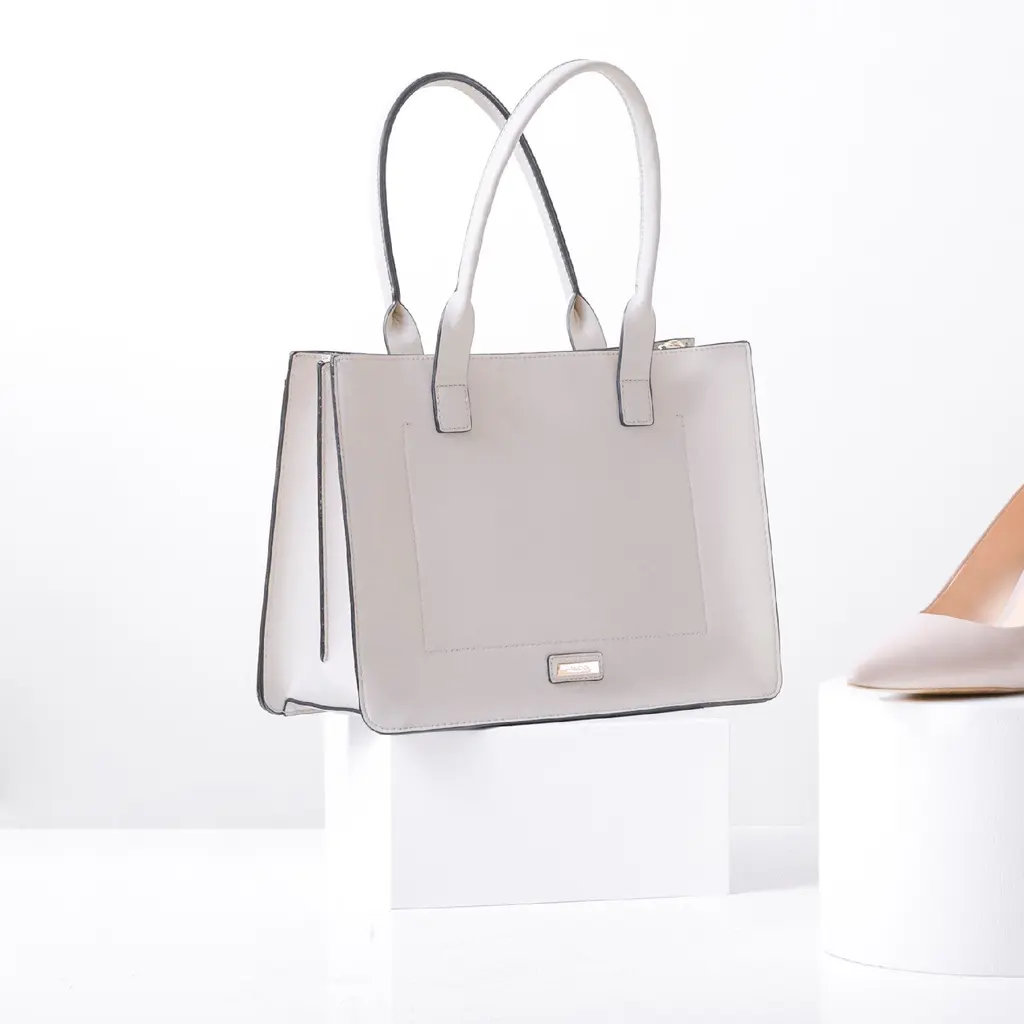
You cut, stitch and assemble handbags from leather, canvas or other materials, often for a brand or boutique order. Valuable hides and finished bags can concentrate in your workshop, while a failed strap or clasp can injure a customer after the bag is sold.
The Southern Agency can help you evaluate your workshop operations and inventory to help select insurance that reflects the value of your materials and finished goods. We can discuss how your policy protects against inventory theft or transit losses and addresses potential product liability.
Premium leather, branded hardware, and finished designer bags concentrate value that is attractive to burglary and employee theft.
Failed strap hardware, detaching small parts, or dye reactions on a carried product can lead to liability claims and retailer chargebacks.
Cutting knives, edge tools, and stitching machines expose staff to lacerations and repetitive-strain injuries during assembly.
Fire, smoke, or water can ruin leather hides, fabric rolls, and finished bags stored in the workshop.
Brands and retailers frequently require liability limits, additional insured status, and indemnity terms before stocking the bags.
Sample lines and orders moving to showrooms, buyers, or trade events can be lost, damaged, or stolen away from the premises.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Thieves break in and take finished designer bags and a stock of branded hardware. Property or purchased crime cover may respond, depending on the policy, endorsements, and exclusions. Distinguish burglary from employee loss and check stock ownership, proof, covered causes, valuation, and limits under each form. Branded retail or missing-stock value is not automatically payable.
A clasp fails and a customer reports an injury when a bag drops. Product liability may respond, depending on the policy and facts. Check the clasp, design and use included and alleged injury separately from replacing the bag, contract chargebacks, and withdrawal. Returned lines and recall costs need separate review.
A sample line is lost in transit to a buyer showcase. Inland marine may help with goods away from the premises, subject to the policy. Check sample ownership, carrier and event stages, cause, proof, valuation, and limits. Displaying the line does not insure every showcase, full retail price, or anticipated sales.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Leather, branded hardware, and finished bags can concentrate value. Document actual ownership, cost, and peak inventory, then compare valuation, covered causes, and limits. Workshop size or a designer label alone does not set insured value or guarantee retail-price payment.
Inland marine may help protect samples and orders in transit and away from the premises, where standard property forms often do not respond, depending on the policy.
Yes. Failed hardware or detaching parts on a carried product can support injury claims. Product liability may respond, subject to policy terms, endorsements, and exclusions.
Document owners, values and security, distinguishing burglary, employee theft and unexplained shortages with cause, proof, discovery, and reporting records. Compare property and crime terms, limits, and valuation. A designer label or discrepancy alone does not insure every missing item or full retail amount.
Read brand or retailer limits, insured entities, additional-insured endorsements, indemnity, and return or withdrawal duties. Compare issued terms. Certificates and contracts do not amend policies or guarantee every insured status, chargeback, design or intellectual-property claim or recall benefit.
Workers' compensation commonly responds to medical costs and lost wages from cutting and stitching injuries, subject to policy terms and applicable state law.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.