

Kiln fire and burns
Gas and electric firing creates hot surfaces and fire or ventilation hazards for staff, students, and members with kiln access.
Try a different word, or check the spelling.
Your kiln may hold a student's work beside your sale inventory, with different owners and processing interests. Property and class liability need to fit that arrangement; ordinary firing cracks, a waiver or a canceled class do not establish coverage.
The Southern Agency can review your actual kiln access, classes and ware ownership with you, alongside the property and liability terms offered.
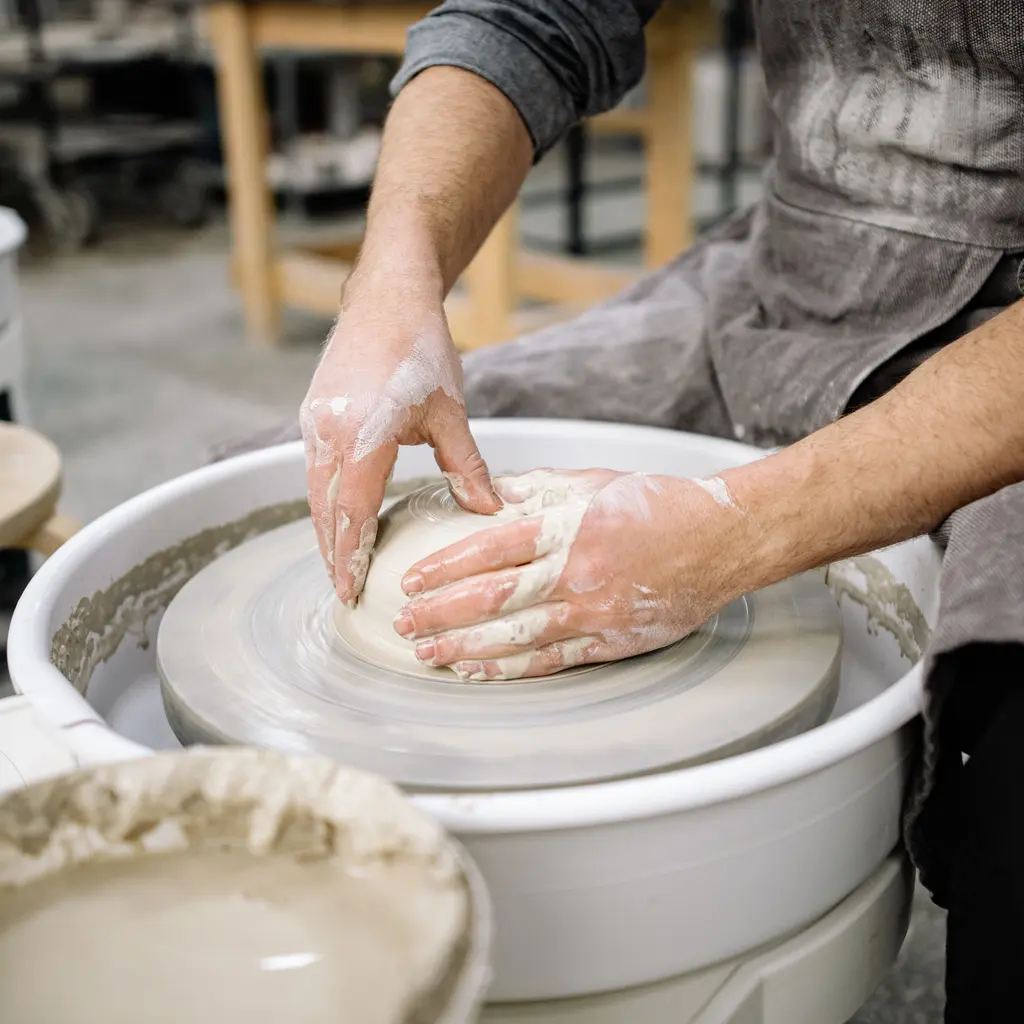
You shape, glaze and fire ceramic pieces, with sales or teaching where your studio offers them. Kiln heat, clay dust and actual glaze ingredients create different worker and property risks, while students and food-use ware bring their own injury questions.
The Southern Agency can review your teaching activities, kiln usage, and product sales to help you select appropriate insurance. For example, we can help you determine how to cover student-made pieces versus your own inventory in the event of a kiln fire.
Gas and electric firing creates hot surfaces and fire or ventilation hazards for staff, students, and members with kiln access.
Classes and open studio bring visitors near tools, heavy clay and equipment, creating slip, cut, and burn exposures.
Identify silica and other ingredients, including lead where present, and the dust or chemical tasks performed. Not all glazes contain the same substances.
A glaze that leaches or a piece that fails can prompt injury allegations. Failed tests, replacing pieces, and refunds are separate questions.
A fire can affect kilns, wheels, greenware, and finished stock together. Student or customer pieces and ordinary firing damage require their own ownership and processing review.
Controller, element or wheel problems can disrupt firing and classes. Distinguish covered internal damage from wear, routine servicing, and process errors.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A class participant touches a hot kiln and suffers a burn requiring treatment. Review the teaching and kiln-access activities insured, student injury, and medical-payment terms and applicable exclusions. Class registration alone does not establish insurance.
A customer claims a mug represented for food use leached after repeated use. Establish what allegedly leached and any injury or damage to other property. A complaint or failed food-use test alone does not establish product-liability payment for replacing the mug, refunds, testing, or withdrawal.
A kiln malfunction ignites nearby shelving and damages inventory. Review covered property fire terms and the owned or entrusted ware involved. The equipment fault, student pieces, ordinary firing cracks and any purchased income benefits require separate cause, ownership, and coverage review.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Describe the teaching, tools, student, and member access and who operates kilns. Check those activities and instruction or professional-services restrictions in the terms offered. Have qualified advisers review participant agreements too; waivers are not insurance.
Declare the decorative or food-use ware and representations made, and obtain qualified material, firing, and testing advice. Injury or damage to other property differs from a failed test, replacing pieces, refunds, and withdrawal. A product policy is not food-safety certification.
Identify covered internal controller or equipment damage and the stock and income terms purchased. Worn elements, routine replacement, firing errors, and canceled classes alone do not establish payment. Separate any covered fire damage from the equipment cause and your own or customer ware involved.
Describe clay and glaze ingredients and dust, mixing, cleaning, and firing duties to qualified advisers. Review worker status, jurisdiction and qualifying occupational-injury benefits. Ventilation and other controls do not guarantee favorable insurance terms or every illness payment.
Check eligibility for production, sales, teaching, open studio and gas or electric kiln use, then the property and liability parts and limits offered. Small size alone does not add student property, firing breakage, internal breakdown or every class-related claim.
Kiln count, class activity, glaze chemistry, equipment, and inventory value, and claims history all factor in. Coverage availability depends on underwriting.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.