

Shared-space injuries
Curbs, spills, weather, and crowded events can lead to injury allegations. Security and maintenance contractors do not remove all operator responsibility.
Try a different word, or check the spelling.
Hiring a maintenance or security contractor does not remove every responsibility you retain for the shared areas. Your center's liability and property protection should fit those contracts and facilities, with rental values, system repairs, and tenant disputes kept distinct from employee claims.
Bring the building schedule, shared-system responsibilities and tenant leases, with rental values and actual maintenance or security contracts.
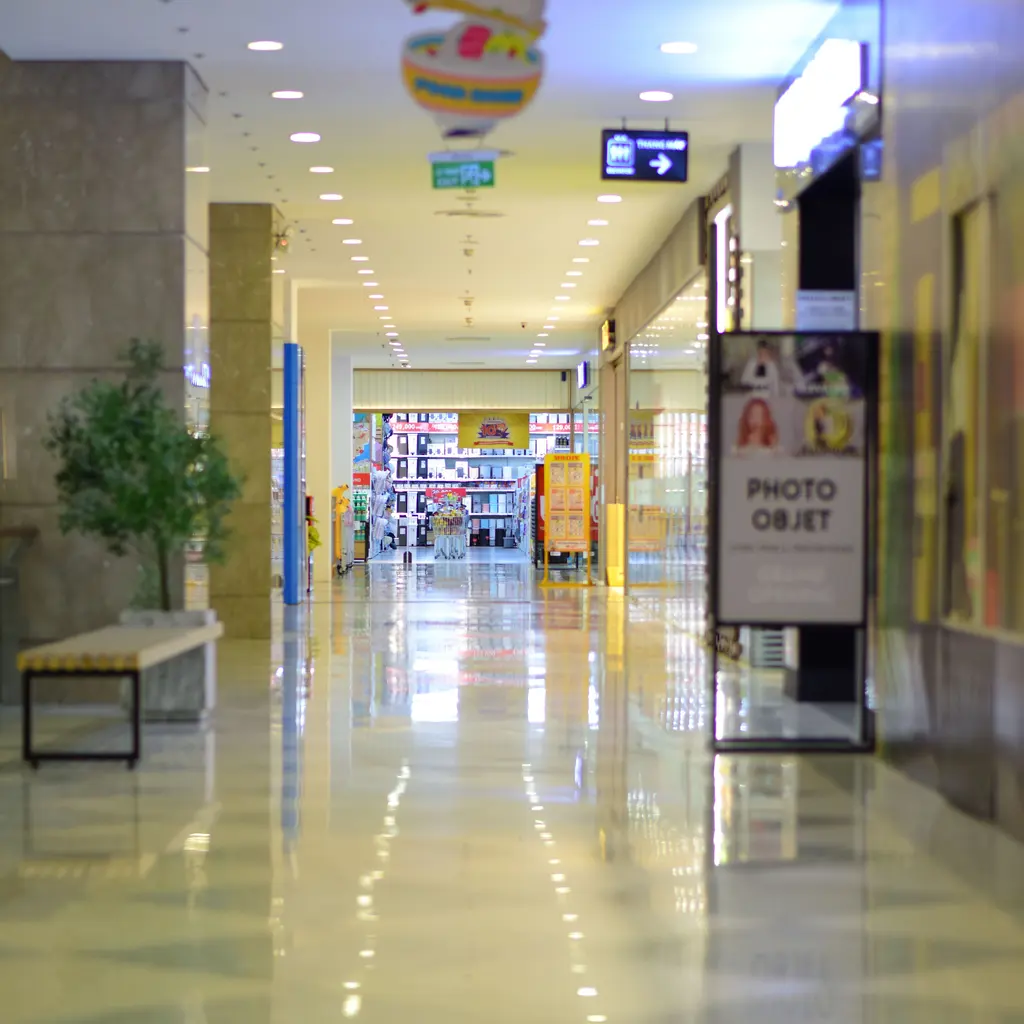
You manage common areas and lease space to retail tenants, ensuring walkways, parking, and restrooms remain functional. A roof leak or a shopper's fall in an open area can implicate your business in costly building repairs or liability claims.
The Southern Agency can review your building responsibilities, shared facilities, and contractor requirements to help you select appropriate insurance. We can discuss how premises liability covers your common areas while property and rental-income coverage help during building losses.
Curbs, spills, weather, and crowded events can lead to injury allegations. Security and maintenance contractors do not remove all operator responsibility.
A single storm can affect multiple structures. Repair costs and lost rental income need their own values and coverage triggers.
Shared HVAC or escalators can fail. Employee injury and employment allegations concern different policies from tenant disputes.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A visitor alleges a damaged curb caused an injury. General liability may address a covered claim; the operator/contractor responsibility and incident facts matter.
Wind could damage canopies and roofs across several tenant buildings. Review the covered cause, scheduled structures and outdoor property, applicable deductibles and repair limits. Lost rent needs included rental-value terms and its actual qualifying interruption, calculation and restoration period; damaged roofs alone do not establish every tenant's unpaid rent.
If the center has an escalator, a mechanical failure could damage it and injure a shopper. Accepted breakdown terms may help with covered equipment costs; liability terms separately address a covered injury allegation. Maintenance duties, contractor arrangements and the actual cause matter, and repairing the system does not settle liability for the shopper.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Only if its policy includes that property interest. Leases and tenant policies need separate review.
No. Rental-value terms depend on covered damage, timing, limits, and the lease-related loss calculation.
No. The actual contract, endorsements, and facts determine responsibility and available cover.
Not merely because a manager handled it. The type of allegation determines the relevant policy.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.