

Falls during fittings
A shopper can trip over an open box or fall when stepping off a fitting stool. The condition of the fitting area and the assistance provided matter when assessing an injury claim.
Try a different word, or check the spelling.
Losing part of a size run can leave intact shoes harder to sell without making all remaining stock a covered loss. Your footwear valuation and income terms need that distinction, alongside fitting assistance, online orders, and evidence for any missing pairs.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
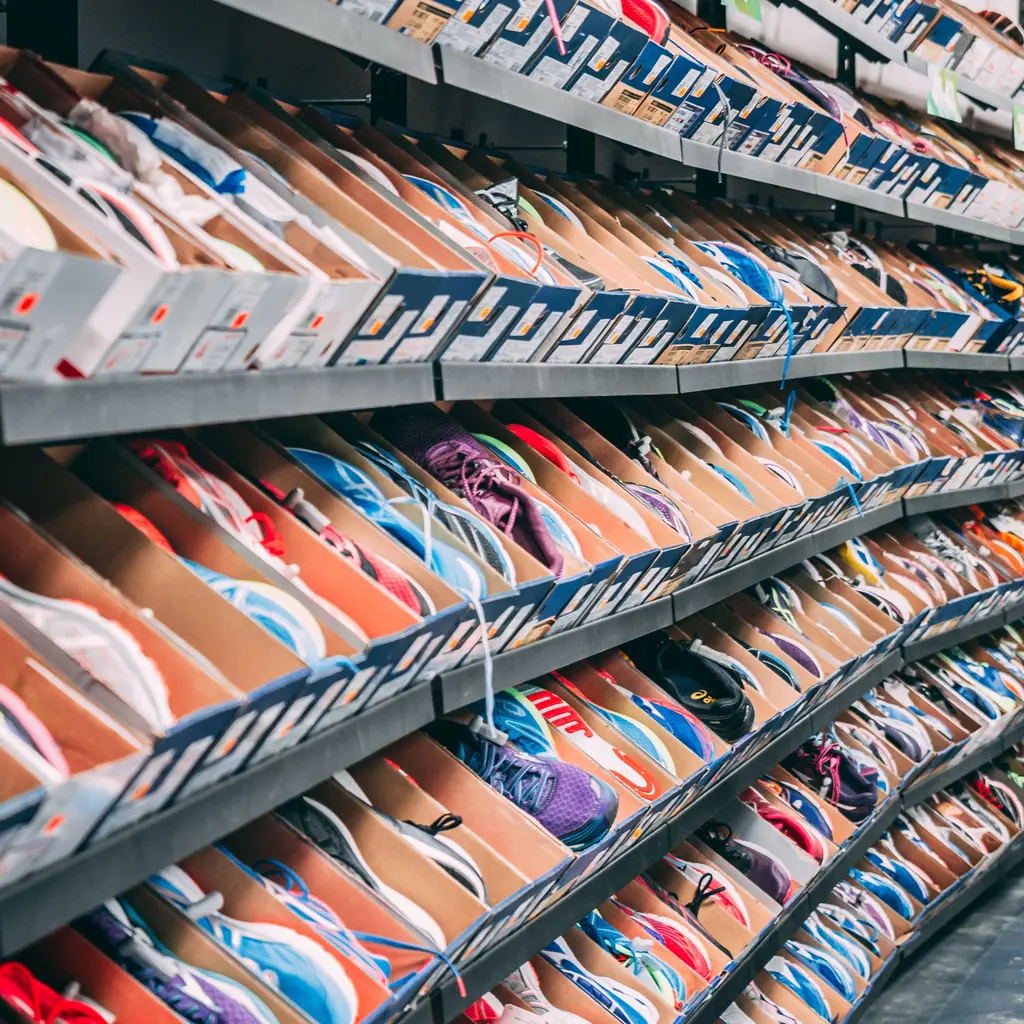
You manage stockroom inventory, assist customers with fittings and fulfill online orders. A fall in your fitting area or damage to your stored stock can interrupt your business and lead to unexpected expenses.
The Southern Agency can review your fitting-area layout, stockroom and sales channels with you. We can compare accepted customer injury and product claims with stock causes, peak size-run values and any purchased qualifying income, alongside staff and customer-data duties.
A shopper can trip over an open box or fall when stepping off a fitting stool. The condition of the fitting area and the assistance provided matter when assessing an injury claim.
A sprinkler discharge can soak boxed shoes across several sizes and styles. Losing only part of a size run can disrupt sales, but a policy's valuation terms determine what is paid for damaged and remaining stock.
Associates carry boxes, reach for shelves, and use stockroom ladders. Falls and repeated lifting can cause employee injuries even when individual boxes are light.
A store may hold addresses, order histories, and payment-related information through its own systems or vendors. A return policy or payment processor does not remove the need to understand who handles the data.
An alleged sole failure can produce a product injury claim against the seller. A stock discrepancy is a different problem: an unexplained shortage does not establish an insured theft.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
An open shoe box catches a customer's foot and the customer seeks payment for an injury. General liability may help defend the store and pay covered damages. Separate medical-payments coverage, if present, has its own conditions; an injury alone does not establish the store's liability.
An accidental sprinkler discharge damages boxed inventory overnight. Property insurance may pay for covered stock damage, subject to valuation and deductibles. Lost sales require an applicable business-income provision and a qualifying interruption, not just a damaged shipment.
An employee falls while retrieving a size from an upper shelf. Workers compensation may help with eligible medical care and wage benefits. The worker's status and applicable state rules matter; general liability is not the employee-benefit policy.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Start with the value of stock at its busiest point, including goods awaiting returns processing. Ask how the policy values damaged merchandise and handles seasonal increases. Retail selling price is not automatically the insured value.
A decline in demand or a markdown is a business loss, not by itself covered physical damage. Fire-damaged inventory and slow-moving stock need separate treatment.
The store can be named even if it did not manufacture the shoe. Products-completed operations may address a covered injury claim, but refunds, replacement pairs, and recalls have different terms.
A data incident involving return records may fall within cyber coverage. The cost of accepting worn shoes or issuing an ordinary refund is not a breach-response expense.
A certificate can provide evidence, but compare the actual policy and endorsements with the lease. Required limits and insured status must be confirmed rather than inferred from a certificate.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.