

Stock and selling windows
Small seasonal runs can be difficult to replace after damage. Insurance valuation and income terms determine payment, not the collection's expected retail revenue.
Try a different word, or check the spelling.
Taking a small collection to a pop-up changes the stock's location and the host's insurance requests, not just your selling space. Your property and event protection need that move accepted, with seasonal valuation and ordinary markdowns distinguished from insured damage or lost income.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
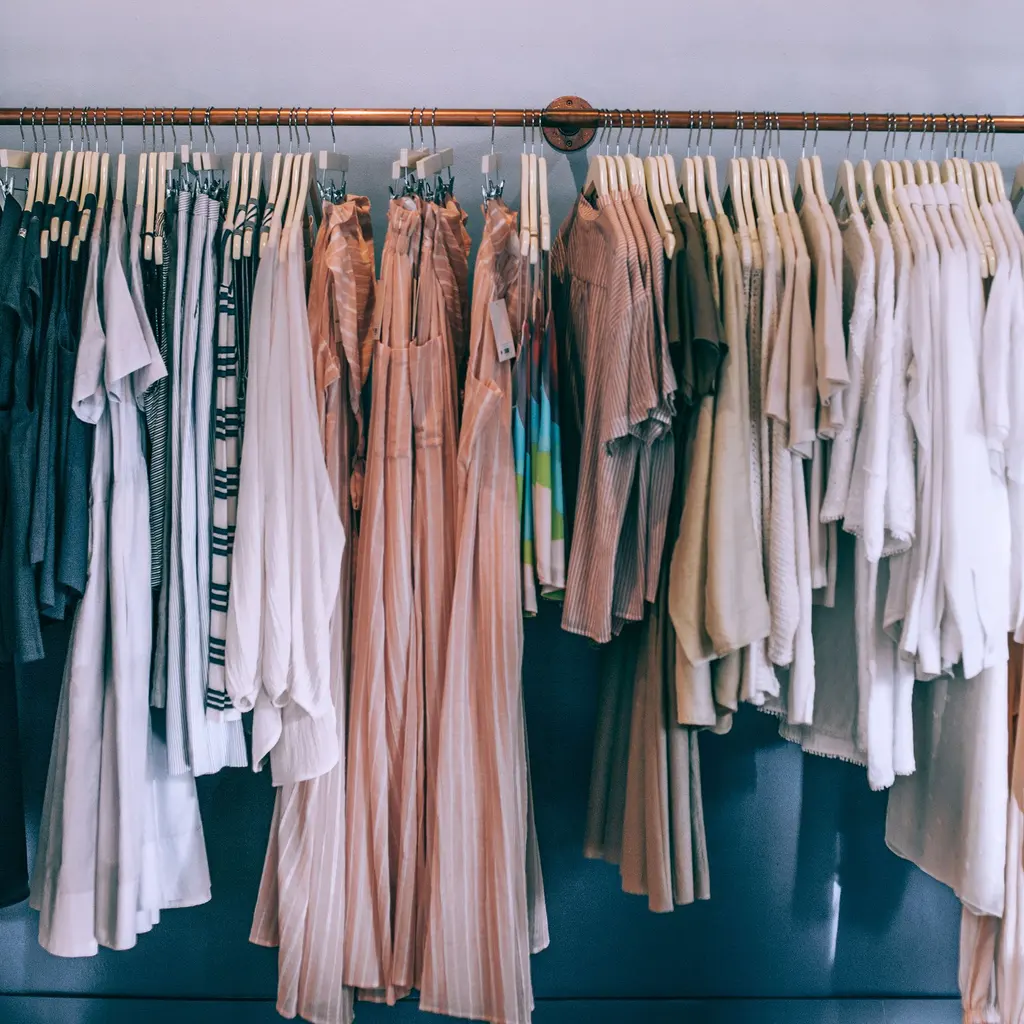
You sell changing collections of clothing and accessories, perhaps through a storefront, web shop, or pop-up event. A leak can ruin a new collection, while taking stock off-site can move it beyond the locations listed in a standard property policy.
The Southern Agency can review your sales channels and seasonal stock to help you choose insurance. We can discuss property protection for the main shop and any accepted off-site stock, alongside liability and customer-data needs.
Small seasonal runs can be difficult to replace after damage. Insurance valuation and income terms determine payment, not the collection's expected retail revenue.
Mirrors, displays, and changing-room traffic create injury potential. Pop-ups add new locations and host requirements.
Missing inventory needs an identifiable insured cause. Restocking and event setup can injure staff, while social and online selling involve customer data and vendors.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Merchandise is damaged at a trunk show. Applicable off-site property cover may pay an insured loss if the location and goods fit; store-only terms may not.
A display mirror falls and injures a customer. General liability may address covered defense and damages; medical payments, if present, have separate conditions.
Unauthorized access exposes webstore customer records. Cyber may address covered response and liability costs, subject to vendor definitions, consent, and reporting terms.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Poor demand alone is not covered physical damage. Damaged-stock valuation and business-income claims have separate terms.
Not automatically. Check temporary locations, transit, and liability provisions before an event.
No. Identify the information and systems the boutique and vendors handle, then review relevant cyber terms.
Employee injuries need workers compensation review based on duties, employment arrangements, and state rules.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.