

Incubator power and climate failure
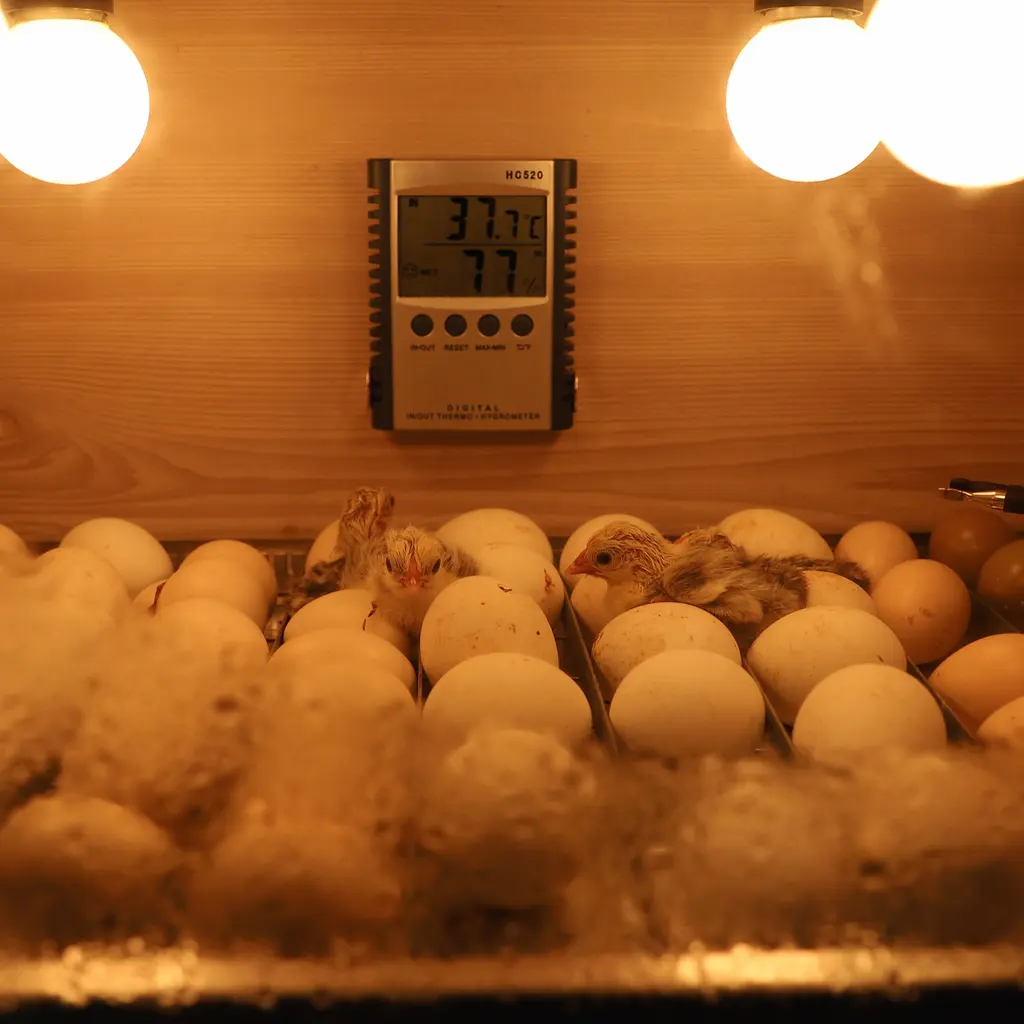
An outage or control failure can affect multiple batches of developing eggs. Outcome depends on actual species, stage, conditions, duration, and backup response.
Try a different word, or check the spelling.
Your incubators hold developing batches, while customers are waiting for day-old birds. Coverage needs to distinguish the equipment, the living value inside and what happens during shipment.
The Southern Agency can review your incubation and dispatch arrangements to compare equipment, egg or bird loss and shipment terms.
You run a hatchery focused on incubating fertile eggs and supplying day-old birds to customers. Managing incubation stages, bio-security, and live shipments presents specialized risks distinct from standard property insurance.
The Southern Agency can review your hatchery infrastructure, incubation controls, and delivery processes to help you select appropriate insurance. For example, we can help clarify the difference between coverage for an incubator's failure and the separate protection needed for the livestock itself.
An outage or control failure can affect multiple batches of developing eggs. Outcome depends on actual species, stage, conditions, duration, and backup response.
Contaminated eggs or facility pathogens can lower hatch rates, spread to customers, and prompt regulatory and product concerns.
Chicks shipped by mail or delivery can arrive dead or weakened. Own-shipment loss, delay, replacement promises, and injury or damage to others need separate review.
An official disease response may restrict movement or involve destruction of birds or eggs. Affected operations, stock interests and assistance eligibility depend on the actual event and program.
Incubators, hatchers, ventilation, and backup power have connected dependencies. A machine fault, affected eggs, and live-bird loss may involve different coverage terms.
Fire, storm, or cooler failure can damage the facility, egg inventory, and the systems hatching depends on.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a storm interrupts power and backup does not supply incubators. Applicable terms may address eligible machine or utility damage and selected resulting loss. Establish the cause, actual backup response, egg/bird stage, and ownership; loss of hatch, live birds, and interrupted orders are not established by machine coverage alone.
Hypothetical: a delayed chick shipment arrives with dead birds and the buyer requests replacement. Review actual cargo/live-stock interests, cause, carrier, and sale terms. Product liability for injury or damage to others does not by itself establish payment for the hatchery's dead shipment, refund or arrival guarantee.
Hypothetical: a cooler compressor fails while fertile eggs await setting. Applicable breakdown terms may address eligible repair and selected resulting stock loss. Compare actual egg condition, ownership, cause, utility/wear, valuation, and stock limits; reduced viability or later hatch rate is not automatically insured spoilage.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Not automatically. Confirm eligible machinery, cause, wear, utility, and backup conditions, then actual egg/bird stages, ownership, and valuation. Machine repair, viability, live-bird loss, disposal, and income can have different terms.
A shipment's death, delay, refund, or replacement promise is not established by third-party injury/property liability. Compare actual live-cargo, ownership, carrier, and buyer terms; liability for illness or damage to others is a different inquiry.
No. Actual assistance eligibility, bird/egg inventory, valuation, approval, and specified costs differ from private property/mortality and income cover. Do not assume a movement restriction, destruction order, all dead birds, or every lost hatch/order receives the same response.
Use available supplier/receipt, batch, hatch, health, and control records to explain condition and timing. Compare proposed causes and egg/animal, stock, guarantee, and income terms; low hatchability alone does not establish insured spoilage.
Identify carrier/custody, route, delay, condition/arrival, loss, replacement, and who owns eggs or birds in transit. Vehicle liability and selected physical damage do not establish live-cargo or fulfillment guarantees.
Incubation and day-old dispatch add fertile-egg, hatchability and live-shipment questions. Declare any layers, breeder flocks, grow-out, or food-egg sales as well; one farm label does not establish protection for combined work.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.