

Falls from roofs and ladders
Accessing chimneys requires roof and ladder work in varied weather, exposing sweeps to serious fall injuries.
Try a different word, or check the spelling.
Your inspection can influence whether a customer uses the fireplace again. Liability for that judgment deserves attention as well as protection for the cameras and brushes you carry.
The Southern Agency can help you align your insurance with the physical and professional risks involved in chimney maintenance.
You clean and inspect residential chimneys, which requires rooftop access and safety judgment. An incomplete inspection or a cleaning mistake can lead to a later house fire, causing significant liability for your business.
The Southern Agency can review your service procedures and rooftop activities to help you select appropriate insurance. For example, we can help you choose coverage for property damage that might occur in a client’s home while also addressing the professional risks of your inspection judgments.
Accessing chimneys requires roof and ladder work in varied weather, exposing sweeps to serious fall injuries.
An overlooked creosote buildup or undetected flue crack can be linked to a later chimney fire or carbon-monoxide event.
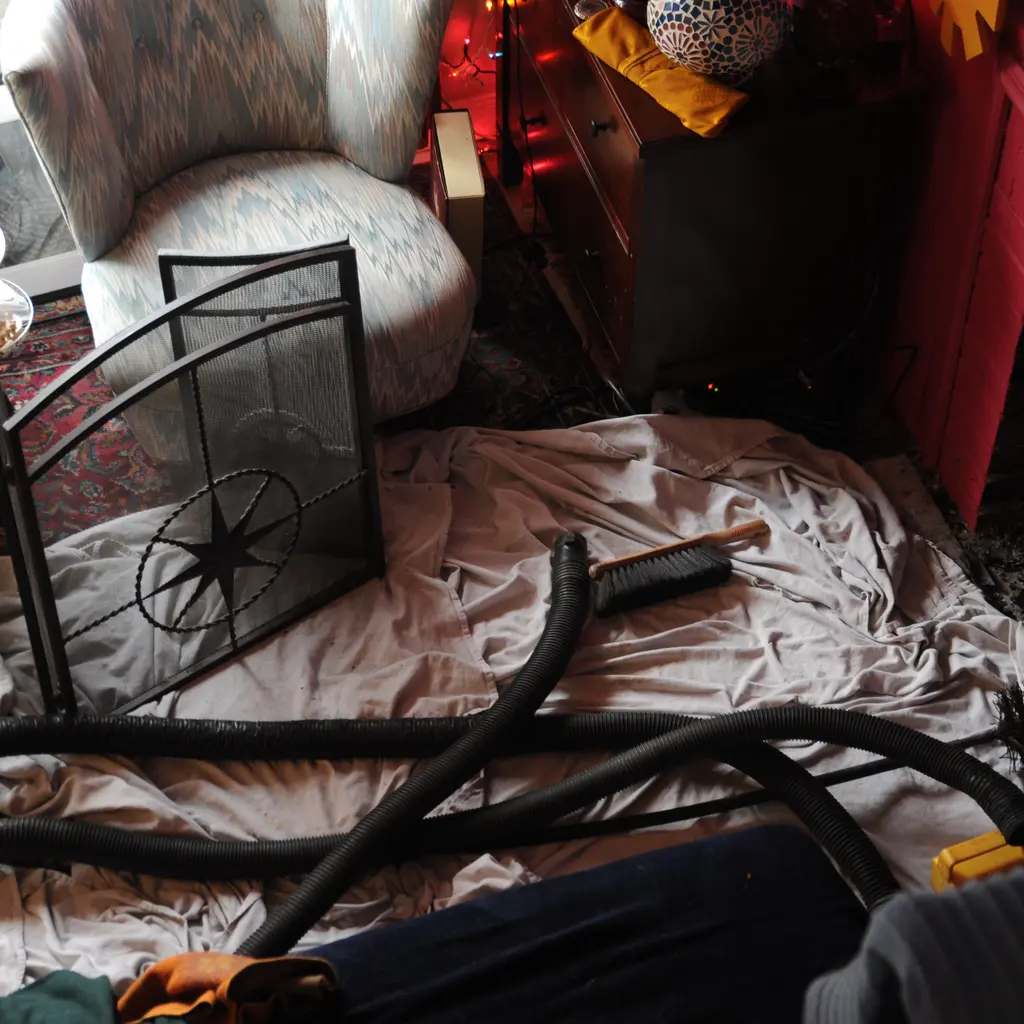
Cleaning and vacuuming inside occupied homes can spread soot or damage flooring, furniture, and belongings.
Customers rely on inspections for safety, so a serious incident may prompt allegations the contractor's work fell short.
Removing and disposing of creosote and ash creates air-quality and waste-handling exposure on the job.
Inspection cameras, vacuums, brushes, and rods travel between jobs and are exposed to theft and damage.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a homeowner alleges a recent cleaning missed creosote before a chimney fire. Notify the relevant liability insurers for review: physical fire damage, a missed inspection finding and a professional-services exclusion can raise different questions. Preserve the agreed scope, findings, photographs and recommendations; the allegation alone does not decide GL or E&O response.
Hypothetical: soot reaches carpet and furniture during cleaning. GL may address covered damage to other property, subject to custody, work-scope and pollution provisions. Cleaning the chimney again and repairing resulting damage to a room are different costs.
Hypothetical: a technician falls while accessing a chimney. Workers' compensation may provide benefits for a covered employee injury under applicable law. Describe roof access, height and ladder practices accurately rather than assume a cleaning-only classification includes every repair or roofing operation.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Because customers rely on cleanings and inspections for fire safety. If they allege a missed defect contributed to a loss, professional liability may respond, subject to policy terms and underwriting.
GL may address covered damage to surrounding carpet or furniture, but compare soot or pollution provisions with the actual cleaning method and property in your care or being worked on. Recleaning the chimney, replacing a damaged customer item and cleaning affected rooms are not automatically one covered expense.
Workers' compensation may provide qualifying benefits for an employee's roof or ladder fall. Identify actual employers, duties and work states, including owners and subcontracted repairs. Do not infer that a sweeping-only description covers all masonry, relining or roof work; protection for another firm's worker needs separate liability review.
Inland marine coverage may respond to theft or damage of cameras, vacuums, and rods that move between jobs, subject to scheduled limits and policy terms.
Relining, masonry repair, and cap installation add exposures beyond cleaning. The right structure depends on the work performed and underwriting.
Underwriters weigh the services offered, payroll, height work, vehicles, and claims history. Coverage availability depends on underwriting and operations.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.