

Subcontractor coordination liability
As general contractor, the office builder can be drawn into injury and property-damage claims arising from the many trades working on site.
Try a different word, or check the spelling.
Tenant move-in dates can be set before you finish the building's glazing and systems. Protecting high-value work in progress needs to be considered separately from promises about the completion date.
The Southern Agency can help you align your insurance with the schedule-driven and physical risks of high-end office construction.
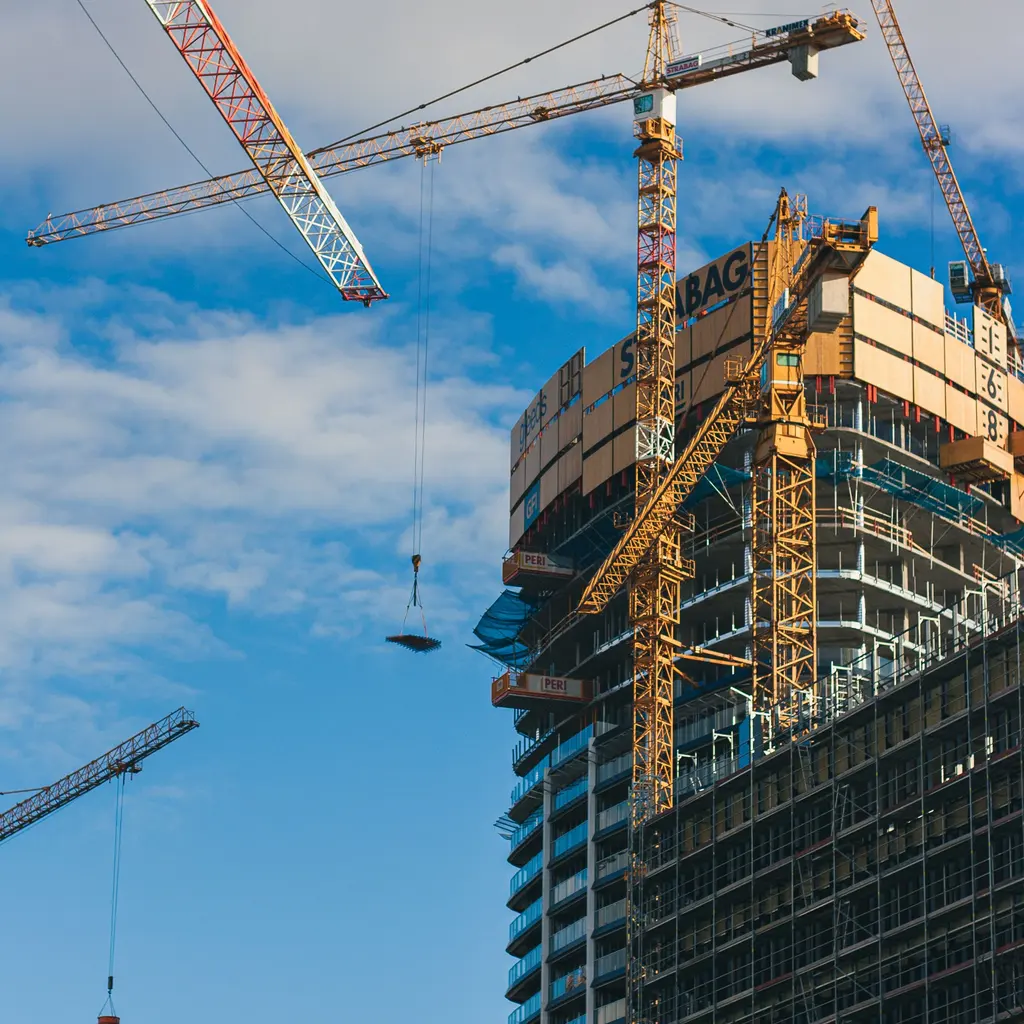
You build complex commercial office spaces, coordinating various trades to meet tight deadlines. Projects involving glass curtain walls or mechanical systems on busy urban sites create high risks of falling materials, fire, and costly scheduling delays.
The Southern Agency can review your construction project requirements and site management to help you select appropriate insurance. For example, we can help you choose coverage for high-value building systems.
As general contractor, the office builder can be drawn into injury and property-damage claims arising from the many trades working on site.
Large glass systems create falling-glass risk to people below and water-intrusion claims if the building envelope is not sealed correctly.
Fire, windstorm, or theft of high-value materials like copper, HVAC, and elevators can cause major loss to a building in progress.
Cranes, hoists, and deliveries near sidewalks and adjacent buildings raise the risk of striking pedestrians, vehicles, or neighboring property.
Lease-driven deadlines mean a covered loss or delay can expose the builder to liquidated damages and owner claims.
Building-envelope, structural, or systems defects may surface after occupancy and lead to costly repair and litigation.
An owner or lender may request performance or payment bonds, particular forms and approval before award or mobilization. Compare the actual obligation and timing; a request does not establish available capacity or insure every delay.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: a panel breaks free during curtain-wall installation and damages property below. GL may address covered third-party damage, subject to crane, glazing, subcontractor and other applicable terms. The panel and unfinished facade are separate property interests from the passerby's property.
Hypothetical: rooftop HVAC units staged for a nearly complete office building are stolen before installation. Builders risk may address covered theft of insured materials. Confirm ownership, values, storage, security and coverage dates; testing or phased occupancy can affect terms before final handoff.
Hypothetical: water enters through the envelope after tenants move in and damages interior finishes. Separate correcting the facade from resulting damage and any tenant loss-of-use claim. Completed-operations coverage is not automatically a warranty for the envelope or payment for contractual lease-delay charges.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Compare site and completed-work liability, actual crew benefits, vehicles, mobile equipment and project property. Glazing, public access, testing, tenant occupancy and owner bond requests affect the review. The mix and availability depend on actual scope and contract duties, not a standard office-builder package.
Read the actual owner or lender request, required form, obligee and timing. Performance and eligible subcontractor or supplier payment are different obligations, subject to approval and capacity review. A bond does not replace liability or project property insurance, and surety indemnity can require reimbursement.
Curtain-wall work creates falling-glass exposure to people and property below. General liability may respond to resulting third-party claims, depending on policy terms and the facts of the incident.
Water intrusion and envelope defects can surface after occupancy. Whether a policy responds depends on completed-operations terms, exclusions, and the specific facts, so contract and warranty language matter.
Builders risk may help protect materials and systems staged or installed during construction against fire, wind, and theft, subject to the limits and terms disclosed in the policy.
Pricing commonly reflects contract value, building height, glazing scope, site logistics, payroll, bonding needs, and claims history. A tailored quote reflects how your specific projects are built.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.