

Falls from roofs and ladders
Working on pitched surfaces, ladders, and scaffolds exposes roofing and siding crews to serious falls.
Try a different word, or check the spelling.
Your roofing and siding meet at details that must keep the rest of the building dry. Coverage needs to address the transition from exposed tear-off work to a finished exterior, not just the tools on the truck.
The Southern Agency can help you protect your business against the risks of working on building envelopes and heights.
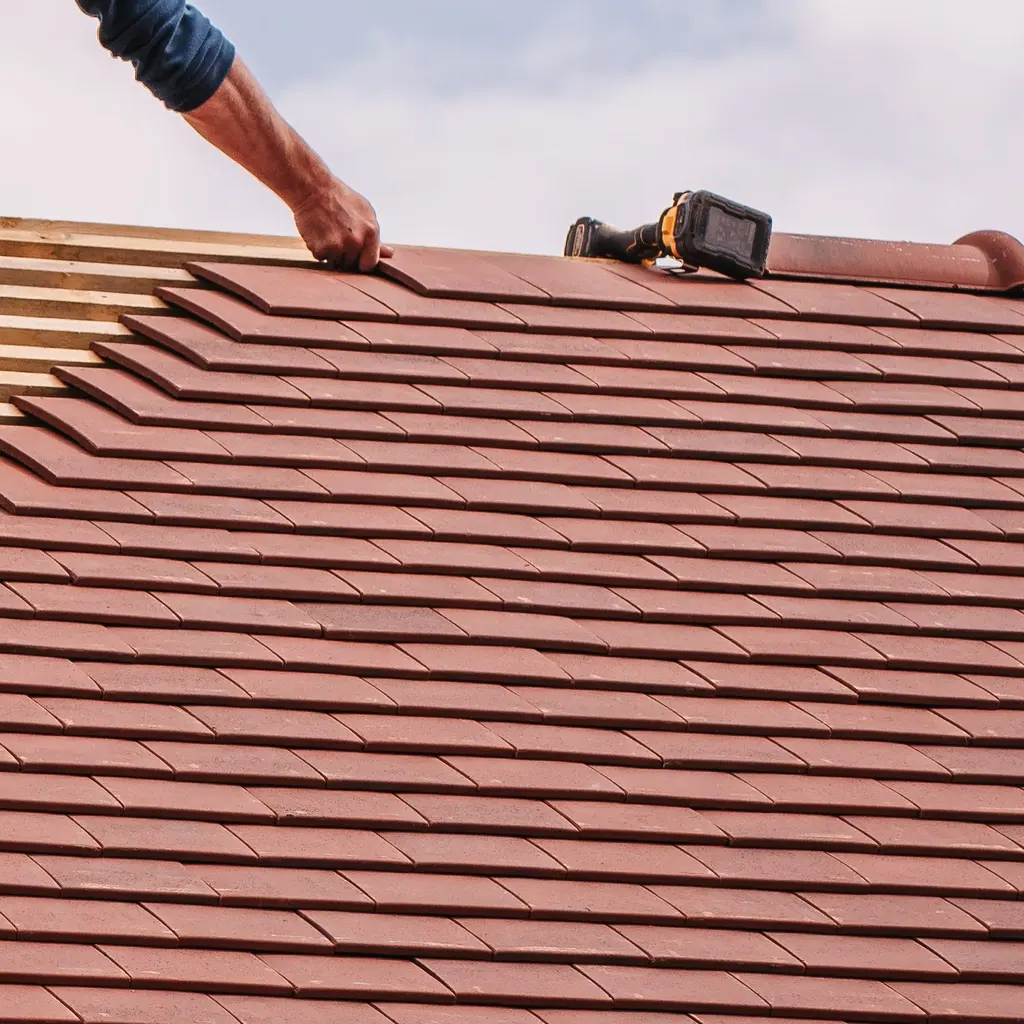
You install and replace exterior cladding and roof systems, working at heights and managing the building envelope from tear-off to final seal. An unfinished roof left during a storm or a faulty exterior interface can lead to interior water damage and property claims.
The Southern Agency can review your roofing and siding mix, including your temporary weather-protection methods, to help select appropriate insurance. We can discuss how to protect your team and your business against risks like falls or property damage caused by falling materials while you work on building exteriors.
Working on pitched surfaces, ladders, and scaffolds exposes roofing and siding crews to serious falls.
A torn-off or in-progress roof leaves the interior exposed, and sudden rain can cause significant water damage to the structure and contents.
Torch-down and heat-welded membrane work can ignite roof materials or the building, leading to fire damage claims.
Tear-off debris, fasteners, and dropped tools can strike people, vehicles, and landscaping below the work area.
Improper flashing or fastening can let water intrude after the job, prompting completed-operations and warranty claims.
Compressors, nail guns, ladders, and lifts moved among job sites are exposed to theft and damage in transit and on site.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: rain enters during tear-off and damages ceilings and contents. Review actual roof stage, temporary protection, water-entry dates and accepted open-roof/work-property terms. Unexpected weather alone does not establish liability or coverage; replacing roof work and resulting interior harm are separate.
Hypothetical: a crew member falls from a sloped roof. Workers' compensation may provide qualifying benefits under applicable law and actual employment duties. Identify employer/subcontractor status, height and method; a labor certificate or GL/excess limit does not settle benefit responsibility or approve the work setup.
Hypothetical: a dropped tool dents a customer's parked car below the exterior work. GL may address covered resulting damage under accepted operations and property terms. Keep location and trade-control records; the tool itself, employee injuries and correcting the roof or siding are different interests.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Describe roofing/siding mix, height/pitch, access and hot-work methods and labor arrangements. These affect review, but a strong safety program or a request for higher limits does not establish accepted operations or availability.
First separate liability from insurance. Record the tear-off/protection stage, cause and dates, existing conditions, and interior damage. Fault depends on the facts and duties; any GL response still needs accepted work and water/work-property/exclusion review.
Torch and hot-air work can ignite the building. Disclose the exact methods and check hot-work exclusions/conditions; a permit, safety practice or GL certificate does not by itself establish accepted fire exposure.
Inland marine coverage may help protect ladders, nail guns, compressors, and lifts in transit and on site, depending on the specific policy and limits.
Preserve work/handoff, water-entry/damage, and discovery/claim dates. A later leak or callback does not itself trigger completed operations. Separate correcting the roof/cladding from resulting damage, then review terms, exclusions, and warranty obligations.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.