

Weather damages widespread arrays
Hail and wind can affect many modules in one event.
Try a different word, or check the spelling.
Your panels can remain physically usable while a shared electrical component stops their output. Breakdown and generation-income protection need to address that dependency separately from the weather terms on the array.
The Southern Agency can help you compare array weather terms, electrical bottlenecks and actual damage-related generation-income needs.
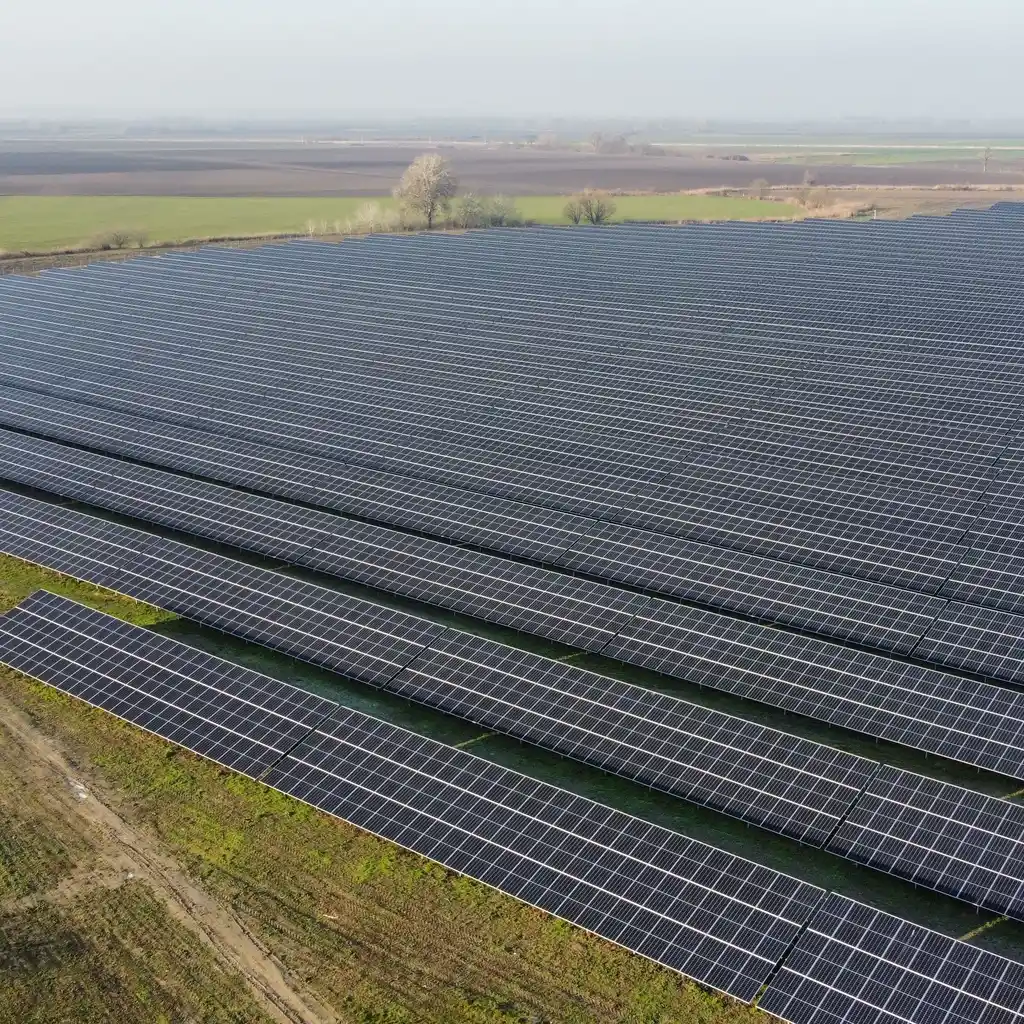
You generate electricity using solar arrays, inverters, and grid connections. Weather events like hail can damage panels across an entire field, while an inverter failure can stop your power output.
The Southern Agency can review your array and interconnection assets to help you select appropriate insurance. We can discuss how to link repair coverage for inverters and modules with protection for the income lost during an insured shutdown.
Hail and wind can affect many modules in one event.
A common electrical component can idle otherwise usable panels.
Modules and copper can be lost from operating sites or staging areas.
Faults, vegetation and maintenance can expose employees and neighbors to injury or damage.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Hypothetical: hail damages modules across part of the field. Property may address covered damage under the actual site deductible, hail sublimit and replacement/valuation terms. Undamaged modules are not automatically replaced to match, and selected lost-generation terms must address the affected output separately.
Hypothetical: an internal inverter failure idles otherwise usable panels. Breakdown may address a qualifying fault of declared equipment, with selected income terms assessing actual lost earnings and restoration. Compare spares and supplier lead times; deterioration, warranty replacement and every performance shortfall are not automatic additions.
Hypothetical: copper is stolen from a remote operating section. Property terms may address covered theft at that location under actual interests, values and security conditions. Distinguish fixed cabling from staged shipments and any repair-related income loss; a construction transit form does not establish all operating-site protection.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Review array property, machinery, site liability and employees, adding transit/installation protection for the actual project phases.
Only insured causes and limits qualify. Hail/wind deductibles, sublimits, and exclusions need specific review.
Suitable property or transit terms may help, depending on location, insured interest, cause, and security requirements.
Qualifying inverter or transformer failures may be included; wear and defective performance are separate questions.
Selected income protection can address covered damage-related loss. Clouds, normal weather variability, and every grid curtailment are not automatically covered.
Assess employees and contractor arrangements under applicable rules; a maintenance contractor's personnel are not automatically plant employees.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.