

Freight condition
Wetted grain or contaminated bulk freight can bring cargo-owner demands. Load condition, commodity, hatch duties and custody handoffs matter; a damaged load is not automatically the carrier's full-value liability.
Try a different word, or check the spelling.
Your tow's route involves bridge and lock owners alongside the parties to a freight contract. Marine liability and cargo protection should address those different interests and accepted commodities, with excess expressly following the relevant underlying forms.
The Southern Agency can review your barges, towing and carriage agreements with you before comparing marine and shoreside interests.
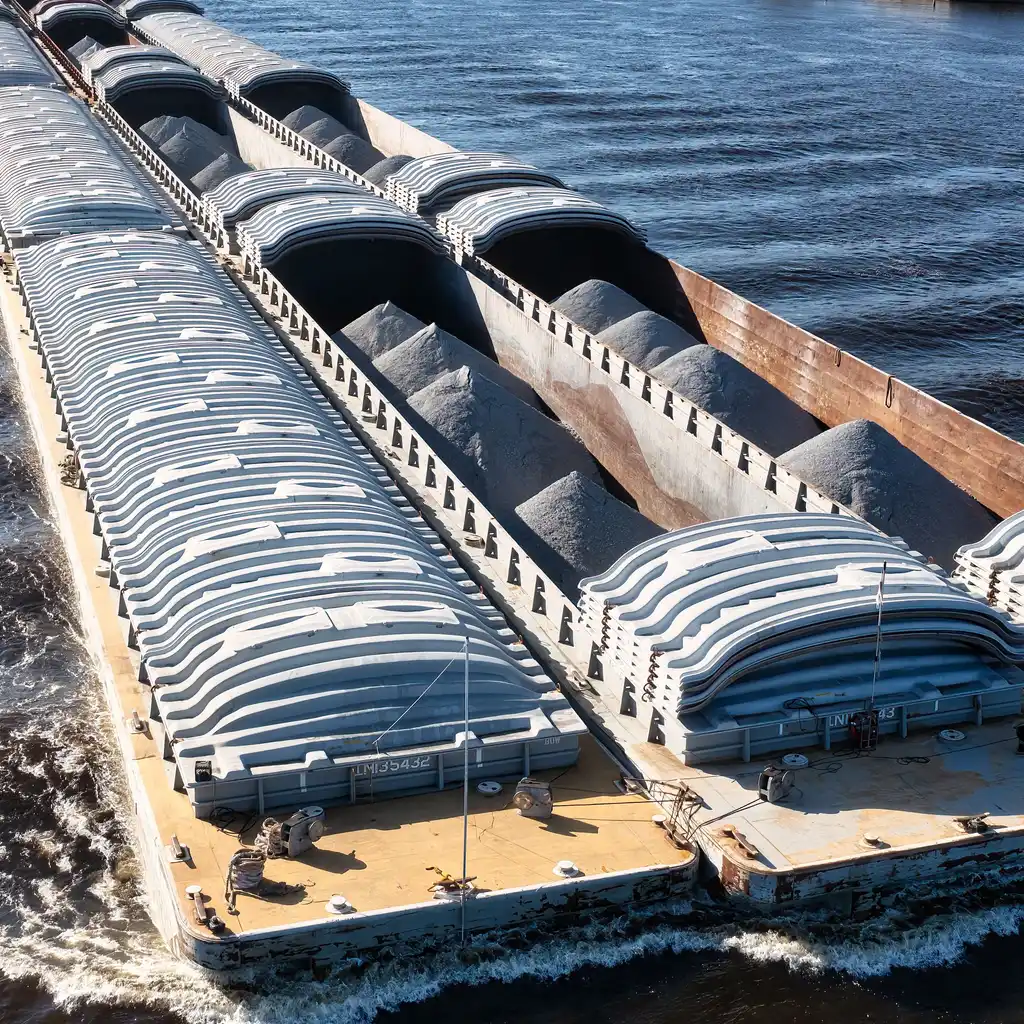
You move freight through rivers, locks and fleeting areas, with responsibility shaped by your towing and carriage arrangements. Water can damage a load, while a tow striking a structure can create a separate claim for damage to someone else's property.
The Southern Agency can review your carrier role, vessels, and freight responsibilities to help you select insurance. We can discuss cargo interests and marine liabilities separately from shore assets, using the actual handoffs and tow operations to guide the comparison.
Wetted grain or contaminated bulk freight can bring cargo-owner demands. Load condition, commodity, hatch duties and custody handoffs matter; a damaged load is not automatically the carrier's full-value liability.
A breakaway or sinking can affect the barge, freight and other vessels or structures at once. Owned hull, salvage/removal obligations, cargo and operating liability are different insured interests.
A loaded tow striking a bridge or lock can damage the structure and interrupt navigation. The tow and terminal roles, navigation accepted and marine liability terms matter beyond ordinary shoreside GL.
Coupling, line handling and cargo or fleeting work expose crews and shore handlers to different injuries and legal arrangements. Actual employer and duties matter; being near water does not decide every worker's cover.
Fuel or liquid cargo escaping after damage can involve cleanup and other-party claims. The material, place and insured responsibility differ from repairing handling equipment or replacing the cargo.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose grain arrives wet after water enters a barge. Compare the insured carriage duties, evidence of cause and load condition, commodity, voyage and valuation. Direct cargo insurance and the carrier's legal liability are different; neither a bill of lading nor the owner's demand proves full-value payment.
Suppose a tow contacts a bridge and damages a pier. Compare the operator, tow arrangement, accepted navigation and marine operating liability with the claim. Repairing the barge, damaged freight and bridge liability require separate interests; a shoreside GL label is not marine acceptance.
Suppose collision damage releases fuel into the river. Establish the fuel owner, responsibility, location and release cause, then compare accepted cleanup/other-party terms, notice and consent. Routine fuel handling, fines and every removal bill are not automatic benefits.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Start with actual barge/tow roles, waters, commodities and employers. Review hull/machinery, cargo, marine operating liability, crew and pollution interests separately from shore equipment. Ordinary inland marine or premises GL is not a substitute for marine forms that accept your barge and carriage duties.
Keep load-condition, hatch, voyage and handoff records and the carriage agreement. Responsibility depends on facts, contract and applicable rules. Compare direct cargo versus carrier-liability interests, commodities, causes and valuation; damage and a declared value do not automatically make you liable or insured for the whole load.
Identify the towing/operating parties, structure damaged and accepted navigation. Compare marine operating liability, limits and relevant excess with separate hull and cargo interests. A tow contract or ordinary premises GL does not itself insure a bridge or lock claim.
Describe each employer, vessel and shore tasks and where work occurs. Have actual maritime crew and shore-worker arrangements reviewed under applicable rules; ordinary state workers' compensation should not be assumed to cover every tow or terminal duty.
Disclose the actual product, quantities, vessels, transfer stages, fuel and cargo responsibilities and prior releases. Compare accepted pollution conditions, cleanup/other-party costs, notice and consent with cargo terms. Petroleum carriage does not establish all spill, replacement or regulatory costs insured.
Yes. Bring each charter's condition, repair, return, hull, operating and indemnity duties and identify who tows and fleets the barge. Compare insured entities and interests with actual marine terms; a charter does not add cover or guarantee every obligation can be placed.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.