

Concentrated stock
A fire, smoke, or covered water loss can damage bottles and packaging. Product composition and stock quantities matter; insurance valuation is not automatically retail selling price.
Try a different word, or check the spelling.
The selling price on a fragrance gift set may not be the insured value of the bottles and packaging. Your stock protection needs that valuation and the actual composition and quantities, with sampling injuries, recalls, and unexplained missing bottles considered separately.
The Southern Agency can review your holiday stock, tester practices and actual theft and valuation terms with you.
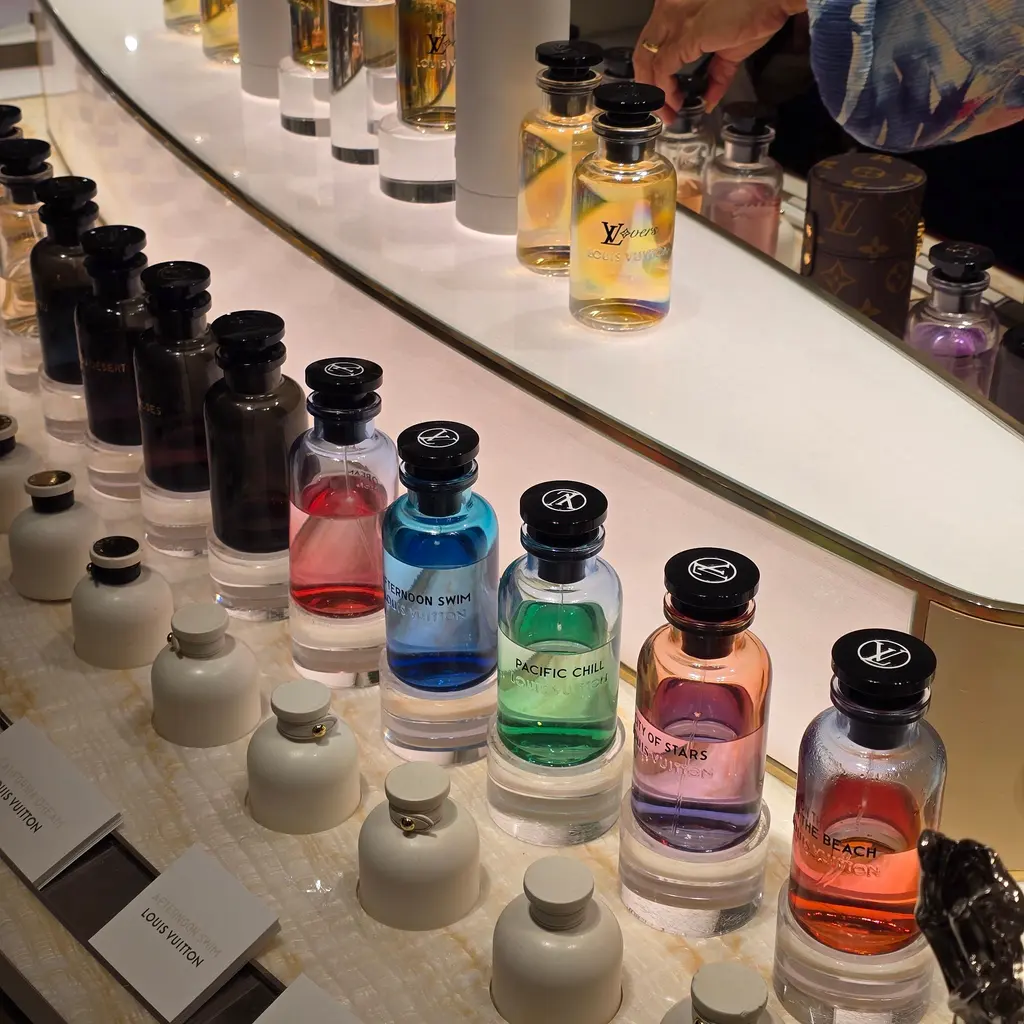
You sell fragrances and gift sets, often with testers and samples to help customers choose. A broken bottle can leave damaged stock and an injury claim; a missing bottle and a customer reaction call for different evidence and insurance terms.
The Southern Agency can review your actual products, stock values and sampling with you. We can compare accepted premises/product claims with stock causes, theft evidence and written valuation, alongside payment-data duties and any purchased interruption benefits.
A fire, smoke, or covered water loss can damage bottles and packaging. Product composition and stock quantities matter; insurance valuation is not automatically retail selling price.
Burglary, employee theft, and an unexplained stock difference are separate losses. One crime label does not insure every missing bottle.
A reaction or slip during sampling may produce an injury claim. Payment systems and customer accounts introduce separate privacy costs.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
Suppose burglars take fragrance stock and damage a door. Compare actual owned/leased property and stock theft with valuation, proof and security terms. Selected crime clauses may address a different interest; neither a missing count nor two policy names guarantees payment.
Suppose a customer alleges a tester caused a skin injury. Compare actual product/sampling duties and accepted injury terms. The reaction does not itself establish negligence; any medical payments, product refund or recall have different provisions.
Suppose a fire damages stock and closes the shop during a holiday period. Compare accepted property damage/valuation with purchased qualifying income, actual lost sales and waiting/restoration limits. Seasonal turnover does not establish every sale, bottle's selling price or closure expense paid.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
Do not assume it. Merchandise theft may belong under property terms, while crime sections insure specified acts and interests.
No. The allegations, injury, and liability terms matter. Medical payments, if included, have separate conditions.
Not necessarily. Confirm replacement-cost, actual-cash-value or other valuation terms.
A processor does not eliminate all exposure. Review what systems and information the shop and vendors handle.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.