

Installed products
A defective valve or heater can allegedly cause leaks or scalding after sale. Replacing the defective item differs from paying for injury or damage to a building.
Try a different word, or check the spelling.
A valve can be blamed for a building's water damage long after it leaves your counter. Review product claims alongside your actual supplier and installation roles, rather than treating replacement of the fitting as the whole loss.
Talk with The Southern Agency about your operation, policy terms, and the information carriers need.
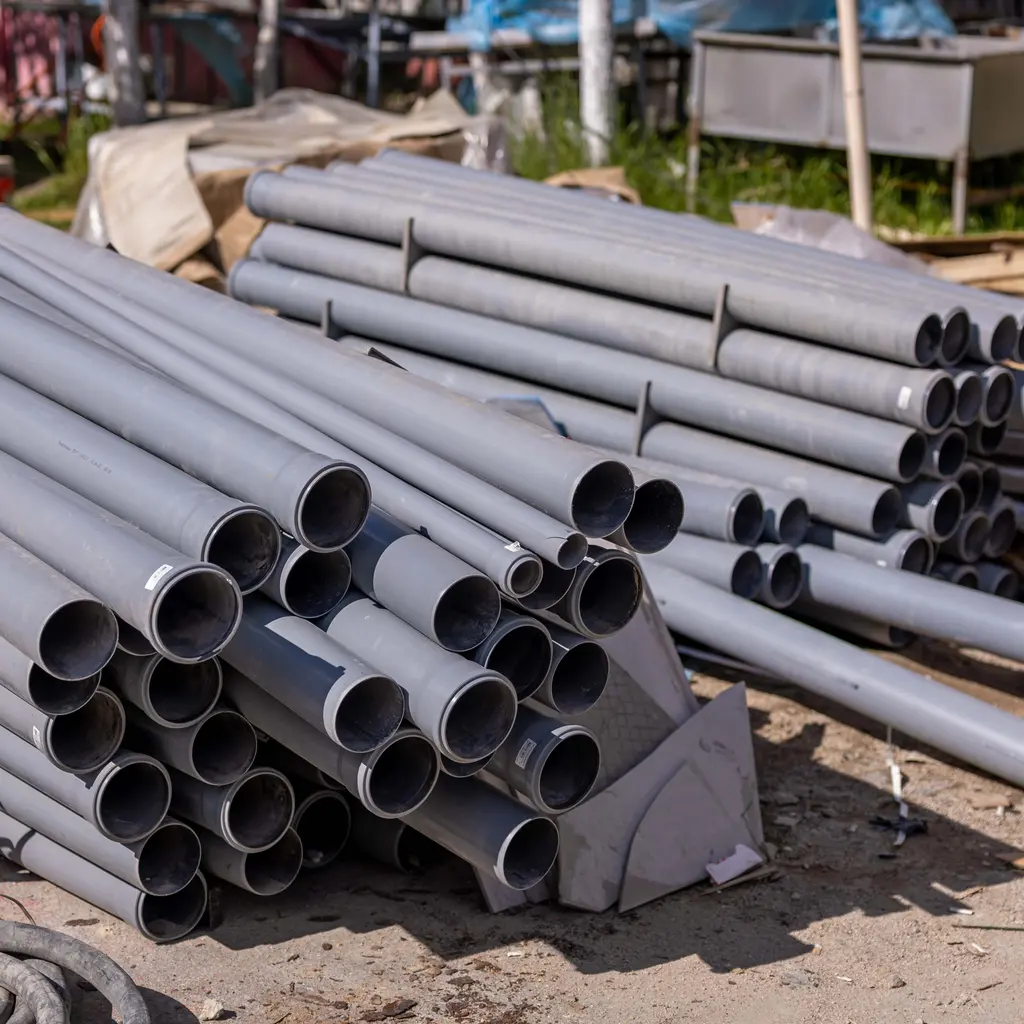
You distribute heavy pipe, fixtures and water heaters from your warehouse to delivery trucks and contractor customers. A dropped fixture during loading or a delivery accident can cause expensive damage to both your property and your customers' supplies.
The Southern Agency can review your warehouse racking, delivery vehicles, and distribution operations to help you select appropriate insurance. We can discuss how inland marine coverage helps protect your cargo and how products liability addresses claims involving distributed materials.
A defective valve or heater can allegedly cause leaks or scalding after sale. Replacing the defective item differs from paying for injury or damage to a building.
Forklifts, long pipe, and heavy fixtures create loading and injury hazards. Vehicle, cargo, and unloading terms need coordination.
Water can damage packaged or electronic stock. Account-data compromise differs from a contractor simply failing to pay.
Policies to ask about. Which ones fit depends on your operations, your contracts, and the carrier’s forms.
These hypothetical examples are not agency claim results. Whether a loss is covered depends on the facts, policy terms, and applicable exclusions.
A sold valve allegedly fails and damages a customer's building. Products coverage may address covered resulting damage, but replacing the valve itself and the installer's work have separate limitations.
A forklift load injures a visiting contractor. General liability may address a covered visitor claim; an employee injury instead raises workers compensation questions.
A pipe leak damages packaged units. Property may pay if the water cause qualifies, subject to valuation and exclusions; flood is not the same cause.
Start with the work you do and the questions your current policies leave unanswered. Carrier options depend on your location, risk, and underwriting. Explore our approach.
A dealer can be named in a resulting injury or damage claim. Liability is not established solely by the sale, and replacing the item is a separate cost.
Not by itself. Cargo or transit insurance must cover the goods and insured interest.
Ordinary credit default is different from a covered data or fraud incident.
No. The specific cause, entry conditions, exclusions, and limits matter.
Bring your questions, current policies, and relevant contracts. An agent can review coverage terms, exclusions, and the information carriers ask for, then explain the options available to you.